


The IRRs delivered by the strategy since 2017 have been impressive. The asset class is coming under scrutiny but will aim to prove the doubters wrong.
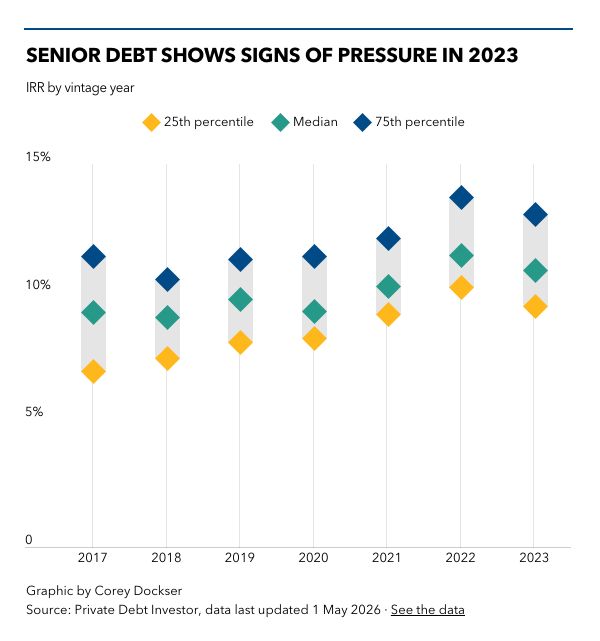
It’s been a good time to be investing in senior debt, as indicated by our proprietary chart showing top quartile, bottom quartile and median performance from 2017 to 2023 (the latest vintage for which we have meaningful performance figures).
While top-quartile internal rates of return have ranged from 10.5 percent to 13.7 percent across those vintages, even bottom-quartile funds have seen respectable performance of between 6.9 percent and 10.2 percent. A rising tide has indeed floated all boats.
But while the performance remained good among 2023 vintages, the returns were down across all quartiles compared with 2022 – providing a hint that some of the pressures funds were facing in relation to a challenging economic and geopolitical backdrop may have started taking a toll.
In our Q2 State of the Market report, we challenge the notion that the asset class is facing some kind of crisis – a view that some in the mainstream press appear keen to encourage. Redemption pressure in the BDC market appears to have been triggered by the “noise” rather than portfolio fundamentals.
Meanwhile, in the much-maligned software sector, there will be winners and losers – even though all we hear about is the losers. Anecdotally, the message coming from numerous fund managers is that – up to now at least – software is often the best-performing part of the portfolio. There are also regional disparities – in Europe, software exposure tends to be much lower than in the US.
Where challenges exist, they are of a much more prosaic nature than the cataclysmic crises predicted by some. The focus on underwriting and credit risk needs to be sharper than ever in the face of ‘potential’ AI disruption, for example.
Moreover, there are valid concerns about payment-in-kind and the extent to which an inability to service debt interest can be disguised or forgiven. Maybe vintages beyond 2023 will show the signs of stress that is increasingly assumed to be within portfolios but not yet evident. But who knows? Private credit over the years has shown a tendency to surprise on the upside.



Latest news

Open Tab
Leveraged loans keep running up a tab. Senior direct lending already knows what it owes.


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.