


Delegates at the recent Europe Summit heard views on how different parts of the market will weather the challenges.
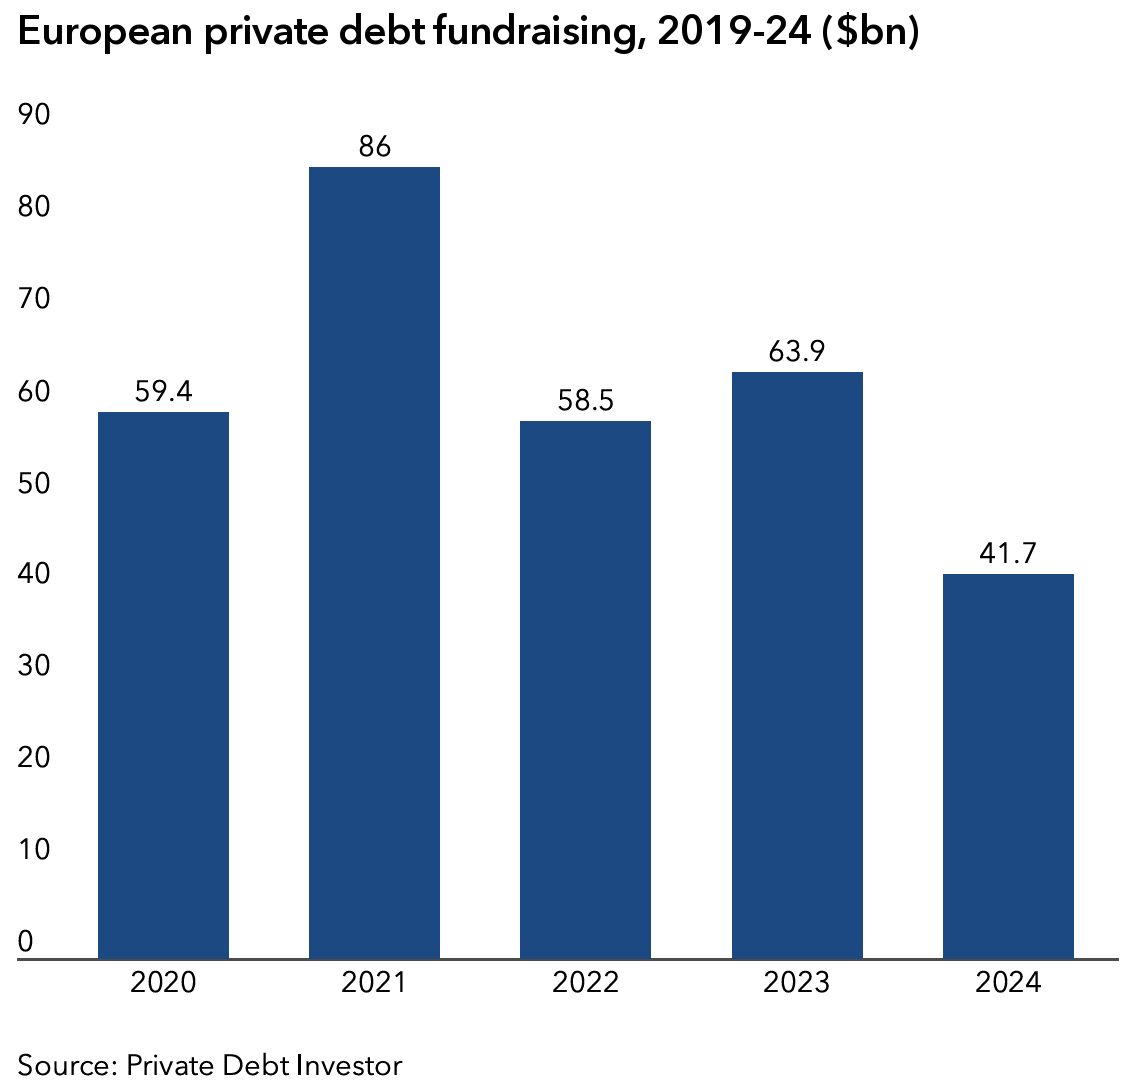
Our recent Private Debt Investor Europe Summit drew LPs, GPs and advisers from all corners of the globe, keen to discuss a rapidly changing environment and what they should be celebrating and fearing. While Europe has struggled on the fundraising front in recent years (see chart) there was plenty of optimism in the room.
Fund managers specialising in smaller businesses had a message for investors – our target market is not as exposed to the policy vagaries around tariffs because, for businesses largely or exclusively focused on domestic markets, long supply chains are simply not a potential hazard. That’s not to say of course that these borrowers won’t find themselves under pressure in an economic downturn.
For those operating at the larger end of the market, doubling down in what are perceived to be the most resilient sectors is the order of the day – software, healthcare and business services are only likely to attract even more fans.
Given the level of stress in portfolios due to pressure on borrowers from inflation, higher interest rates and an unhelpful geopolitical backdrop, it is not surprising that investor scrutiny of direct lending is heightened. But how easy is it for them to detect tell-tale signs of stress – or even separate real stress from imagined stress?
“You need big teams with good processes to assess private credit portfolios,” said Orla Walsh, managing director and portfolio manager in Barings’ Global Private Finance Group. “One challenge is to assess what’s a positive ‘amend and extend’ and what’s not: it might be a growing business that can be helped to grow further; or it might be a fundamentally good business that has deviated from its base case and there’s more leverage than there should be.”
The secondaries market bucks the trend in expecting strong deal flow through this year as a lack of M&A activity amid volatility prompts LPs to scan their books for assets they can sell without having to accept a big discount. In many cases, private debt is the answer as there has been no material decline in pricing according to those in the market.
This is not to say secondary buyers have no concerns – deep diving into underlying assets is no easy task when a private debt portfolio may have so many individual loans. How confident can a buyer be of resilience to a downturn?




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
