


Despite talk of Europe becoming the new fundraising magnet, the data is not showing any significant change in LP appetite.
There has been much written about the attractions of European private credit of late. Moreover, the region’s perceived strengths are frequently compared with the challenges facing aspects of the North American private credit market – with the resulting narrative that a redirection of investor capital flows away from North America and towards Europe may be expected.
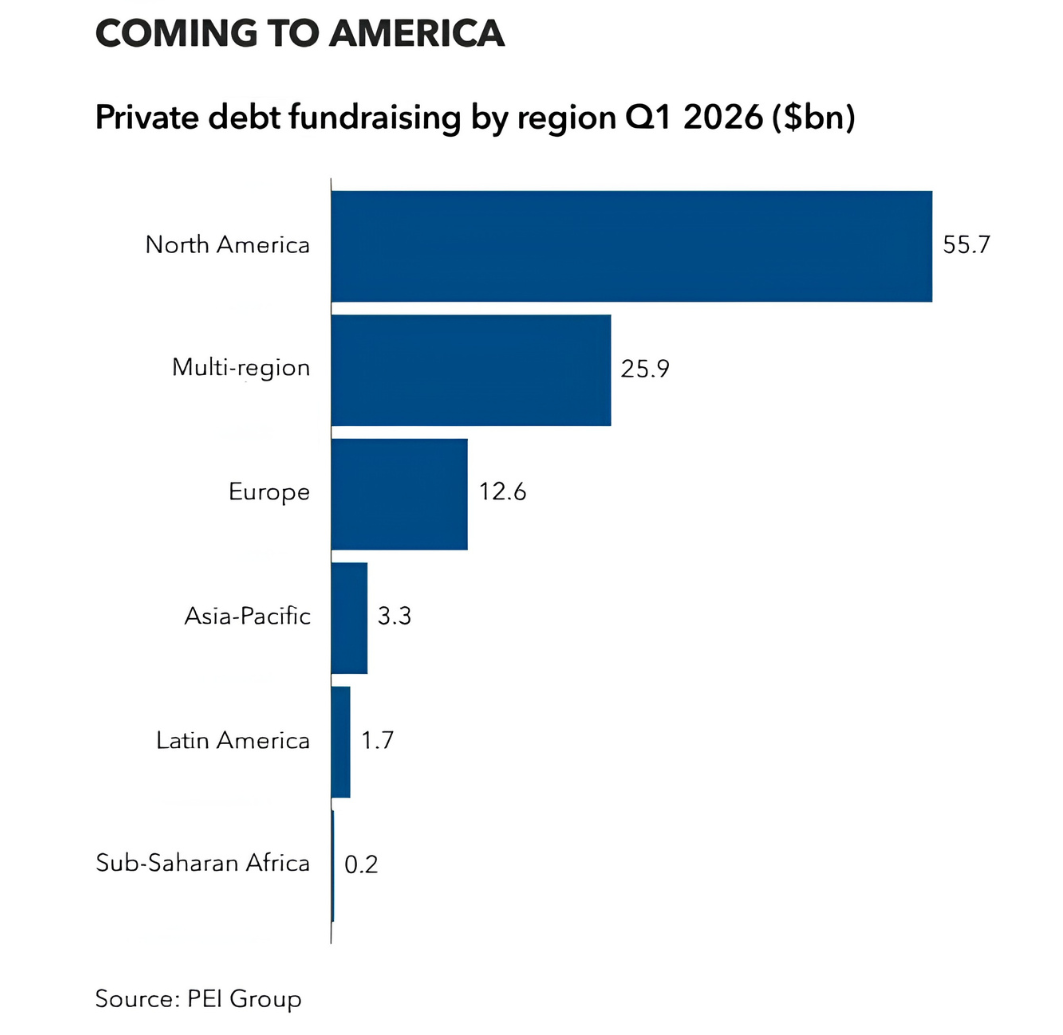
There’s only one problem with the theory: it’s only a theory. When you look at the data, it appears that institutional investor confidence in North America is remaining rock solid. After many years of North America being easily the most favoured region for investors, the first quarter of this year continued the trend (as can be seen from the chart above).
Of course, much of the “noise” in North America has been in relation to specific issues – largely surrounding retail investment through the BDC market and levels of exposure to AI-threatened parts of the software sector. Institutional investors may have concluded that these issues are too peripheral to affect their long-term, strategic allocations to the asset class.
There were indications, however, that investor sentiment may be changing in our latest Investor Report, published in January this year. It reinforced the sense that Europe stood to be the recipient of increased capital inflows – with 42 percent of investors surveyed saying they had a greater interest in the region. By contrast, only 17 percent had a greater interest in North America – below even the 19 percent figure for developed Asia-Pacific.
If there has been a change in sentiment, it has not yet been reflected in the data. With funds focused on North America currently actively raising almost $222 billion globally, according to Private Debt Investor data, these funds will be hoping that North America’s favoured status is maintained.



Latest news
Share of US private debt capital raised by strategy
In the US, buyout activity remained paltry, as deal count for direct lending LBO financings fell to its lowest level since Q3 2023 in the three months ended July 31, according to the latest US LCD Private Credit Monitor.
Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the dividend yield of the VanEck BDC Income ETF (BIZD), which rose 122bps over the month…

US middle market loan issuance weakened in 3Q26, despite a rebound in sponsored direct lending activity
Overall US middle market loan issuance weakened in 3Q26, although sponsored direct lending bucked the broader trend, rebounding from the…