


The asset class is moving beyond its traditional institutional investor base.
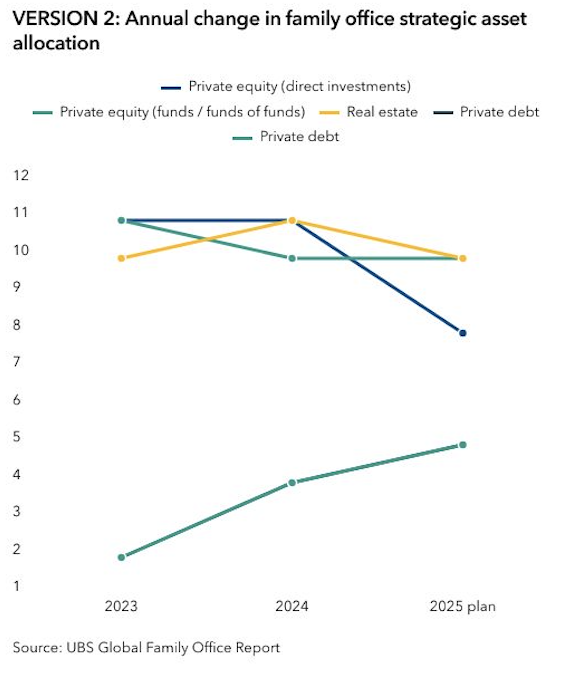
Where insurance firms, pension schemes and other institutional investors have ventured en masse, family offices are increasingly dabbling in what, for many of them, is a new area. Their average allocation to private debt doubled from 2 percent to 4 percent last year, according to UBS’s Global Family Office Study 2025 (see chart).
Private debt accounted for the biggest relative rise in allocation among private asset classes over the period, showed the survey of 317 family offices by the world’s biggest private bank. Meanwhile, private equity, the most popular alternative asset class among family investors, posted a drop in average allocation to 21 percent from 22 percent.
“[Family offices] are … increasing investments in private debt and some are looking to add developed-market fixed income possibly for enhanced yield and diversification,” the UBS report said.
Nedelina Lazarova, head of private debt at German multi-family office HQ Trust, with €17 billion in AUM, told PDI: “The clients of ours who have allocated to private debt tend to invest between 5 and 10 percent of their total allocation. As for clients who do not invest in private debt at all, more are showing interest. Overall, there is a greater interest in the asset class.”
US asset manager Russell Investments is also seeing a big rise in inquiries about private debt, but not yet in capital flows, said Keith Brakebill, Seattle-based senior portfolio manager for private credit.
Likewise, Jeffrey Griffiths, global head of private credit at placement agent Campbell Lutyens, said he was seeing increasingly strong interest from family offices across the globe. “I think as family offices see capital come back to them, they’re re-allocating into private credit, mostly from other illiquid private market asset classes.”
Lazarova said a number of HQ Trust’s clients had, in the last 12 months, pulled out of real estate equity and reallocated that capital to private debt.
Helping fuel this appetite are the liquidity and returns on offer from private debt, especially relative to private equity. “In this higher-interest-rate environment of the last three years, private credit returns have looked better than they ever have on a relative-value basis,” said Griffiths.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
