


There were some signs of improvement in the second quarter, but raising new private debt capital was still a struggle in the first six months of 2024.
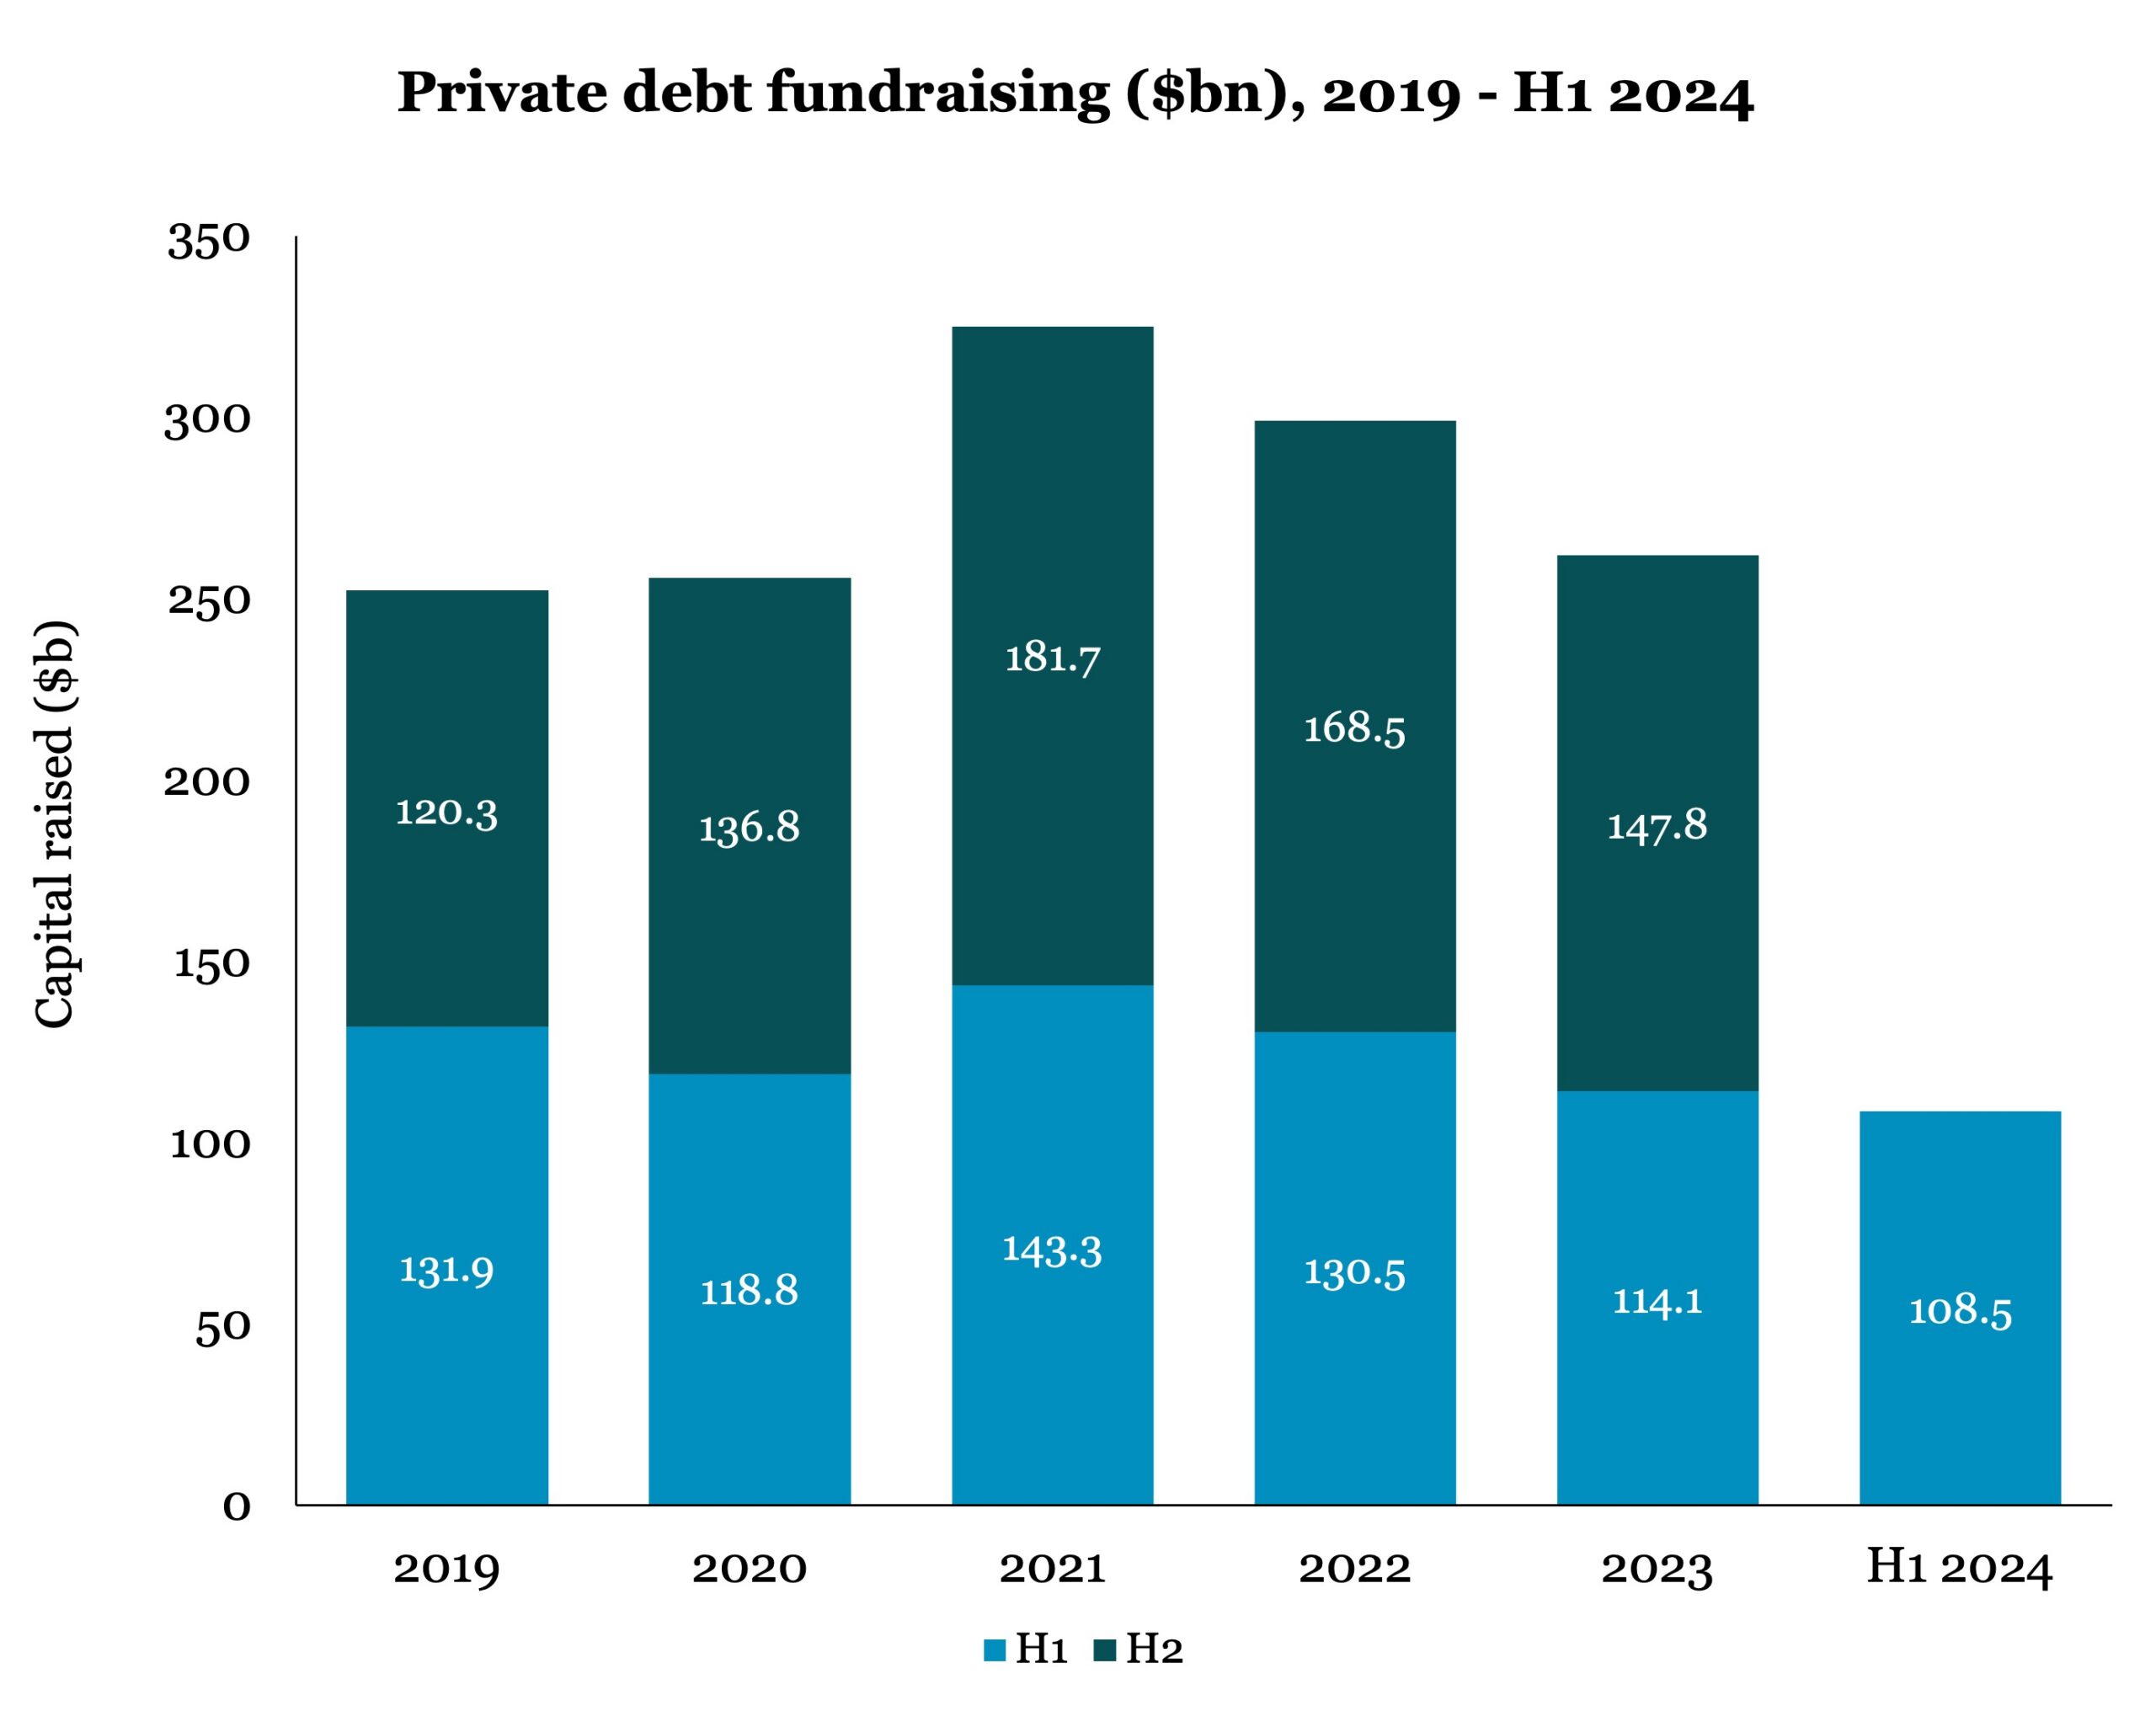
The first half of 2024 did not offer much consolation to those awaiting clear signs of a private debt fundraising revival. Private Debt Investor’s provisional data for H1 records $108.5 billion of capital raised – down on the $114.1 billion total in the first half of last year, and a significant decline on the $143.3 billion total in the first half of the peak fundraising year of 2021 (see chart).
However, there were signs of activity picking up in the second quarter, led by Goldman Sachs Asset Management’s $13.1 billion closing of West Street Loan Partners V in May and HPS Investment Partners’ $10.4 billion closing of HPS Specialty Loan Fund VI in June. Hopes are high that a revival will finally be seen in the second half of this year as the pressure on LPs hampered by a lack of distributions begins to ease and allocations begin to once again flow freely into an asset class which still retains favoured status.
In terms of strategy, H1 2024 saw a notable shift to senior debt strategies, accounting for 66 percent of the total capital raised. This squeezed the amount allocated to other private debt strategies, with subordinated/mezzanine debt seeing its share fall from 34 percent in full-year 2023 to just 14 percent. Distressed also saw a significant decline, down from 16 percent to 7 percent over the same period.
North America continued to lead the way in terms of geographical focus, accounting for almost $46.2 billion, with multi-regional strategies on nearly $40.3 billion and Europe coming next on just over $19.7 billion.
One well-established trend which has clearly continued into 2024 is that of more capital gravitating to fewer managers – boosting the size of favoured managers’ funds in the process. The first half of this year saw the average size of closed-ended vehicles rise to a record of more than $1.1 billion – ahead of the yearly record average size of $924.5 million in 2023.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
