


While this year’s sluggish junior debt fundraising numbers partially reflect the hollowing out of mid-market mezzanine investments, they also illustrate big firms getting bigger.
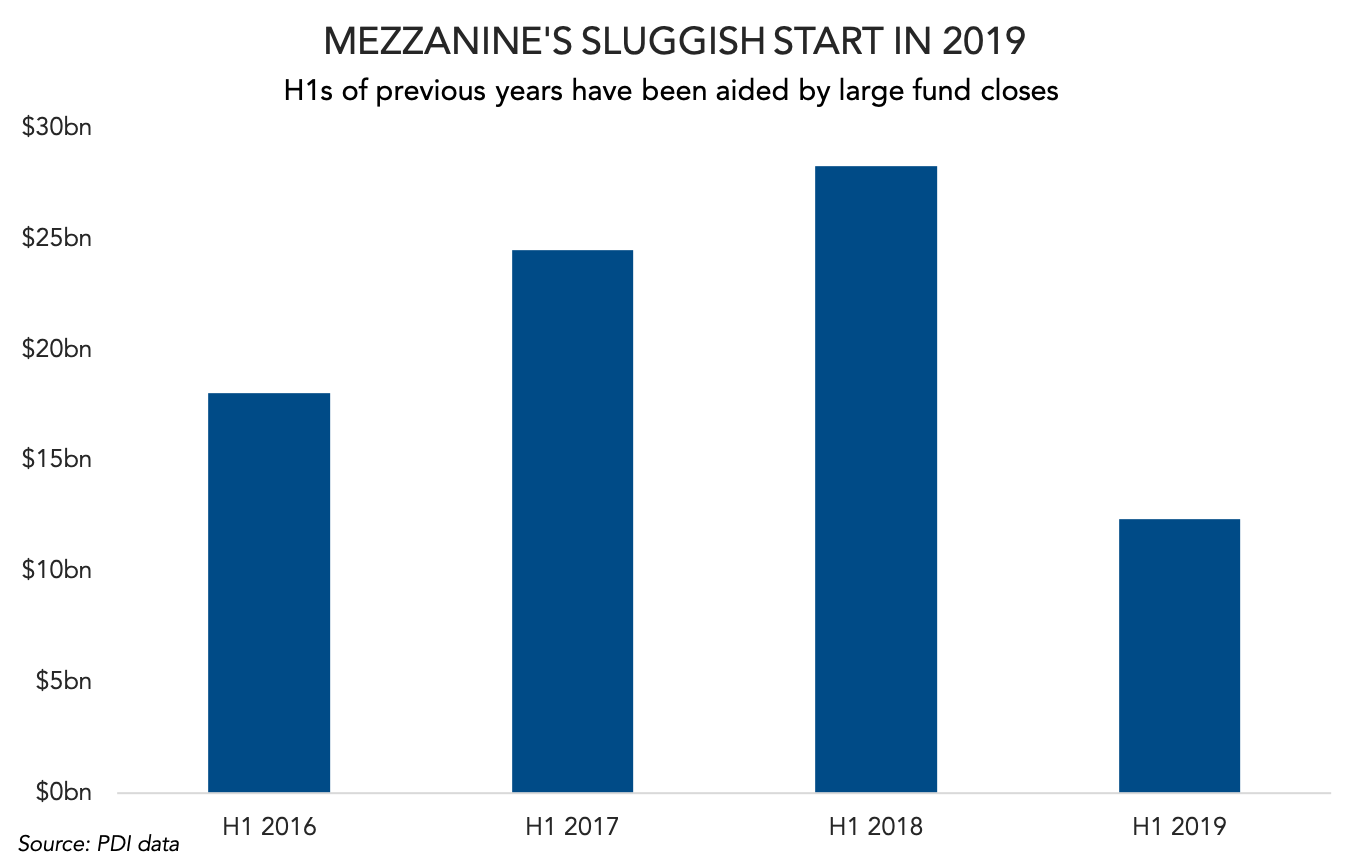
Mezzanine debt fundraising is off to a slow start this year, according to PDI data, once again showing the strategy’s reliance on mega-funds to post impressive fundraising numbers.
In the first half of 2019, junior debt funds closed on $12.37 billion, whereas in the initial six months of 2018 such vehicles closed on $28.31 billion. In 2017, that number was $24.52 million.
The first-half total of 2018 received quite a boost after Goldman Sachs held a final close on a whopping $9.9 billion for its GS Mezzanine Partners VII. The first half of 2019 produced no such massive fund closes. There were several that hit $2.5 billion but no vehicles reached the stratospheric level of Goldman Sachs’ capital pool.
Before processing other data, let’s just appreciate this: on junior debt funds, closes of $2.5 billion have a hard time moving the needle.
Certainly, mezzanine has been commonplace longer than senior debt funds, so larger funds might be more common. But the shifting of senior debt-junior debt financing structures toward unitranche loans in recent years has hollowed out mid-market mezzanine fundraising numbers, putting even more reliance on the mega-funds to boost mezzanine debt capital raising figures.
The second half of 2016 – a timeframe in which mezzanine funds raised $41.08 billion – shows just how several gargantuan closes can boost a fundraising total. GSO Capital Partners and HPS Investment Partners closed junior debt vehicles on $6.5 billion and $6.6 billion, respectively, in the second half of 2016. Adding to that total was Blackstone’s third real estate debt fund’s $4.5 billion raise.
Now more than ever, most private debt capital is being concentrated in the hands of the few, and the mezzanine debt numbers show that. Call it private debt inequality.
Contact: Andrew Hedlund
andrew.h@peimedia.com



Latest news

With inflation running hot, rate hike expectations strengthen
A hotter-than-expected inflation reading has renewed expectations for near-term Federal Reserve tightening. The Consumer Price Index rose 0.6% month-over-month, pushing…

Open Tab
Leveraged loans keep running up a tab. Senior direct lending already knows what it owes.
