


Preqin Private Debt Intelligence – 6/6/2016

Private Debt Firms Maintain Lower Management Fees
Negotiating appropriately structured fund terms and conditions has long been a key issue for investors across all alternative asset classes. Until recently, the traditional “2 & 20” fee structure for private equity funds has been widely used, but in the past several years these arrangements have become less fixed. Instead, investors and fund managers have both sought changes to management and performance fees, as well as hurdle and catch-up rates in an attempt to come to an agreement that suits all parties.
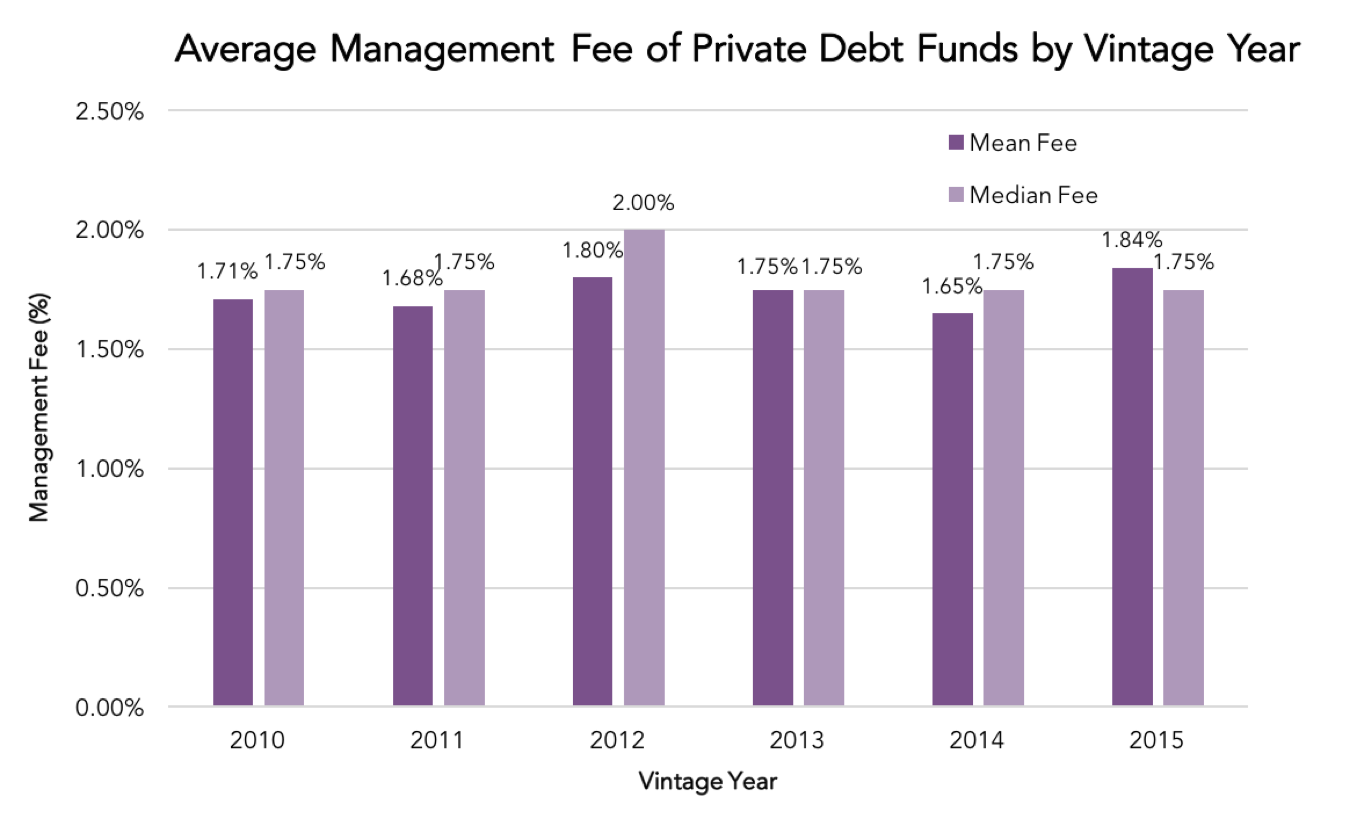
The growth of the private debt fund management industry since the Global Financial Crisis has further movement away from the ‘standard’ fixed terms, with debt funds charging markedly lower management fees than buyout funds raised in the same period. The median management fee for private debt funds has remained stable over the past three vintage years, at 1.75%. This compares to a median management fee for buyout funds of 2.00%, a figure which has remained the same for the past ten vintage years. The mean private debt management fee has fluctuated, falling from 1.80% for 2012 vintage funds to 1.65% for 2014 vintage funds, less than the mean fee charged by buyout funds of the same vintage years.
However, among 2015 vintage funds, the mean management fee private debt funds rose to 1.84%, while for buyout funds it fell to 1.74%. This is the first time that the mean fee for private debt funds has exceeded that of buyouts, perhaps reflecting the contrasting points in the life cycles of the two industries. 2015 saw several flagship private debt funds close in a position to dictate favourable terms, while the buyout industry is coming under increasing scrutiny from investors and regulators on the issue of fees.
Overall, fee structures remain a complicated and contested area of the LP-GP relationship. The right level of fees depend on the manager and the investor, but innovation and flexibility on this issue may prove an important tool in a fund’s ability to market itself to investors.
Contact: William Clarke
william.clarke@preqin.com




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
