



Seve Ballesteros won four majors in the 1980s despite being, by his own admission, one of the wildest drivers of the golf ball on tour. He found the trees, bunkers, and deep rough more often than his competitors. But what made him great was his recovery shots and improvisation when he found trouble. That turned his bad drives into pars on the scorecard.
Private credit can work the same way. A default isn’t the end of the story, it’s often the start of negotiation. As discussed in Safety, Not Size, core middle market lenders engage the sponsor early, protect collateral, and use covenant trips to compel negotiations before problems compound.
As a result, a default in the middle market rarely resembles a default in the public markets. When a broadly syndicated loan or high yield bond runs into trouble, given the large number of constituents (often with competing priorities), the path often runs through a courtroom. A lengthy Chapter 11 process can generate significant restructuring fees that eat into recoveries. In the core middle market, the lender is often a single manager or a small, tightly knit club of relationship lenders. Restructurings nearly always happen around a conference table, not in front of a judge.
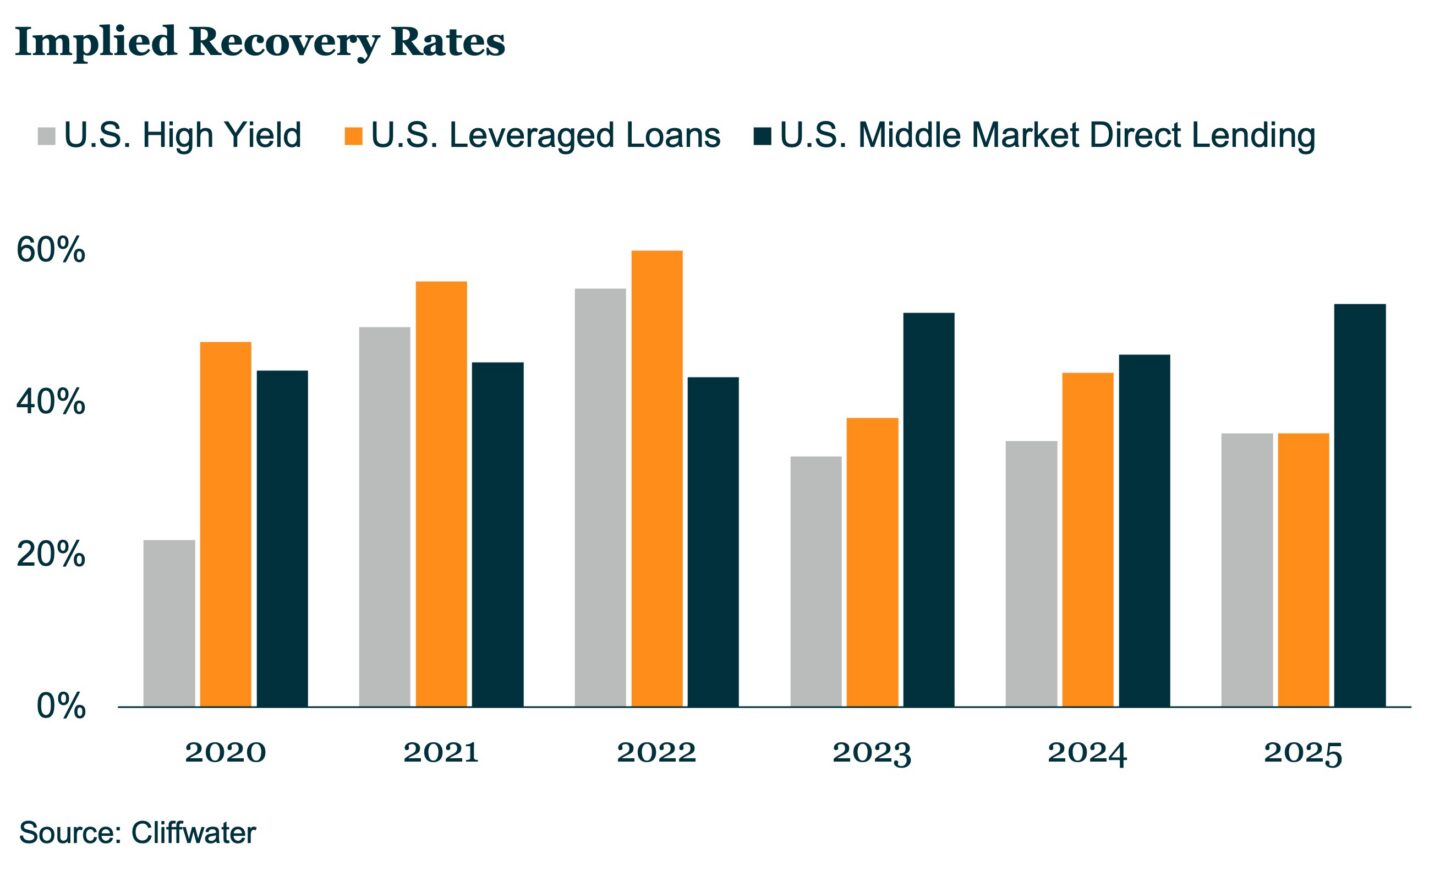
Private credit can also have a long runway before a loan ever reaches a true default. Amend-and-extend agreements, PIK toggles, and equity cures all give companies lifelines to address underlying issues. The “shadow rate” – as discussed last week – can be a useful signal, in part because some measures include covenant defaults. A covenant trip can give managers the ability to get “back to the table” to negotiate a better outcome. Examples include pushing for a sponsor cash injection, tightening credit agreement provisions/baskets, increasing reporting/transparency, requiring sale of non-core assets for debt repayment or pressing for a change in management and/or governance while there’s still time to right the ship.
As one workout specialist put it, “You have to remain proactive as a lender. Make the case to other capital providers, owners, and management for the direction you want to go. Otherwise, you’ll be reacting to the strategy and direction of others, which can result in sub-optimal outcomes.”
Most middle market workouts don’t end up as free-fall Chapter 11s. Consensual workouts, built on relationships between sponsors and lenders who expect to work together again, generally result in the best outcomes and recoveries.
Ballesteros didn’t win majors by keeping the ball in the fairway. He won them because his short game turned trouble into pars, and pars into trophies. Private credit managers who’ve been through prior cycles operate the same way. The default isn’t the story. It’s all about what they do when they find themselves in trouble.


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
