



Download PitchBook’s Report click here.
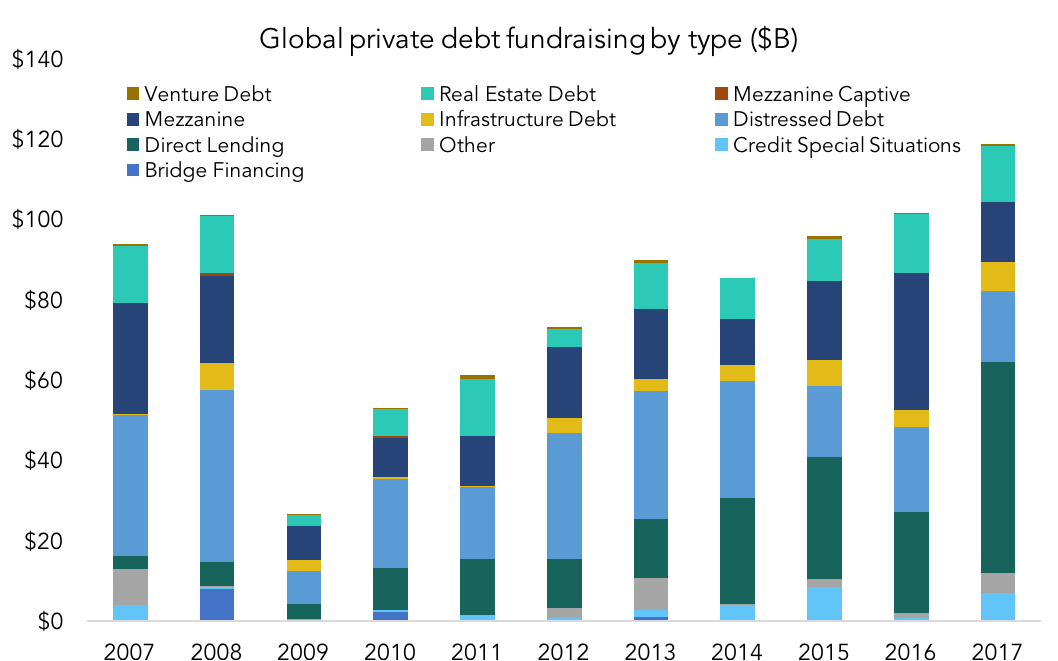
Following the financial crisis, raising funds for private debt vehicles has mirrored—and in some cases exceeded—the exponential growth of the larger private capital market. 2017 was a record year in capital commitments, which totaled more than $118 billion globally. Of course, the private debt market can be sliced into a number of sub-strategies, each with their own contribution to the capital structure. The explosion in private debt fundraising (graphed above) has usually been credited to quantitative easing, which pushed public market yields down to razor-thin margins. Institutional investors looking to revive “normal” credit returns, turned to private debt in droves. There’s some truth to that, but the bigger engine was new financial regulations put in place by Dodd-Frank and Basel III, which in their own ways both stymied the lending capabilities of big banks, leaving a crater-sized hole in the credit market.
The other major influence on the private debt market was the private equity industry itself. What goes on in the PE market has a large impact on what goes on in the private debt market. The two go hand-in-hand in many ways, and momentum in one asset class helps fuel momentum in the other. As the supply of private debt has ballooned to record levels, the result has been, what else?, increased competition on terms and pricing. Cov-lite loans are at unprecedented levels, and add-backs have increased in usage to make issuers seem more creditworthy. On the other side of the coin, lenders and LPs are in a riskier position today—fewer protections and lower rates could ultimately mean lower returns for general debt funds, which could mean even more opportunity for niche players like distressed debt or turnaround funds.
Contact: Alex Lykken
alex.lykken@pitchbook.com




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
