



PE Fundraisers Going Bigger in 2016 Portends Emerging Spread in Success?
At $225 million, the median US private equity fund size is higher thus far in 2016 than in the several years prior. This is despite relatively healthy fundraising activity in general, with 57 closed vehicles in the third quarter alone; one may suppose that diminished activity could artificially inflate median fund sizes, as the most successful firms are still able to close while others miss out, but that is not the case this year. The increase in size is attributable to a confluence of factors, ranging from timing to limited partners’ preference for fewer managers but stable allocation sizes, which necessarily leads to larger checks to fewer funds.
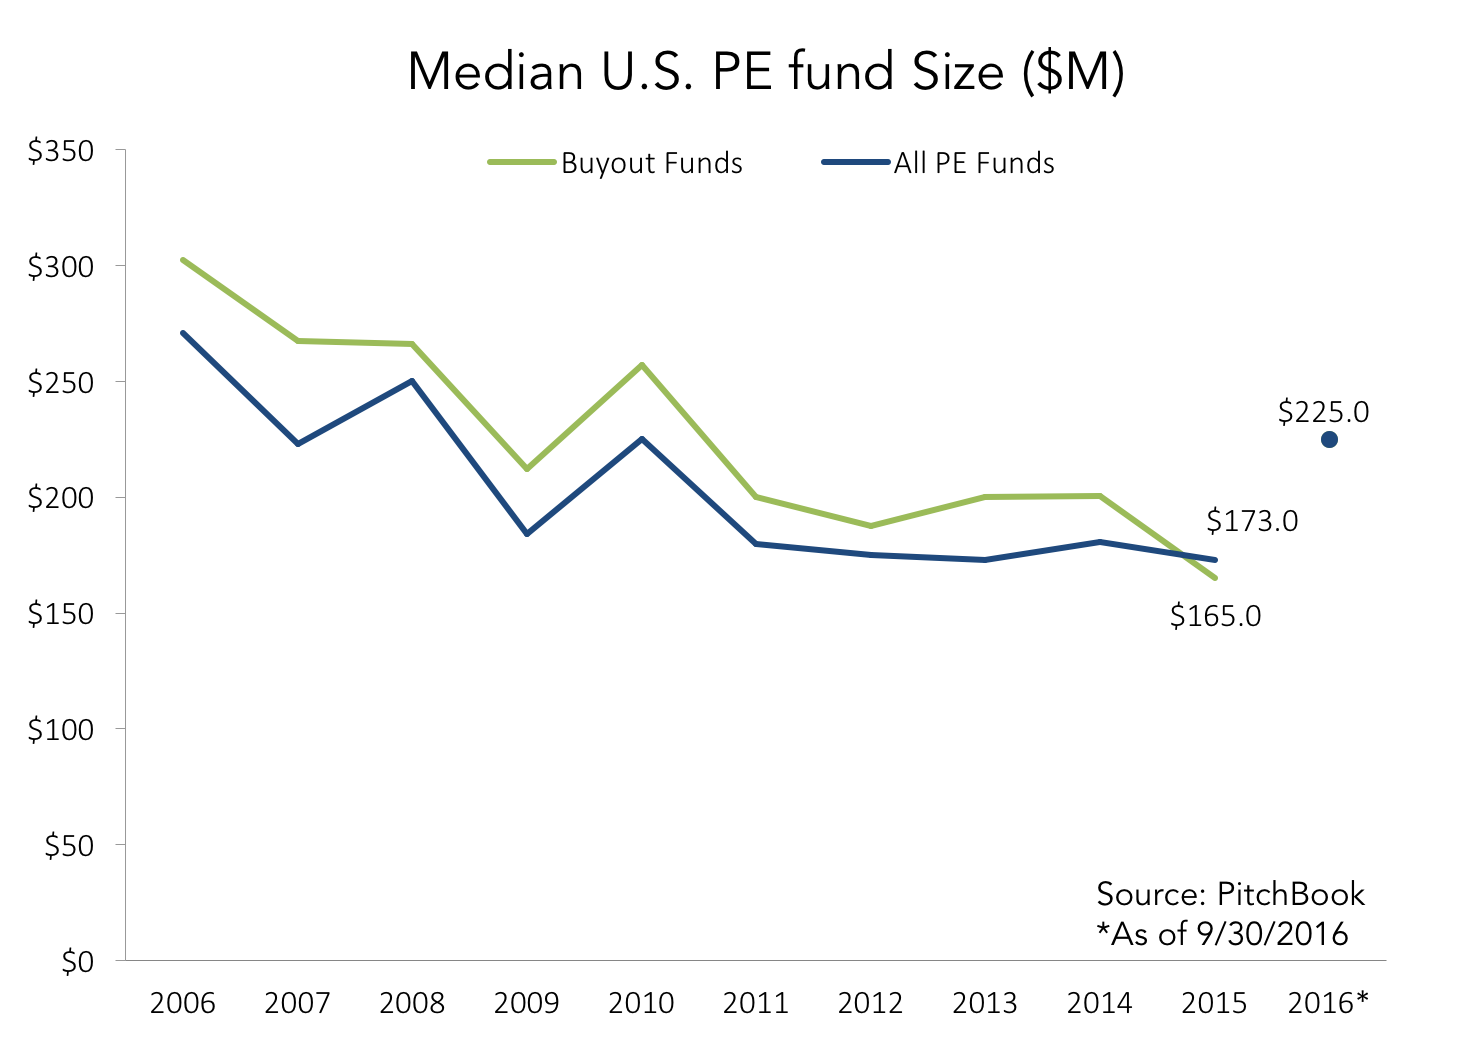
Expectations of a relatively high-priced environment persisting for some time as well as longer fund lifecycles may also be playing into fundraisers’ goals. It should be noted that funds of a necessity simply took longer to close this year, with the average buyout fund taking over 15 months to wrap up. That isn’t untowardly long on a historical basis, and still reflects the basic reality of closing on larger funds. LP enthusiasm isn’t necessarily surging, but rather remaining steady given the relative allure of PE as an alternative asset class. Given that, it’s interesting to speculate upon where the equilibrium will emerge between LP appetite for PE exposure and the level of competition for funds in the marketplace. Between 2000 and 2014, the number of active PE firms globally rose from close to 1,500 to around 3,500, an increase of 143%. It’s been a couple of years, but it’s highly unlikely all those funds are both still around and also raking in a median of $225 million for their buyout vehicles. A spread in fundraising success is likely emerging or set to unfold over the next few years, accordingly. Some firms will likely refine investment theses in response or even pivot into more niche sector-based approaches, but regardless, unless LP allocations tick up or perhaps shift from hedge funds and other such increasingly unpopular strategies to PE, a bifurcation in fundraising success is likely to emerge, however masked by the outsized success enjoyed by a stable of managers.
☞ Read PitchBook’s 3Q 2016 Breakdown Report here.
Contact: Garrett Black
garrett.black@pitchbook.com


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
