


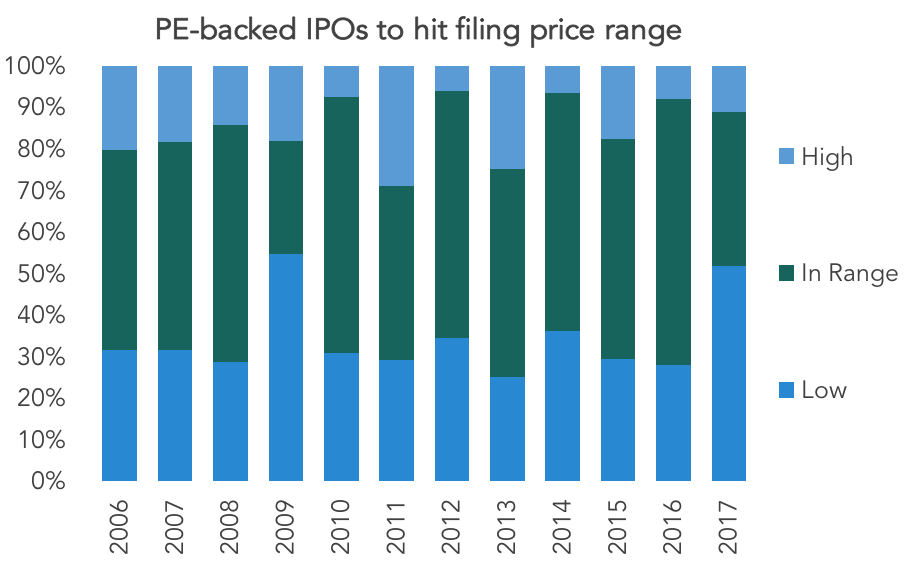
It’s no secret that PE sellers have preferred outright sales over IPOs recently. There are big advantages to staying private, and many of the best-performing assets on sale since 2016 have been bought outright by financial or corporate buyers. Why test the temperamental public markets when acquisitions can bring in consistently high multiples? The PE-backed companies that have gone public this year almost confirm that perception. Through 3Q, almost half of 2017 IPO listings priced below their initial price ranges, a ratio not seen since 2009.
Times are different today, and PE’s IPO woes are multi-faceted. Questions around profitability and leverage ratios were cited several times this year, as were questions around the current retail model, energy prices, tax changes, healthcare regulations and the sustainability of the recent tech surge. Among the PE-backed IPOs to underwhelm this year, several were tied directly or indirectly to the struggling retail sector or the still-questionable energy market. Perhaps the biggest difference between today’s numbers and 2009’s is the housing sector; among the better IPOs this year, three have direct ties to an improving housing market, including Floor & Décor (up 88% since listing), Jeld-Wen (which considered an outright sale around $3 billion, while its stock has surged 71% to a $4.1 billion market cap), and Invitation Homes, Blackstone’s massive holding in the rental-home market, which is up 17% since going public in January.
Contact: Alex Lykken
alex.lykken@pitchbook.com




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
