



What is in store for US private equity in 2017?
After a high-water mark for US private equity activity in 2015, last year experienced a significant slowing in not only the number of closed deals but also total deal value, the latter ameliorated by a bevy of blockbuster transactions. This was driven in part by the progression of a typical investment cycle, wherein after a steady ramp-up in dealmaking the market attracts more and more firms looking to cut deals and consequently becomes pricier. External conditions like the relative attraction of the PE asset class amid the global financial landscape didn’t assuage matters for PE fund managers, who enjoyed plenty of interest from limited partners and responded in kind, amassing significant hoards of dry powder that kept upward pressure on valuations in auctions. A coinciding M&A boom also led to higher valuations at the upper end, as players in more traditional industries sought acquisitive routes to growth. Accordingly, total deal value remained robust but PE dealmakers slowed their pace throughout 2016, responding to valuations, lack of worthwhile targets, overheated competition or shaky growth prospects in certain arenas.
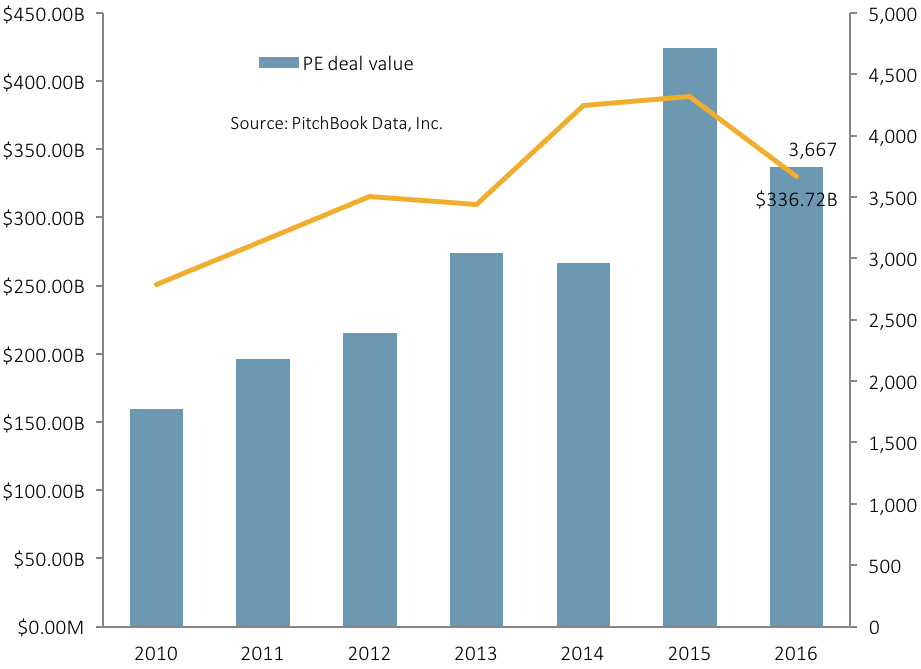
So where does this leave the US PE industry, on the cusp of 2017? Investors will at the very least just maintain their current investing pace, as public market comparables seem to show no sign of slowing anytime soon and many sectors in the US economy are still sound, particularly relative to the global scene. The case of fundraising is curiouser, to borrow a phrase, as there are significantly countervailing factors: the overhang of capital raised and investors’ demand for exposure to PE. Everything else equal, it’s likeliest that fundraising will continue in an even more targeted fashion, resulting in a slight decrease in vehicles closed but significant success in hitting targets. Last but not least, PE-backed exits should continue at a decent clip, but as the M&A boom cycles downward and IPO prospects remain cloudy, their frequency will gradually decline, or in a moderately more optimistic scenario, flatline.
Contact: Garrett Black
garrett.black@pitchbook.com


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…