



Download PitchBook’s Report click here.
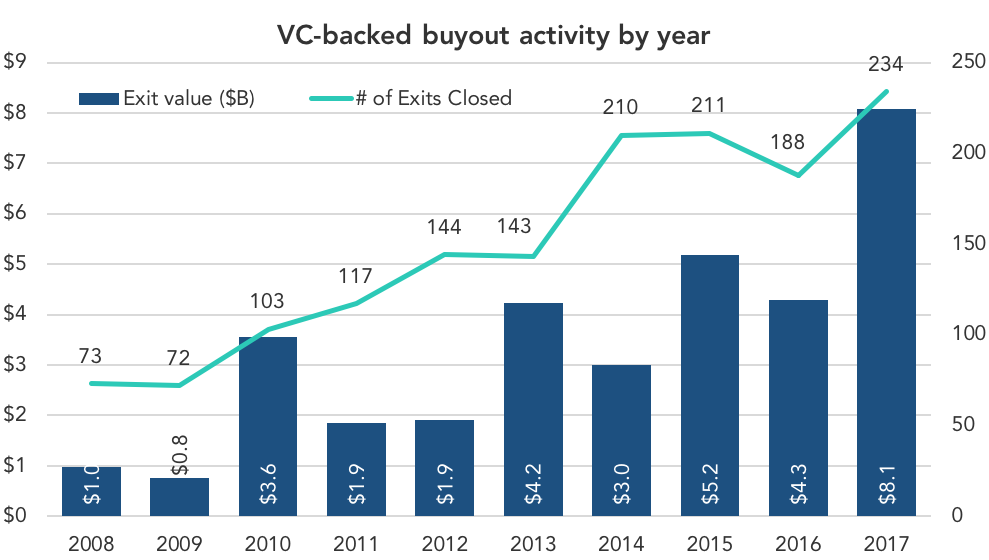
It would have been hard to predict ten years ago, but private equity is becoming a prominent buyer of venture-backed startups. According to our 2017 Annual VC Liquidity Report, buyouts now account for almost a fifth (18.5%) of all VC-backed exits, up from about 14% in 2016 and ~10% a decade ago. It’s a sudden shift in strategy for private equity, which seldom ventured into startup acquisitions in years past. It never really made sense to buy startups anyway—everything from risk assumptions to capital requirements are night and day different between the two models. At least they used to be.
Things are slightly different today. The two popular explanations remain valid—startups are wary of going public in a volatile market (and don’t need to IPO anyway with gobs of private capital floating around). On the buyside, PE dry powder levels are just as strong, and challenging deal flow is forcing PEGs to get creative with their targets. But both of those points have been true since at least 2012, when VC-to-PE acquisitions were much less common. The more important difference today goes back to the startups themselves, which are selling products and services in big enough numbers to justify PE interest. Late-stage startups, especially so-called “unicorns” valued at $1 billion or higher, are generating real revenues that can’t be dismissed by institutional investors, including PEGs. Moreover, many of today’s startups getting acquired by PE are actually getting acquired by PE portfolio companies, which changes the discussion a bit. Add-ons are akin to strategic acquisitions in this case, and as we discussed a few weeks ago, add-ons are popular in the software space as sponsors continue strengthening their platform investments with additional revenue lines. That said, we wouldn’t be surprised to see startups become more popular platform investments in the years ahead, especially late-stage companies that have been private for almost a decade. As PE gains experience in software, the idea of startup buyouts (to coin a phrase) may not sound as crazy as it does today.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
