



Download Related Report click here.
Private equity has enjoyed a historically long business cycle alongside historically low interest rates. With high multiples and lots of dry powder floating around, today’s market bears some resemblance to 2005-2007, but not too much. The latest crop of funds (2016 vintages and later) will face new headwinds and tailwinds that are beginning to come into focus. We recently partnered with Akerman, a middle-market-focused law firm, to spotlight the sub-$1B fund market and where those headwinds and tailwinds will come from.
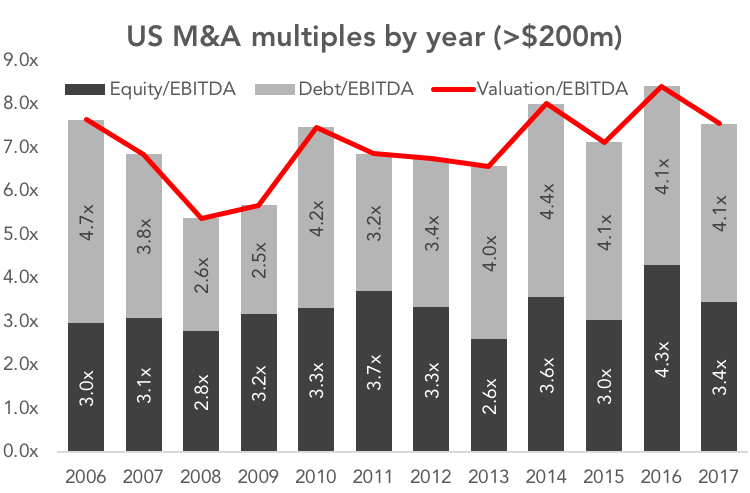
The obvious tailwind, of course, is the reduction of the corporate tax rate from 35% to 21%. Private equity benefits from this at the fund and portfolio company levels, both of which are structured as corporations and qualify for reduced tax bills going forward. Moreover, the tax overhaul may also impact limited partners as it relates to section 1202 of the Internal Revenue Code—with some foresight, LPs (and possibly GPs as well) might be spared the 23.8% federal capital gains tax on qualified portfolio company dispositions. There are potential headwinds, as well. The Fed is expected to raise interest rates several times over the next two years, but PE returns shouldn’t be impacted as heavily as some fear, as long as the increases are done at a modest, structured pace. At the lower end of the middle-market, M&A multiples below $200M have moderated between 7x-8x, visibly smaller than $1B+ multiples. As rates rise, there’s a reasonable chance that multiples will come down in tandem. That bodes well for PE, which is struggling as an asset class to outperform the public market. Quite a bit is expected from private equity—maybe too much. The public market, however, will likely come down to earth as cheap money starts to evaporate, providing an opportunity for PE to regain its luster. PE doesn’t hit as many grand slams as it used to, but perhaps it doesn’t need to—relative returns might be a more appropriate measuring stick than absolute returns, at least for this latest batch of funds.
Contact: Alex Lykken
alex.lykken@pitchbook.com


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…