



Finishing strong
View PitchBook’s 2017 Global PE & VC Fund Benchmarking Report: Part II Here
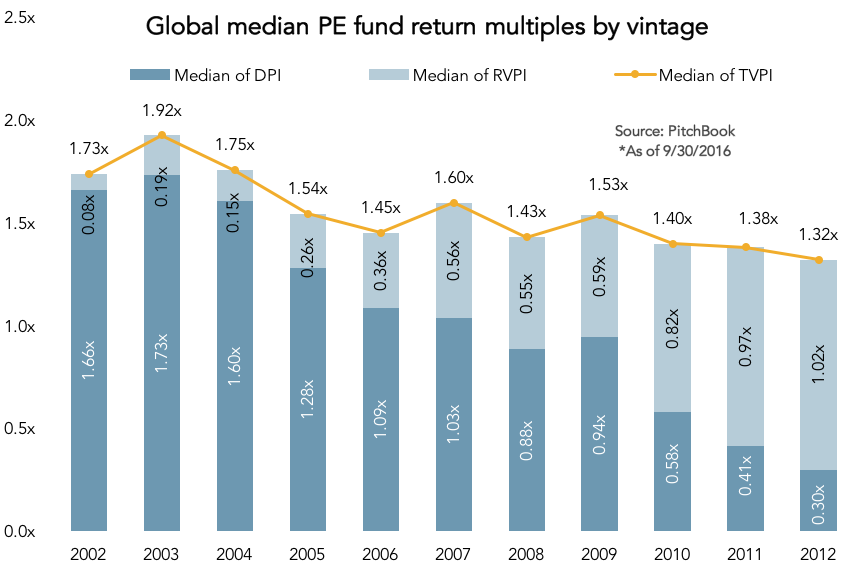
In the prior installment of the Pulse of Private Equity, we discussed how the cyclicality of the PE industry was coming to bear, as the momentum and speed with which more recent fund vintages could return money to their investors slowed. The counterpart to the distributed-to-paid-in (DPI) multiples illustrating that trend – residual value-to-paid-in (RVPI) multiples – exemplify the corresponding phenomenon of just how much value is still left to be realized. Vintages from 2007 to 2009 still have median RVPI multiples exceeding at least 0.50x, even though it has been just shy of a decade since the eldest of those funds closed. Granted, the delaying factor of the recession contributed in no small part – which limited and general partners all consider – but what’s more important now is to assess the paths toward eventual liquidity for investors in those funds. The exit market had a slow start to 2017, slower even than a lag in data collection could potentially explain. Moreover, even if it is still a sellers’ market judging by current transaction multiples and anecdotal evidence, the sheer prolongation of that cycle and its typical progression suggest sales are likelier than not to slow. But time decay is on no one’s side. Hence, a determined focus on exiting what assets are best positioned will characterize the PE-backed exit market as it proceeds into its later innings. Against that backdrop, the realization of gains still locked in currently held portfolio companies looks at best to occur at a more languid pace going forward. Significant realization can still be achievable, as seen by the fact even vintages with liquidity trends most impacted by the financial crisis – 2005 and 2006 – were able to eke out further conversion of RVPI to DPI figures.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
