



View PitchBook’s 2017 Global PE Deal Multiples Report: Part II Here
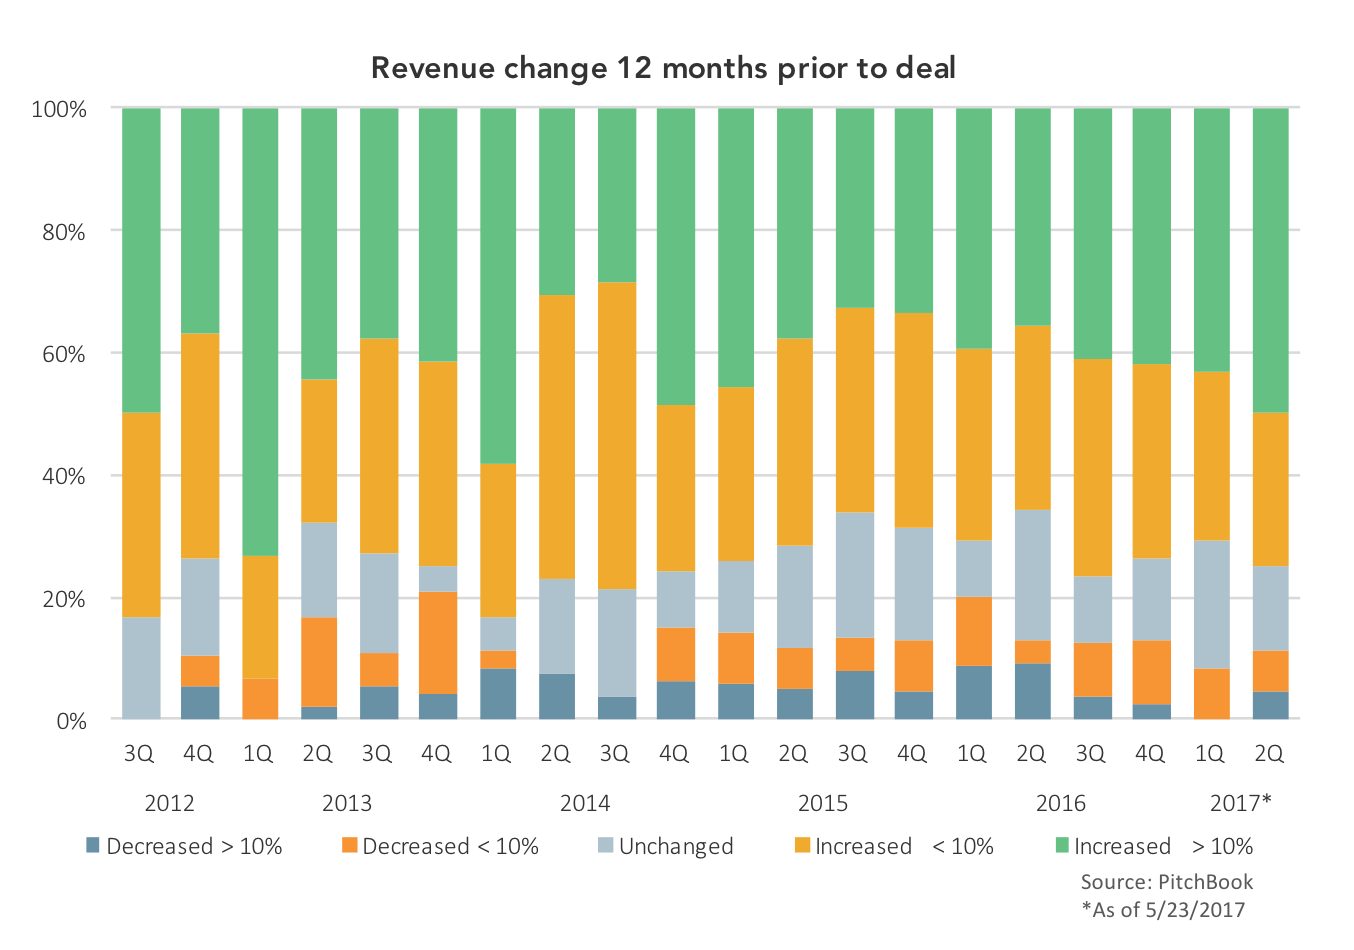
Multiple datasets can help convey certain aspects of why the current private equity environment may represent a new normal in terms of dealmaking, yet one of the more telling is one that depicts the type of the company that buyers are targeting. Since the third quarter of 2015, there has been a distinct if very gradual increase in the proportion of companies with revenue growth exceeding 10%. Although the proportions of companies that are experiencing decreased growth have fluctuated considerably, the increased incidence of firms focusing on growing companies speaks to the difficulties inherent in deal sourcing nowadays. The level of competition is at such a pitch, particularly in light of hefty dry powder stores, PE buyers are considering relatively healthier companies (at least in terms of revenue growth) than they did in much of the past. Granted, historical trends indicate that current proportions aren’t unprecedented, but they testify to the challenges facing PE investors. The larger question now is whether this inexorable trend has shifted the operating environment into a new equilibrium for PE firms, where they will continue to consider companies that typically wouldn’t fall under their purview. Perspective is necessary for accuracy given this unique situation. The buyout industry has rarely enjoyed such largesse from investors, and never has encountered such competition from peers, given the growth in the popularity of typical PE strategies. Moreover, one could argue the unique monetary policy approaches adopted by most developed nations – wherein most PE firms operate – has distorted asset valuations to a noticeable degree. Accordingly, it is not so much that PE strategies themselves have changed as they were forced to adapt given the shift in key underlying drivers. There is a new normal for PE buyout firms now, but that normal could very well shift given slackening leverage regulations or a washout among fledgling fund managers.



Latest news

PIK Your Next Adventure
Every amended PIK loan hits the same crossroad. Not everyone ends up at the same destination.

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.
Private Credit Defaults 101: Beyond the Noise
Like any good school year, this series went by fast. But unlike the end of the year, we’re not out for the summer.