



View PitchBook’s 2017 PE & VC Exits Here
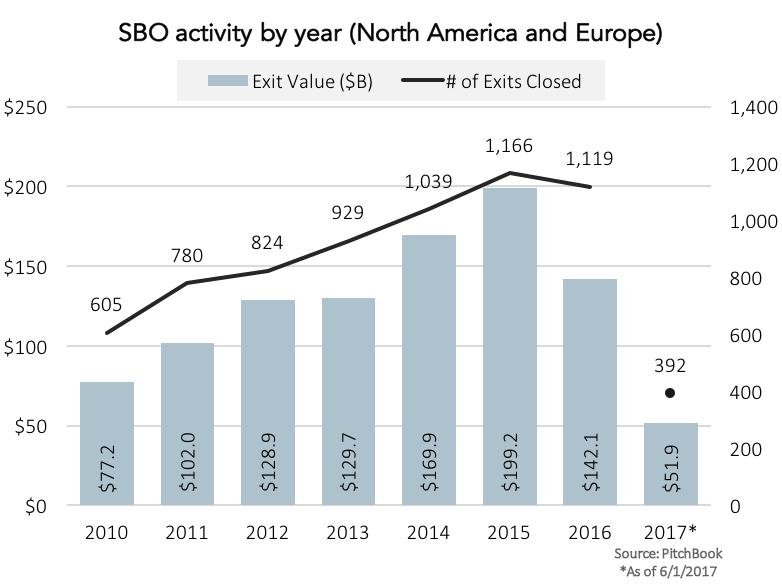
Secondary buyouts have been artificially propped up by the inflated volume of crisis-era investments for the past few years. “Like a snake digesting an elephant’s worth of assets,” as Bain & Co. phrased it, PE deals made from 2005 to 2008 slowly made their exits, topping out in 2015 in terms of secondary buyout activity. Decelerating slightly in 2016, pass-the-parcel deals have fallen off a cliff so far this year. As we outlined in our recent PE & VC Exits Report, SBOs would drop 30% in volume at their current pace and likely level out somewhat over the next few years.
So begins another cycle in the PE industry. Dry powder levels are well above even 2008 totals, and each PE-backed company that comes to market is said to spark a feeding frenzy among buy-side sponsors. As the last of the elephants pass through, we should get a clearer picture of the post-crisis SBO market and the changes PE firms are said to have made. SBOs are now justified via “complementary skillsets” between buyers and sellers—whether in terms of size, geography, strategy, or sector expertise, among others. It’s a perfectly valid trend, but it remains largely anecdotal. With so much money sloshing around chasing too few targets, buyers and sellers are focused on more than just each other’s skillsets, and likely will be for some time to come.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
