



View PitchBook’s 2017 Global PE & VC Fund Benchmarking Report: Part II Here
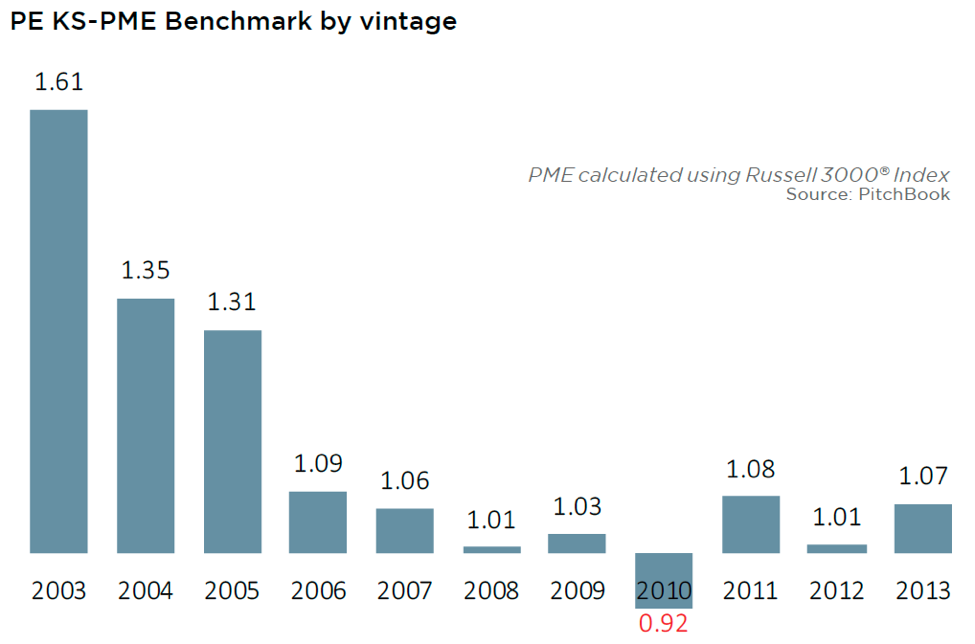
To conclude our analysis of select topics grounded in fund performance data, we must discuss a topic that has become increasingly prevalent as of late: the maturation of the buyout industry and what that entails for its future. Originally a very opaque and non-populous market, information flows and number of participants in the buyout industry have increased its efficiency marginally, although significant market inefficiencies remain. Even if we consider the effects of increased competition on their own terms, they explain in large part the trend observed in charting Kaplan-Schoar PME benchmarks by PE fund vintage; as a reminder, PE KS-PME values exceeding 1.0 indicate outperformance relative to comparable public market indices. It’s clear that the eldest vintages in our dataset distinctly outperformed public markets, benefiting from the considerable time elapsed since their liquidation periods closed (in all likelihood) as well as fewer participants. However, since then we’ve observed a much thinner margin of outperformance. Part of that is due to macro conditions, as stock markets have been on a historic run, while it’s at least possible if not probable that some vintages are still realizing value at a lagging rate due to the recession. Regardless, the continued thinness in spread speaks to how much more difficult it has been for PE fund managers to achieve outsized outcomes given how much competition for private assets there has been. The universe of private enterprises hasn’t necessarily shrunk in absolute terms; it’s just that the penetration by PE funds has grown to such an extent most transactions are now competitive auctions, as opposed to proprietary deals. Consequent elevated prices and heftier equity contributions have dampened returns in aggregate, although outliers still exist. These occurrences are par for the course when it comes to a maturing market. What matters for current PE participants is whether this is truly the new normal or whether, depending on the state of the business cycle, increases in outperformance are possible in the future once more. Given the mammoth hoard of dry powder amassed by PE managers, there are interesting dynamics in play that foreshadow future developments, which we explore in our next Pulse of Private Equity.


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…