



PE Interest in US Lower Middle Market Slumps Temporarily
After trending upward for over a year, private equity dealmaking in the US lower middle market (defined as transactions sized between $25 million and $100 million) fell sharply between 1Q and 2Q 2016. Granted, there were fluctuations in the upward trend, but 1Q recorded not only the highest spike in PE activity in the US LMM since the start of 2012, but also a clear peak in overall deal value. Yet 2Q fell by both counts, even though the overriding trends of adding on smaller companies and PE players’ continued interest still hold.
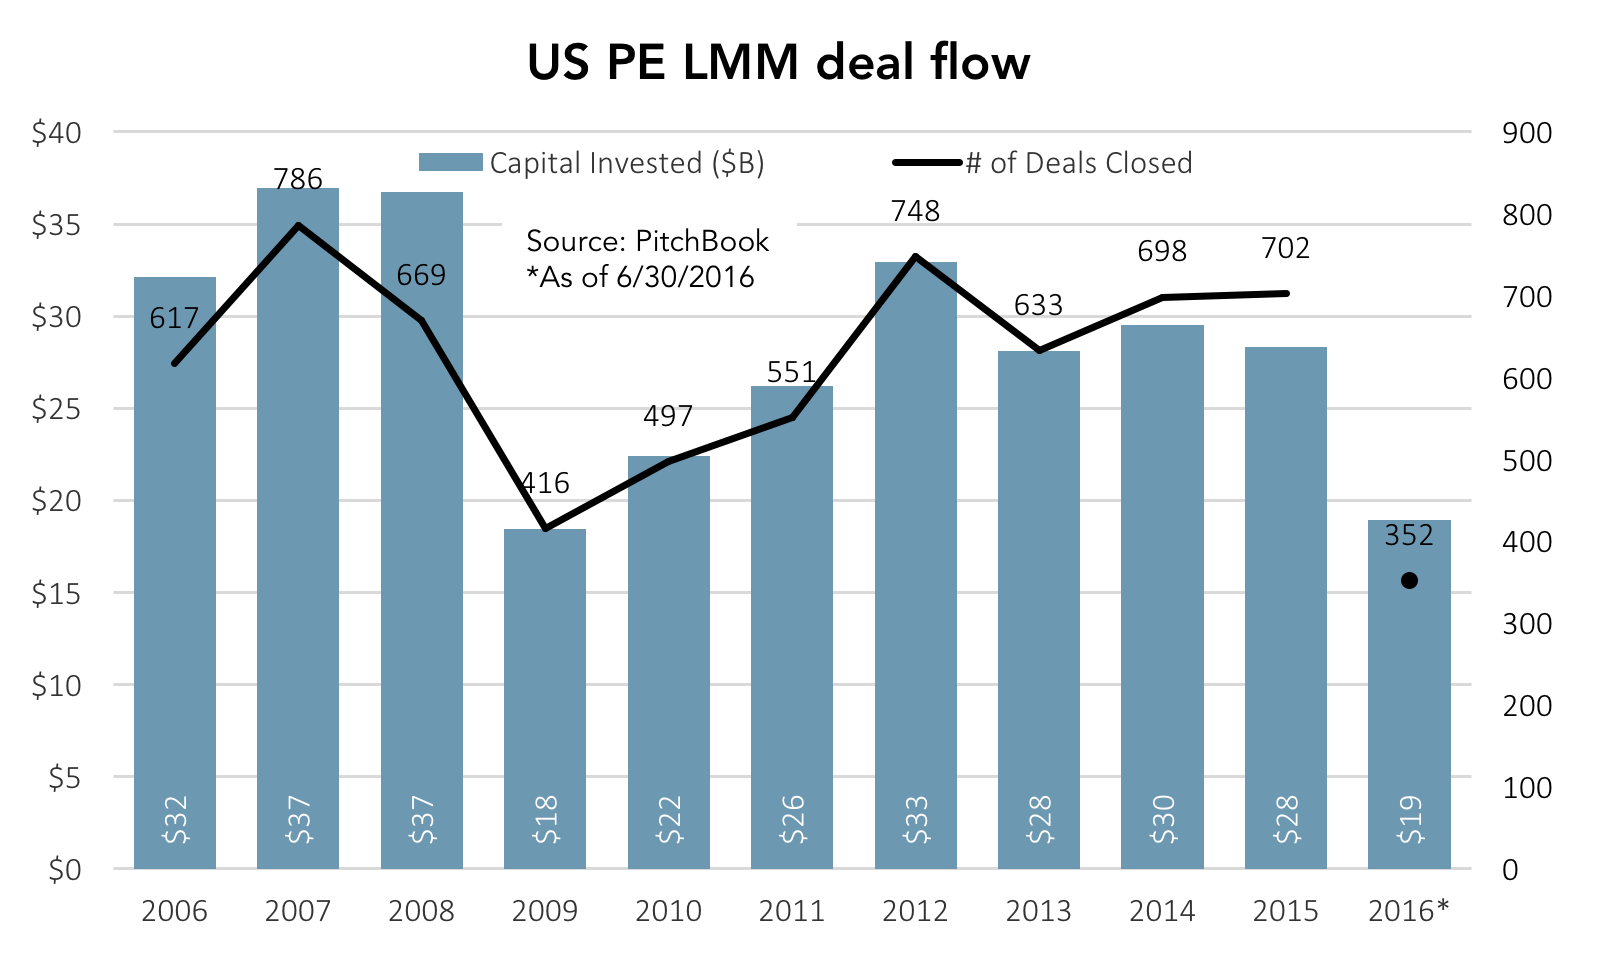
Beyond the fluctuation that can be observed from quarter to quarter—and the consequent caution that must be observed when analyzing such numbers—the decline must be put in a broader context. First, on a yearly basis, US lower-middle-market companies are still on pace to enjoy roughly the same level of interest from PE investors as they did in the past two years, the heyday of the current buyout cycle. Second, given the size of the companies involved as well as the various political and macroeconomic risks that investors are trying to take into account, the steady rise of PE activity in the LMM was capped off with a peak in the first quarter of 2016 as dealmakers sought to close whatever worthwhile opportunities were in play as quickly as possible. On a quarterly basis, the supply of quality companies in market affects the rate of closed deal activity on a slight delay, suggesting that the current decline is also due to most of the best targets having already been bought. Finally, as the pipeline refills in certain sectors such as healthcare and technology, PE interest in the LMM could well revive to a healthier level, since many firms still need to put capital to work and industry trends in those aforementioned industries are still encouraging general M&A.
View the corresponding report here.



Latest news

PIK Your Next Adventure
Every amended PIK loan hits the same crossroad. Not everyone ends up at the same destination.

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.
Private Credit Defaults 101: Beyond the Noise
Like any good school year, this series went by fast. But unlike the end of the year, we’re not out for the summer.