



Mega-deals Down, Mega-exits up
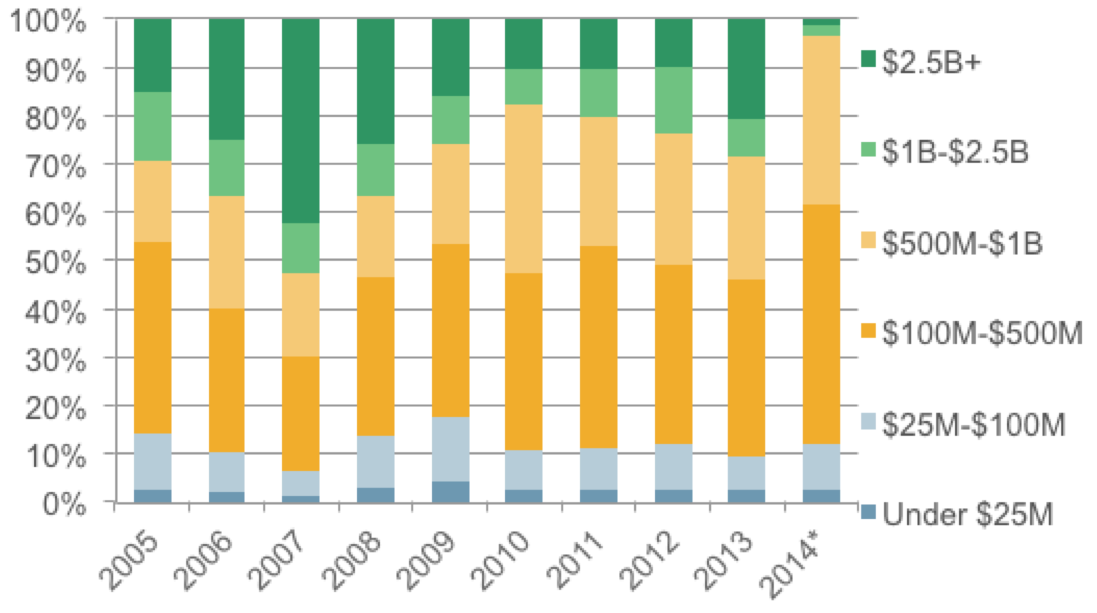
Few investors are as opportunistic as PE firms, which need to invest at entry points low enough (and exit high enough) to justify their investment models. With valuations where they are right now, it’s not surprising to see mega-deals ($2.5 billion+) at a multi-year low in YTD 2014 and mega-exits ($2.5 billion+) at a multi-year high. For those large exits, part of that trend is simply due to timing, with many pre-crisis investments being offloaded while the public markets are open and strategics are willing to buy those companies. What’s interesting is that many of those pre-crisis deals are turning out OK for investors, and some of them are turning significant profits. Deals done in 2006 at high valuations are, in some cases, returning big profits back to LPs.
Deal flow by size
Exit activity by size
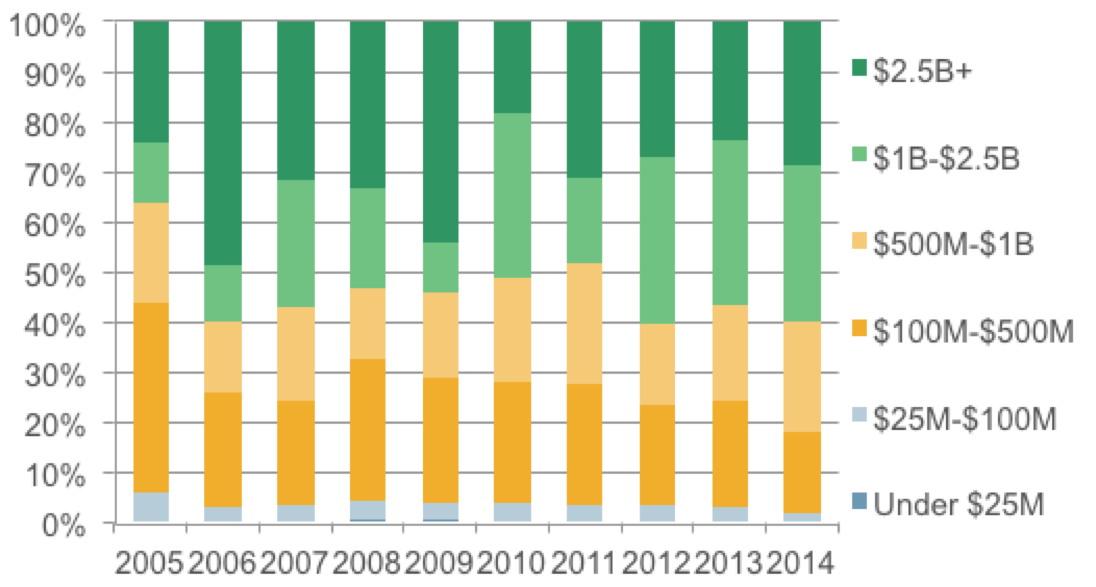
But it seems that PE firms learned some lessons from the last time valuations were this high, and aren’t making as many investments today as they were back in 2005-07. Instead, they’re making more modest bets, including add-ons, middle-market buyouts and growth deals, all of which carry lighter price tags than the typical mega-buyout. Once the stock markets cool off, we’ll probably see PE firms head back into the public markets, but for now, it seems they really did change their approach following the crisis.
Contact: Adley Bowden
adley.bowden@pitchbook.com



Latest news

Open Tab
Leveraged loans keep running up a tab. Senior direct lending already knows what it owes.


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.