


The strategy’s popularity with investors peaked in 2024, as did the amount of capital being deployed.
In 2024, amid a volatile economic and political environment, investors demonstrated a flight to safety by flocking to senior debt strategies. It was a year that saw senior debt’s share of all global private credit fundraising rise to 63 percent. It proved to be a one-off, however – last year, that figure fell to 42 percent, much more in line with the historic norm, as investors prioritised strategic diversification.
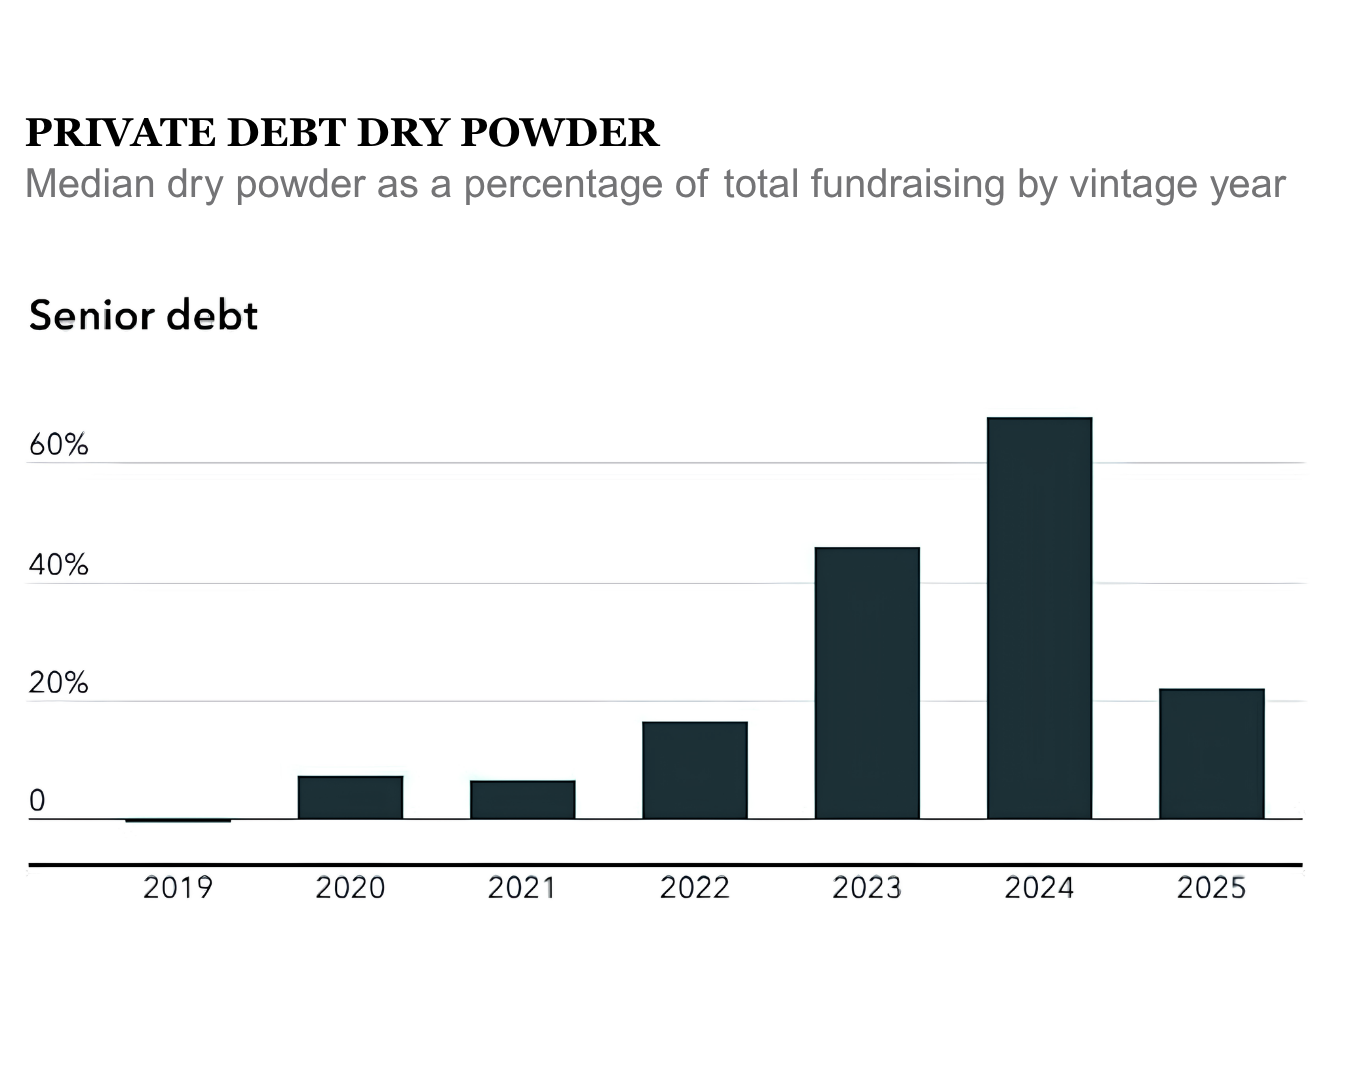
Interestingly, as committed investor dollars peaked, so too did deployment of this capital. As can be seen from our latest fund performance quarterly report charts, senior debt dry powder tumbled to just over 20 percent (the percentage of committed capital not yet called) – a drastic reduction from more than 60 percent the previous year.
This rapid deployment will raise concerns over whether some fund managers have, in the rush to deploy capital, maintained sufficiently rigorous underwriting processes. On the positive side, it has at least demonstrated private credit’s ability to put capital to work – even during periods where M&A activity has been thin on the ground.
Meanwhile, distressed debt and subordinated/mezzanine debt showed similar trends to each other in dry powder terms – with distressed debt spare capital remaining just below 60 percent over the last few years and subordinated/mezzanine debt slightly above that figure for the last two years.


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
