



After a slow third quarter, 2015 has only seen 32 private equity-sponsored initial public offerings (IPO), raising a combined $7 billion. The IPO window for PE sponsors in the fourth quarter of 2015 may be narrowing, although it’s unclear how much concern that should really cause for now. After all, even though an initially disappointing debut can prompt fear of subdued performance for some time, PE firms can defer much liquidity until they can execute secondary offerings in a more welcoming climate.
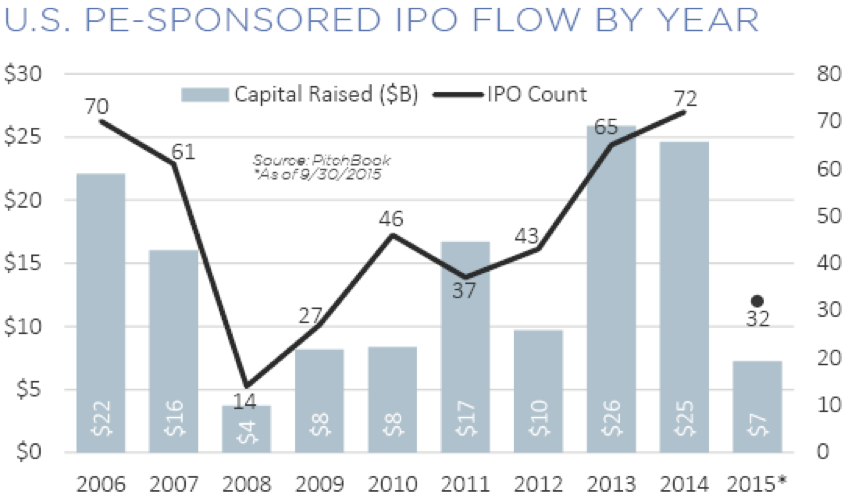 But for now, fear of volatility and underwhelming debuts from Blackstone’s Performance Food Group (NYSE: PFGC) and KKR’s First Data (NYSE: FDC) seem to have spooked Cerberus Capital Management-backed Albertson’s, for one, although a slide in results posted by Walmart (NYSE: WMT) didn’t help matters. With many pointing to the sheer mass of debt on the balance sheets of First Data as one of the causes for investor wariness—given a potential uptick in interest rates at some, undetermined future date—fellow PE portfolio companies that are similarly leveraged, however healthy their overall financials, may well steer clear of going public in what remains of 2015. But as the First Data offering again signifies, timing isn’t restricted to just the amenability of public markets when it comes to some of these PE portfolio companies. First Data was one of the last holdovers of the buyout boom era, with KKR likely biting the bullet and taking it public regardless of volatility in order to achieve some liquidity. Other prominent PE-backed companies in the pipeline, such as Univision, may eventually follow suit, if debt payments become an issue. It’s either that or court a strategic buyer, but some of the companies are fairly hefty prospects for corporate acquirers to absorb. In the end, it comes down to how much PE investors will weigh various timing factors against each other. The potential increase in leverage costs, how much longer volatility will persist, and whether going public now will substantially weigh performance for some time will all be carefully considered by the PE firms whose companies are currently in the pipeline.
Contact: Garrett Black
garrett.black@pitchbook.com



Latest news

PIK Your Next Adventure
Every amended PIK loan hits the same crossroad. Not everyone ends up at the same destination.

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.
Private Credit Defaults 101: Beyond the Noise
Like any good school year, this series went by fast. But unlike the end of the year, we’re not out for the summer.