



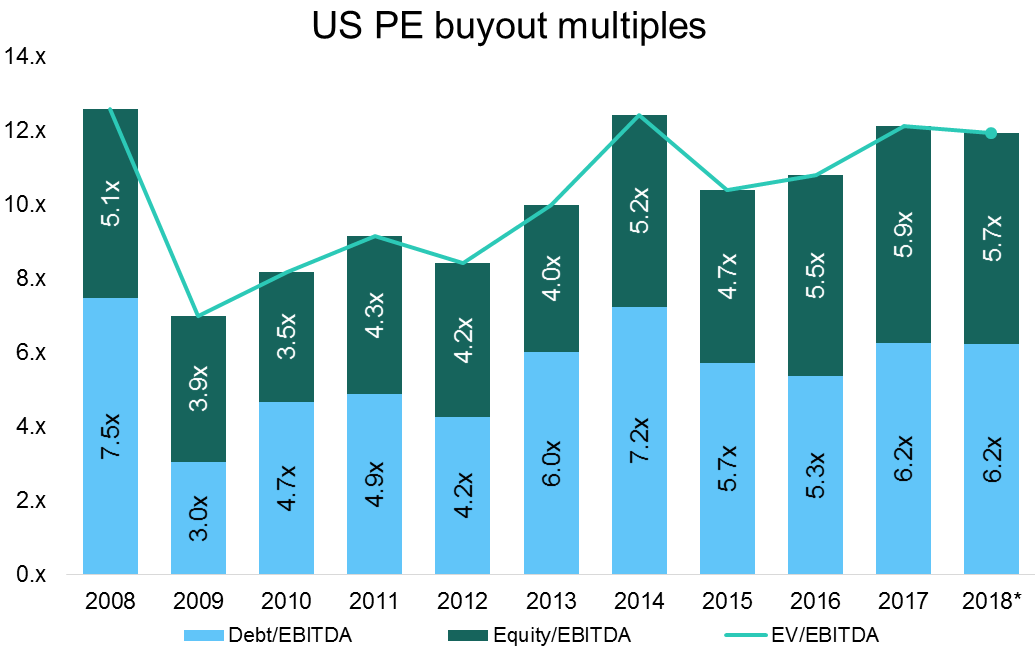
Apollo’s Leon Black made a few waves this week, warning that “the credit markets, unlike the equity markets, have gone to bubble status.” He said the amount of covenant-less debt available today is higher than it was in the run-up to the financial crisis. Bloomberg’s Lisa Abramowicz was right to point out that this isn’t Leon Black’s first warning on the topic—he said the US was in the middle of a credit bubble in February 2017, as well, not long before Apollo closed the largest buyout fund in history. His latest alarm coincides with a recent Moody’s report showing that 92% of post-2009 buyouts done by the 16 largest PE firms were being financed by B2-rated debt or lower. Moreover, almost a fifth of those issues are now B3 negative or lower, in distressed debt territory. Moody’s compares these latest PE-backed ratings with companies without a PE sponsor, where only 40% of debt issues are B2 or lower.
The bubble-calling industry has become a permanent feature in the post-crisis economy. This isn’t to discount Black’s worries, which are echoed by many. But one of the biggest lessons learned from the crisis, at least from PE’s perspective, was the resiliency of creditors and elasticity of cov-lite loans. Both played significant roles in allowing PE’s collective portfolio to survive the credit crisis relatively intact. Of course, the price of debt is going to be different this time around, and interest rate hikes are coming into focus across the PE industry. It’s worth noting that private equity played little to no role at all in the financial crisis—PE lacks systemic importance in the broader economy because PE-backed companies aren’t part of a broader domino chain. They usually aren’t even linked to each other in the same private equity fund. To put Moody’s report into context, of the 308 companies it rated, 20 wound up in default. That poses a problem for the PE sponsors themselves but not for the economy as a whole. “The ratings of PE-backed companies do not bode well for them when the economy turns,” emphasis in italics.
Contact: Alex Lykken
alex.lykken@pitchbook.com




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
