



Last month we wrote about the decline in PE holding times, with the median dropping below five years for the first time in almost a decade. These figures represent portfolio companies and not fund durations (longer-dated funds are relatively new and don’t move the needle yet). PEGs are simply turning companies around a bit faster in recent years, at least in aggregate.
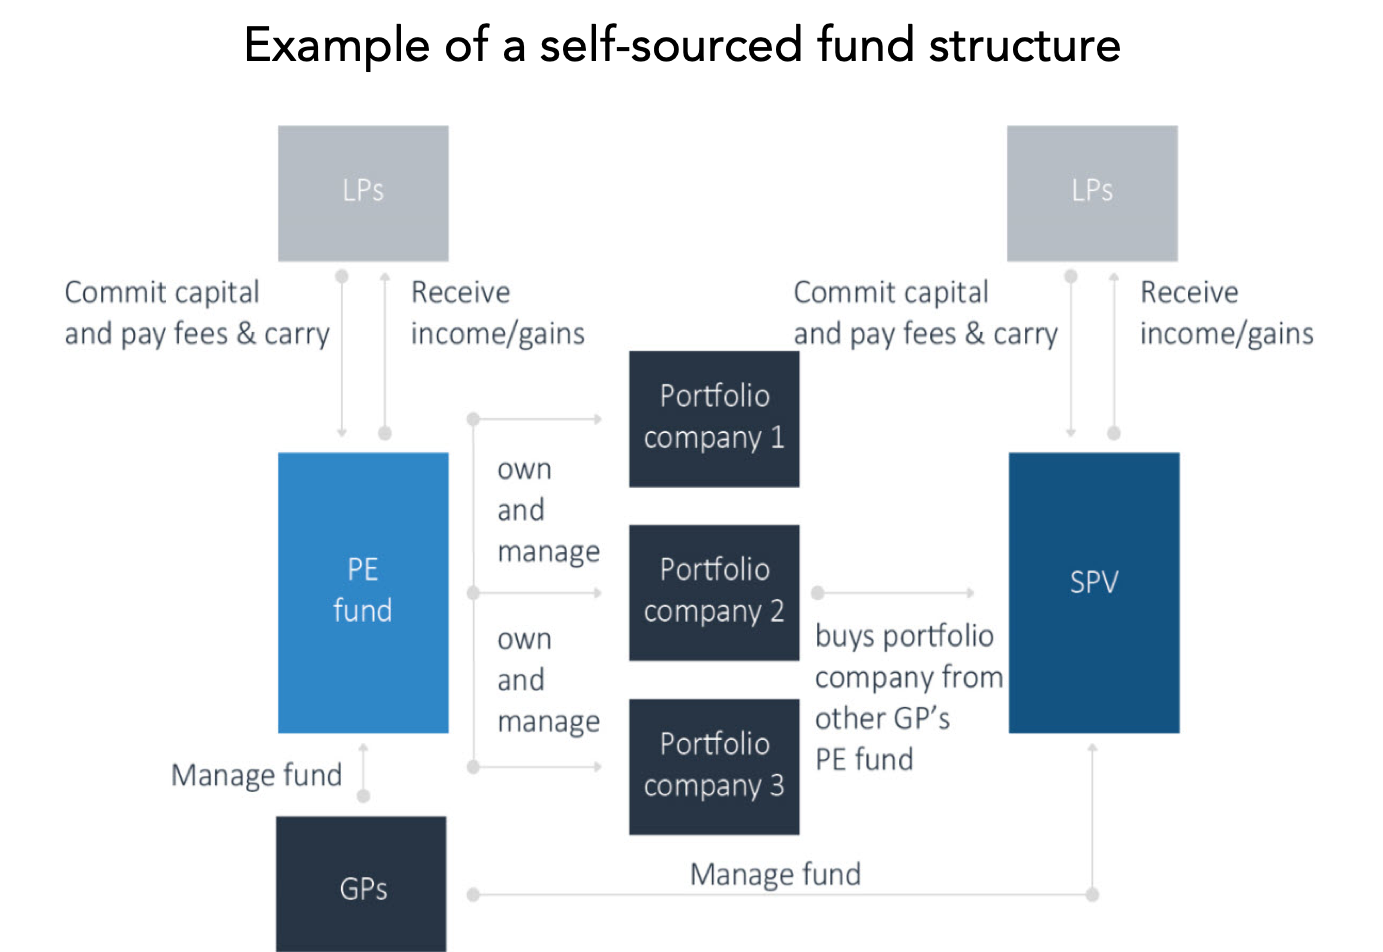
An upcoming PitchBook analyst note will take a closer look at holding times and why they might go up from here. Unrelated to any macro factors, there are signs that PEGs are finding more ways to hold onto their winners longer while keeping investors happy. GP-led secondaries are one option, and while those have been happening for a few years, the market has matured. Greenhill data shows that 30% of all 2018/19 secondaries activity was GP-led, up from 8% in 2012. Popular among the PEGs that use them, GP-led secondaries involve new SPV funds made to hold a handful of portfolio companies for another 3-5 years. Sometimes the firm’s value-creation blueprint needs more time to play out, but the upside might be worth it. LPs can opt out if they’d like.
Thanks to TA Associates, there’s a new option to consider. Last year they rolled out TA Select Opportunities Fund, which sounds like a standard, vague-sounding fund. It’s not standard at all, though, and is pretty interesting. It essentially buys minority stakes in TA portfolio companies that are being sold off to other investors. It’s a new-enough strategy that we’re not sure what it’s called yet. PEI calls it a “double-down” fund, but a craps term might be better than a blackjack one. “Hot roll” fund seems more accurate…but also sounds weird. Whatever we end up calling it, the idea might have staying power, depending on what LPs think of it. Breakout returns aren’t likely, but they could give LPs a differentiated risk/return profile while helping the GP grow AUM. We suspect the market will be watching the fund closely, not only how it performs but also how TA navigates the potential conflicts of interest.


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…