



Download PitchBook’s Report here.
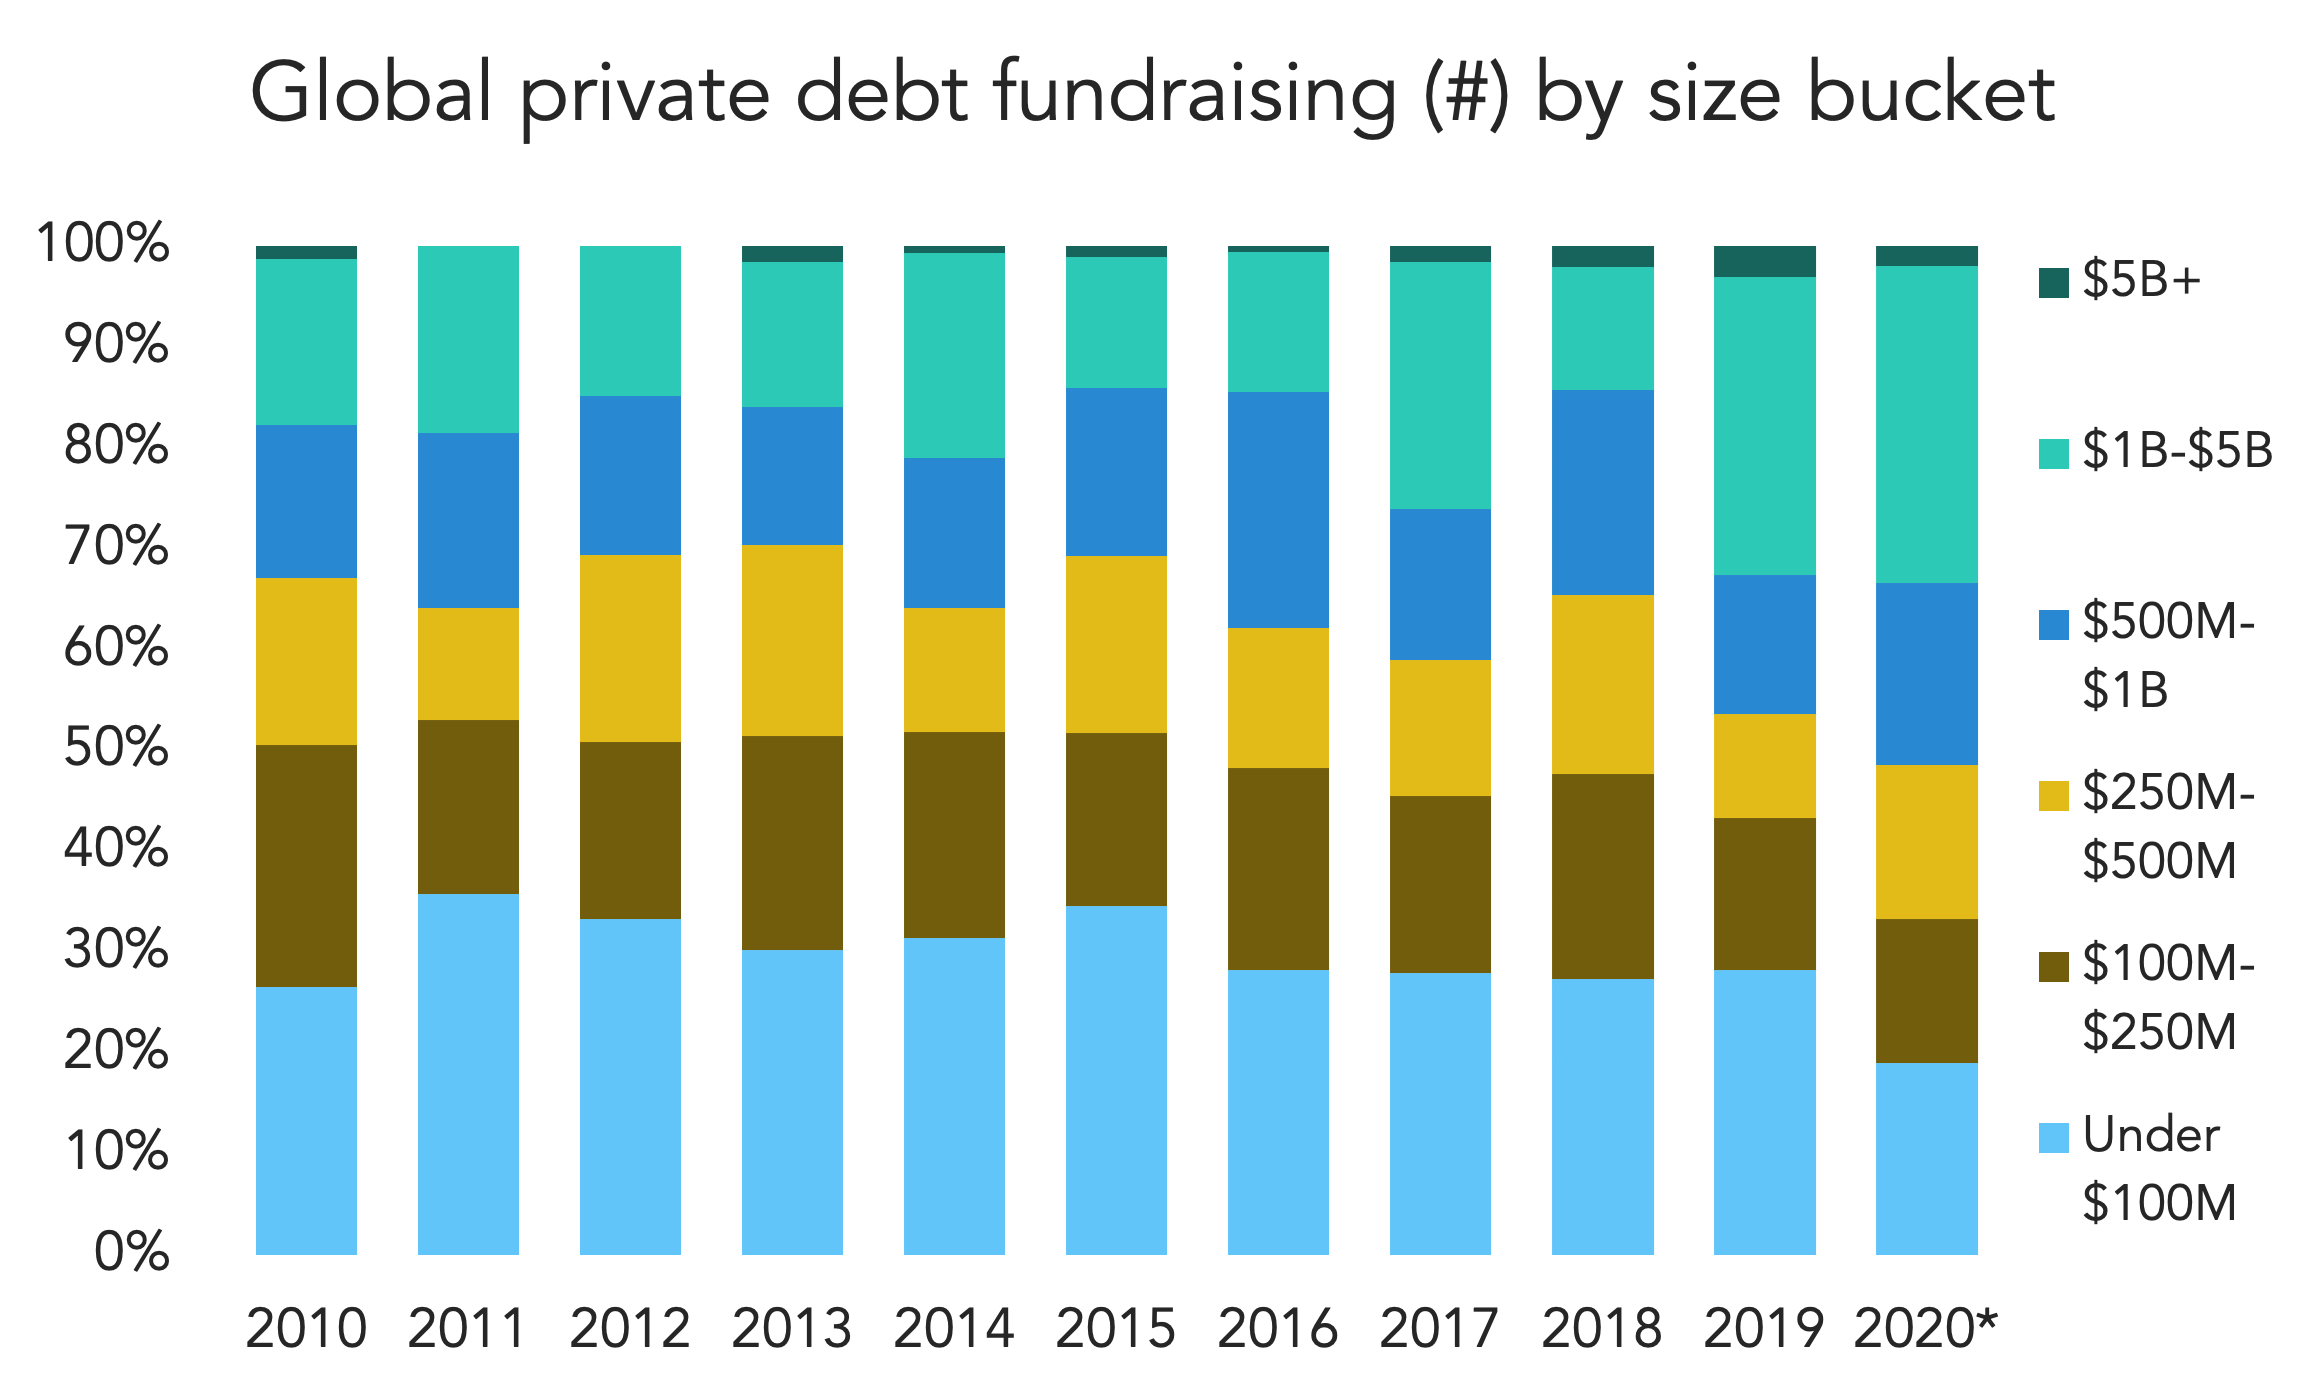
Private debt funds have grown much larger over the past two years, according to PitchBook’s latest Global Private Debt Report. Larger funds naturally dominate the charts – by dollars raised, $1B+ funds accounted for almost 80% of all debt fundraising in 2020. It was the same story in 2019 (82%), but the past two years departed from historical norms. Between 2010 and 2016, $1B+ funds accounted for around 60% to 70% of all private debt raises in any given year.
When we look at the number of $1B+ funds raised, that ratio jumped in a big way over the past two years. In both 2019 and 2020, a third (33%) of all private debt fund closings were above the billion-dollar mark, compared to 14% in 2018. In that two-year span, 89 new $1B+ funds came to market, including 7 worth north of $5B. In fact, for the first time since 2008, fundraises over $1B outnumbered any other size bucket. Predictably, that’s led to higher median fund sizes. Last year’s median was $519 million, which more than doubled the 2018 median of $231 million.
This is all a natural progression for a private asset class, and private debt is following the same trajectory as private equity did over the past two decades. Unless the past two years are outliers or coincidences, though, it looks like private debt is getting top-heavy much more quickly than the PE market did.


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…