



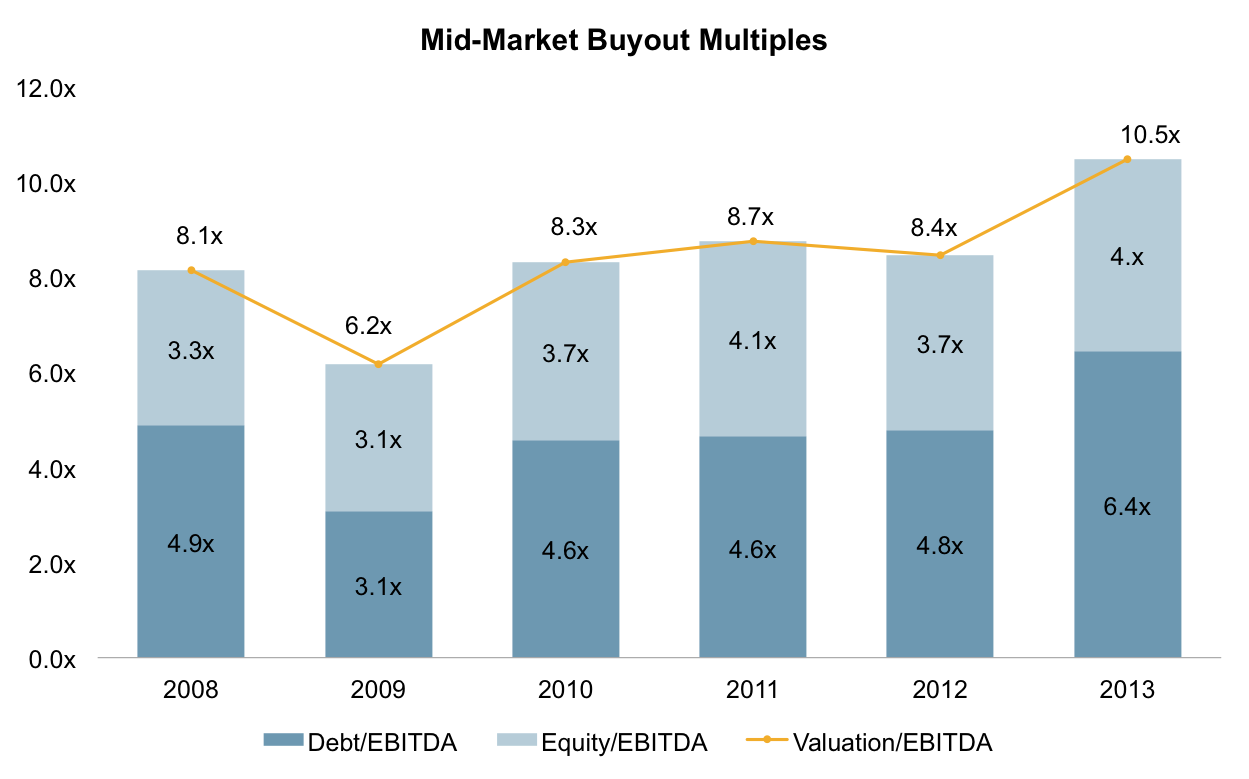
At ACG Intergrowth last week I spent a fair amount of time talking with private equity deal guys (and one gal…another topic) about the current market. The clearest trend everyone could agree on, and one that nobody was particularly excited about, was the increase in company valuation multiples over the last 12 to 18 months. Consensus put EBITDA multiples going up by about 1x to 2x over this short time frame, a fact verified by the data we have captured on middle-market transactions (see above).
There are several drivers behind this multiple expansion and it is hard to quantify the impact of each individual one but the three big ones are as follows. There continues to be increased deal competition for quality deals from both strategic and PE firms, both of which have plenty of money. Leverage for transactions is accessible and cheap as it has almost ever been, allowing firms to put in the same amount of equity as before and just finance the multiple increases. Quality companies have now shown three years of positive financials, essentially wiping the Great Recessions from their books.
The strategies and tactics being used by PE firms as result ranged from nothing different to only buying companies that could be expected to still hit return goals but in a lower multiple environment. Whatever the response is, it is clear that valuation multiple increases are going to continue providing a headache for the foreseeable future.



Latest news

PIK Your Next Adventure
Every amended PIK loan hits the same crossroad. Not everyone ends up at the same destination.

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.
Private Credit Defaults 101: Beyond the Noise
Like any good school year, this series went by fast. But unlike the end of the year, we’re not out for the summer.