



How much longer will the M&A boom sustain PE exits?
The M&A boom has been very kind to private equity sellers. Last year saw PE sellers close over 1,200 sales to strategic buyers, with total value just eclipsing $360 billion. That leaves the past three years at a total of $963 billion in total value exited via that ramp, a truly staggering sum, particularly given the levels before. Corporate buyers have plenty of reason to go hunting amid PE portfolios for targets, given the challenges of appeasing shareholders amid what often is anemic economic growth. On the PE seller side, the current levels of PE-backed company inventory and valuations are still more than compelling enough to push firms to the exit.
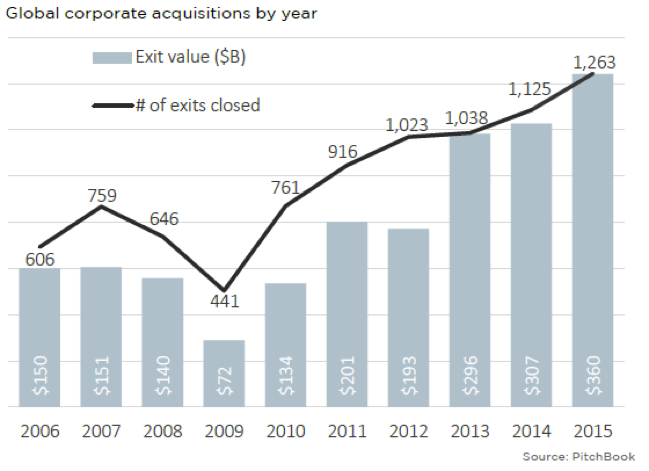
What’s interesting to ponder is how much longer corporates will continue to snap up PE-backed holdings. Even though competitors still seek acquisitive growth, driving companies to shift strategies away from traditional organic means of growing, it seems more than likely that a few factors may emerge to drive down the rate of PE exits, although the extent to which they will do so is set to be mild. First, particularly given the onset of unease and declines in global financial markets, buyers are likely to scrutinize potential acquisitions more closely in general, which could prolong deal timelines. The best companies, accordingly, may well be snatched up even more quickly, but by and large, issues of quality will predominate in acquirers’ minds. Second, PE firms have likely already brought their best portfolio companies to market, capitalizing on high market valuations while they could. Hence, prospective strategic acquirers may simply not buy as much, as they may not find as many targets to their liking. Lastly, again especially in today’s climate of heightened volatility, buyers may well take some time to digest and integrate their acquired targets, in a natural pause after such highly active selling. Granted, barring a major macroeconomic shock, these factors—among others—should not contribute to a significant slide in corporate purchases of PE holdings, but last year, perhaps even through 2014, is likely to remain a high point.


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…