



High Tide for Secondary Buyouts
It isn’t too surprising that secondary buyouts (SBOs) hit a record by count in 2014. Globally, 707 SBOs closed last year valued at a combined $116.9 billion. The latter statistic is well off the record of $159.2 billion set in 2007, but by count 2014 saw 27% more sponsor-to-sponsor deals than 2007 and the height of the buyout boom.
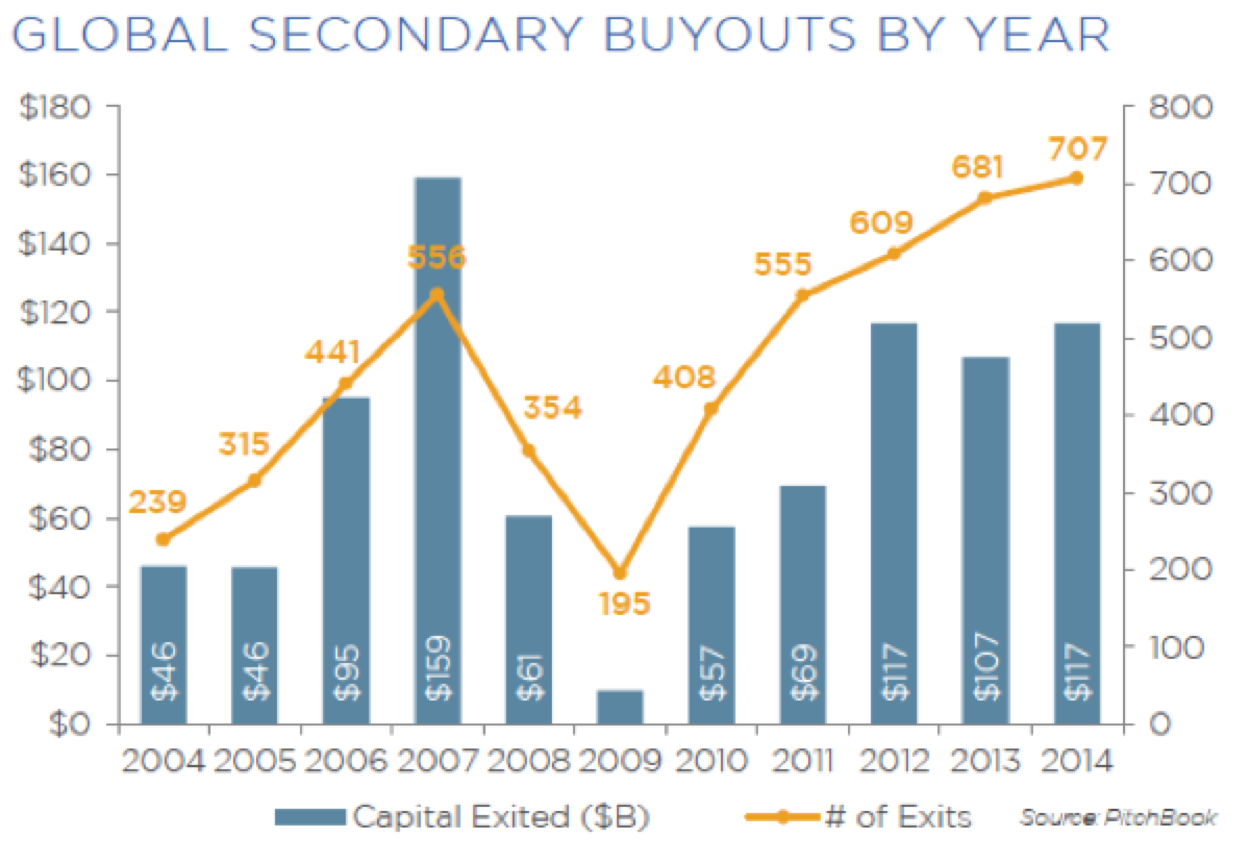
One of the big differences between 2014 and 2007 is the deal-making landscape, which has become much more difficult in recent years. Finding quality platform companies at reasonable valuations is much harder today, and SBOs are helping PE firms stay active in the market and put their always-growing dry powder levels to work. That might irk their LPs, which are funneling money back into the PE cycle only to find themselves buying and selling the same companies to themselves if they’re investors in both GPs. SBOs also hurt overall returns, with one research paper pegging the loss at $0.40 less cash per $1.00 invested and a 15% decline in IRR. In this environment, LPs might be a little more understanding about SBO levels, considering how much strategics are willing to bid for their acquisition targets. But LPs are probably chafing at the sizes of those SBOs, which hit a median of $295 million in 2014 as an exit size, up from $240 million in 2013 and $189 million in 2012.



Latest news

PIK Your Next Adventure
Every amended PIK loan hits the same crossroad. Not everyone ends up at the same destination.

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.
Private Credit Defaults 101: Beyond the Noise
Like any good school year, this series went by fast. But unlike the end of the year, we’re not out for the summer.