


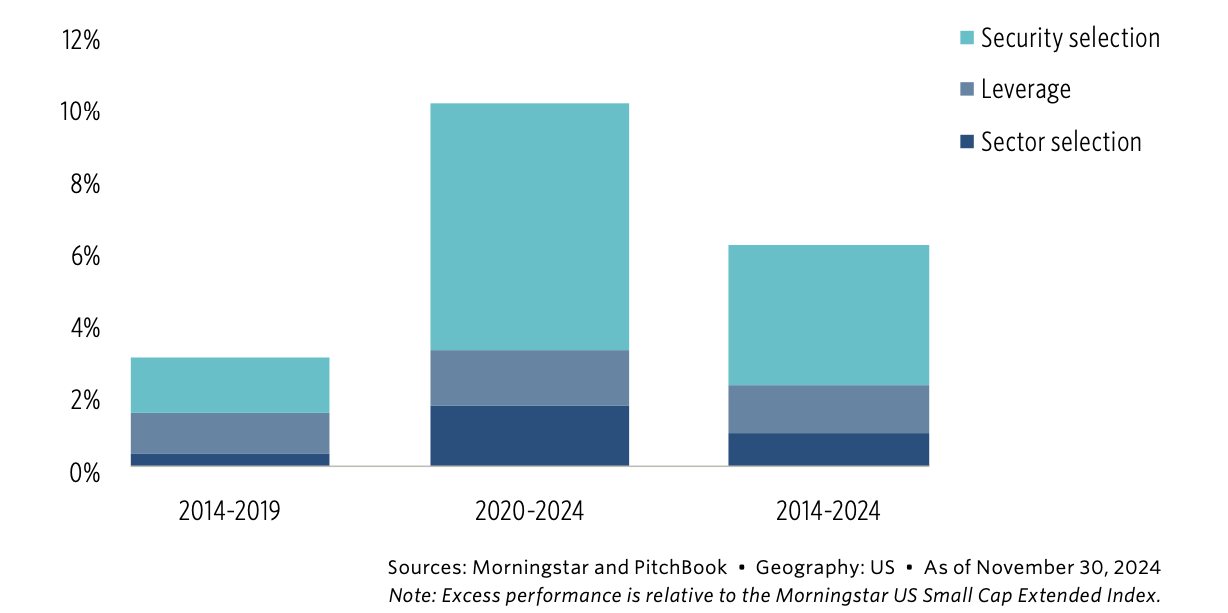
Morningstar PitchBook Buyout Replication Index excess performance attribution (annualized)
Download PitchBook’s Report here.
A returns-based factor analysis using the Fama-French five-factor model plus momentum reveals that the positive alpha from security selection can be explained primarily by a higher market beta. On average, the Index had a monthly excess return of 0.2%, which was not statistically significant. The Index loaded strongly on the broader market with an equity beta of 1.7, but this was consistent with the equity beta of the sector- and leverage-adjusted Morningstar US Small Cap Extended Index, suggesting that the high beta was driven by leverage rather than the model selecting higher beta stocks. The Index had a higher beta to the size factor than the adjusted Morningstar US Small Cap Extended Index, which is consistent with the fact that take-private deals involve companies at the smaller end of even the small-cap universe. Interestingly, we did not find a significant loading to the value factor, making it different from similar past studies.11 In the holdings-based analysis that follows, we show that this is likely due to buyout managers having a different definition of value than the academic definition, which compares equity book value to market value.
(Past performance is no guarantee of future results.)


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
