



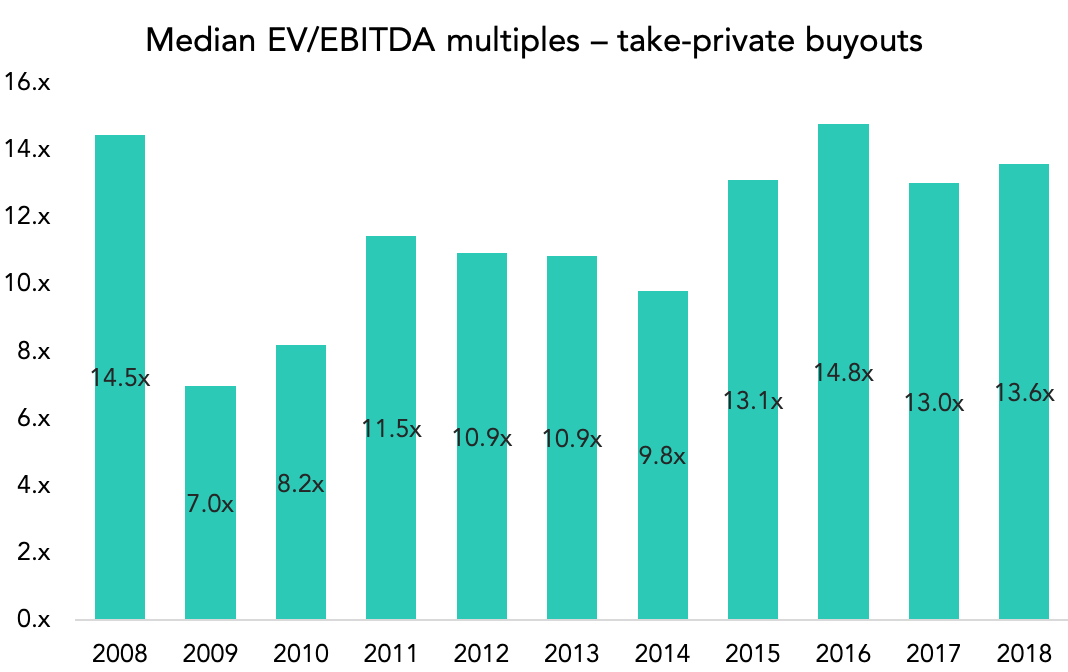
That’s according to Bain & Company, which made a salient point: “Despite the run-up in equity prices, public investors often undervalue companies they don’t understand.” That’s true, and the point is emphasized as public and private equity market multiples continue to converge. Bain notes that publicly traded companies in the $2-$10 billion range “could be purchased for a multiple plus take-private premium that is still below the average private market multiple.” Our numbers suggest that point is true but on a case-by-case basis, as median EV/EBITDA buyout multiples overall are at least two turns cheaper than take-private multiples. The chart above is from a note we’ll be releasing next week on take-privates, which also found a big discrepancy in deal sizes. Take-privates range from twice as large to eight times as large as bread-and-butter buyouts, depending on the year.
We made the point a couple weeks ago that larger funds target larger deals, and because relatively few funds can pull off those larger deals, there is less competition for them. That helps compress entry prices for take-privates, which would undoubtedly be much higher if there were hundreds of mega-funds roaming around instead of dozens. What happens when they need to be exited, though? Going back to Bain’s earlier point, some companies are less understood by public investors, and spending five years under private equity control won’t necessarily change that fact if the PE sponsors opt to take those companies public again. That might explain why so few take-privates end up back in the public markets—the vast majority of those exits are done via acquisition or secondary buyout. There’s little reason to expect that to change as long as public and private multiples remain as close as they are. If sellers can fetch high exit multiples from private buyers, there’s less justification for taking those companies public again anyway. Some, arguably, didn’t belong there in the first place, and they wind up shedding their ticker symbols for good.
Contact: Alex Lykken
alex.lykken@pitchbook.com


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…