



Download PitchBook’s Report here.
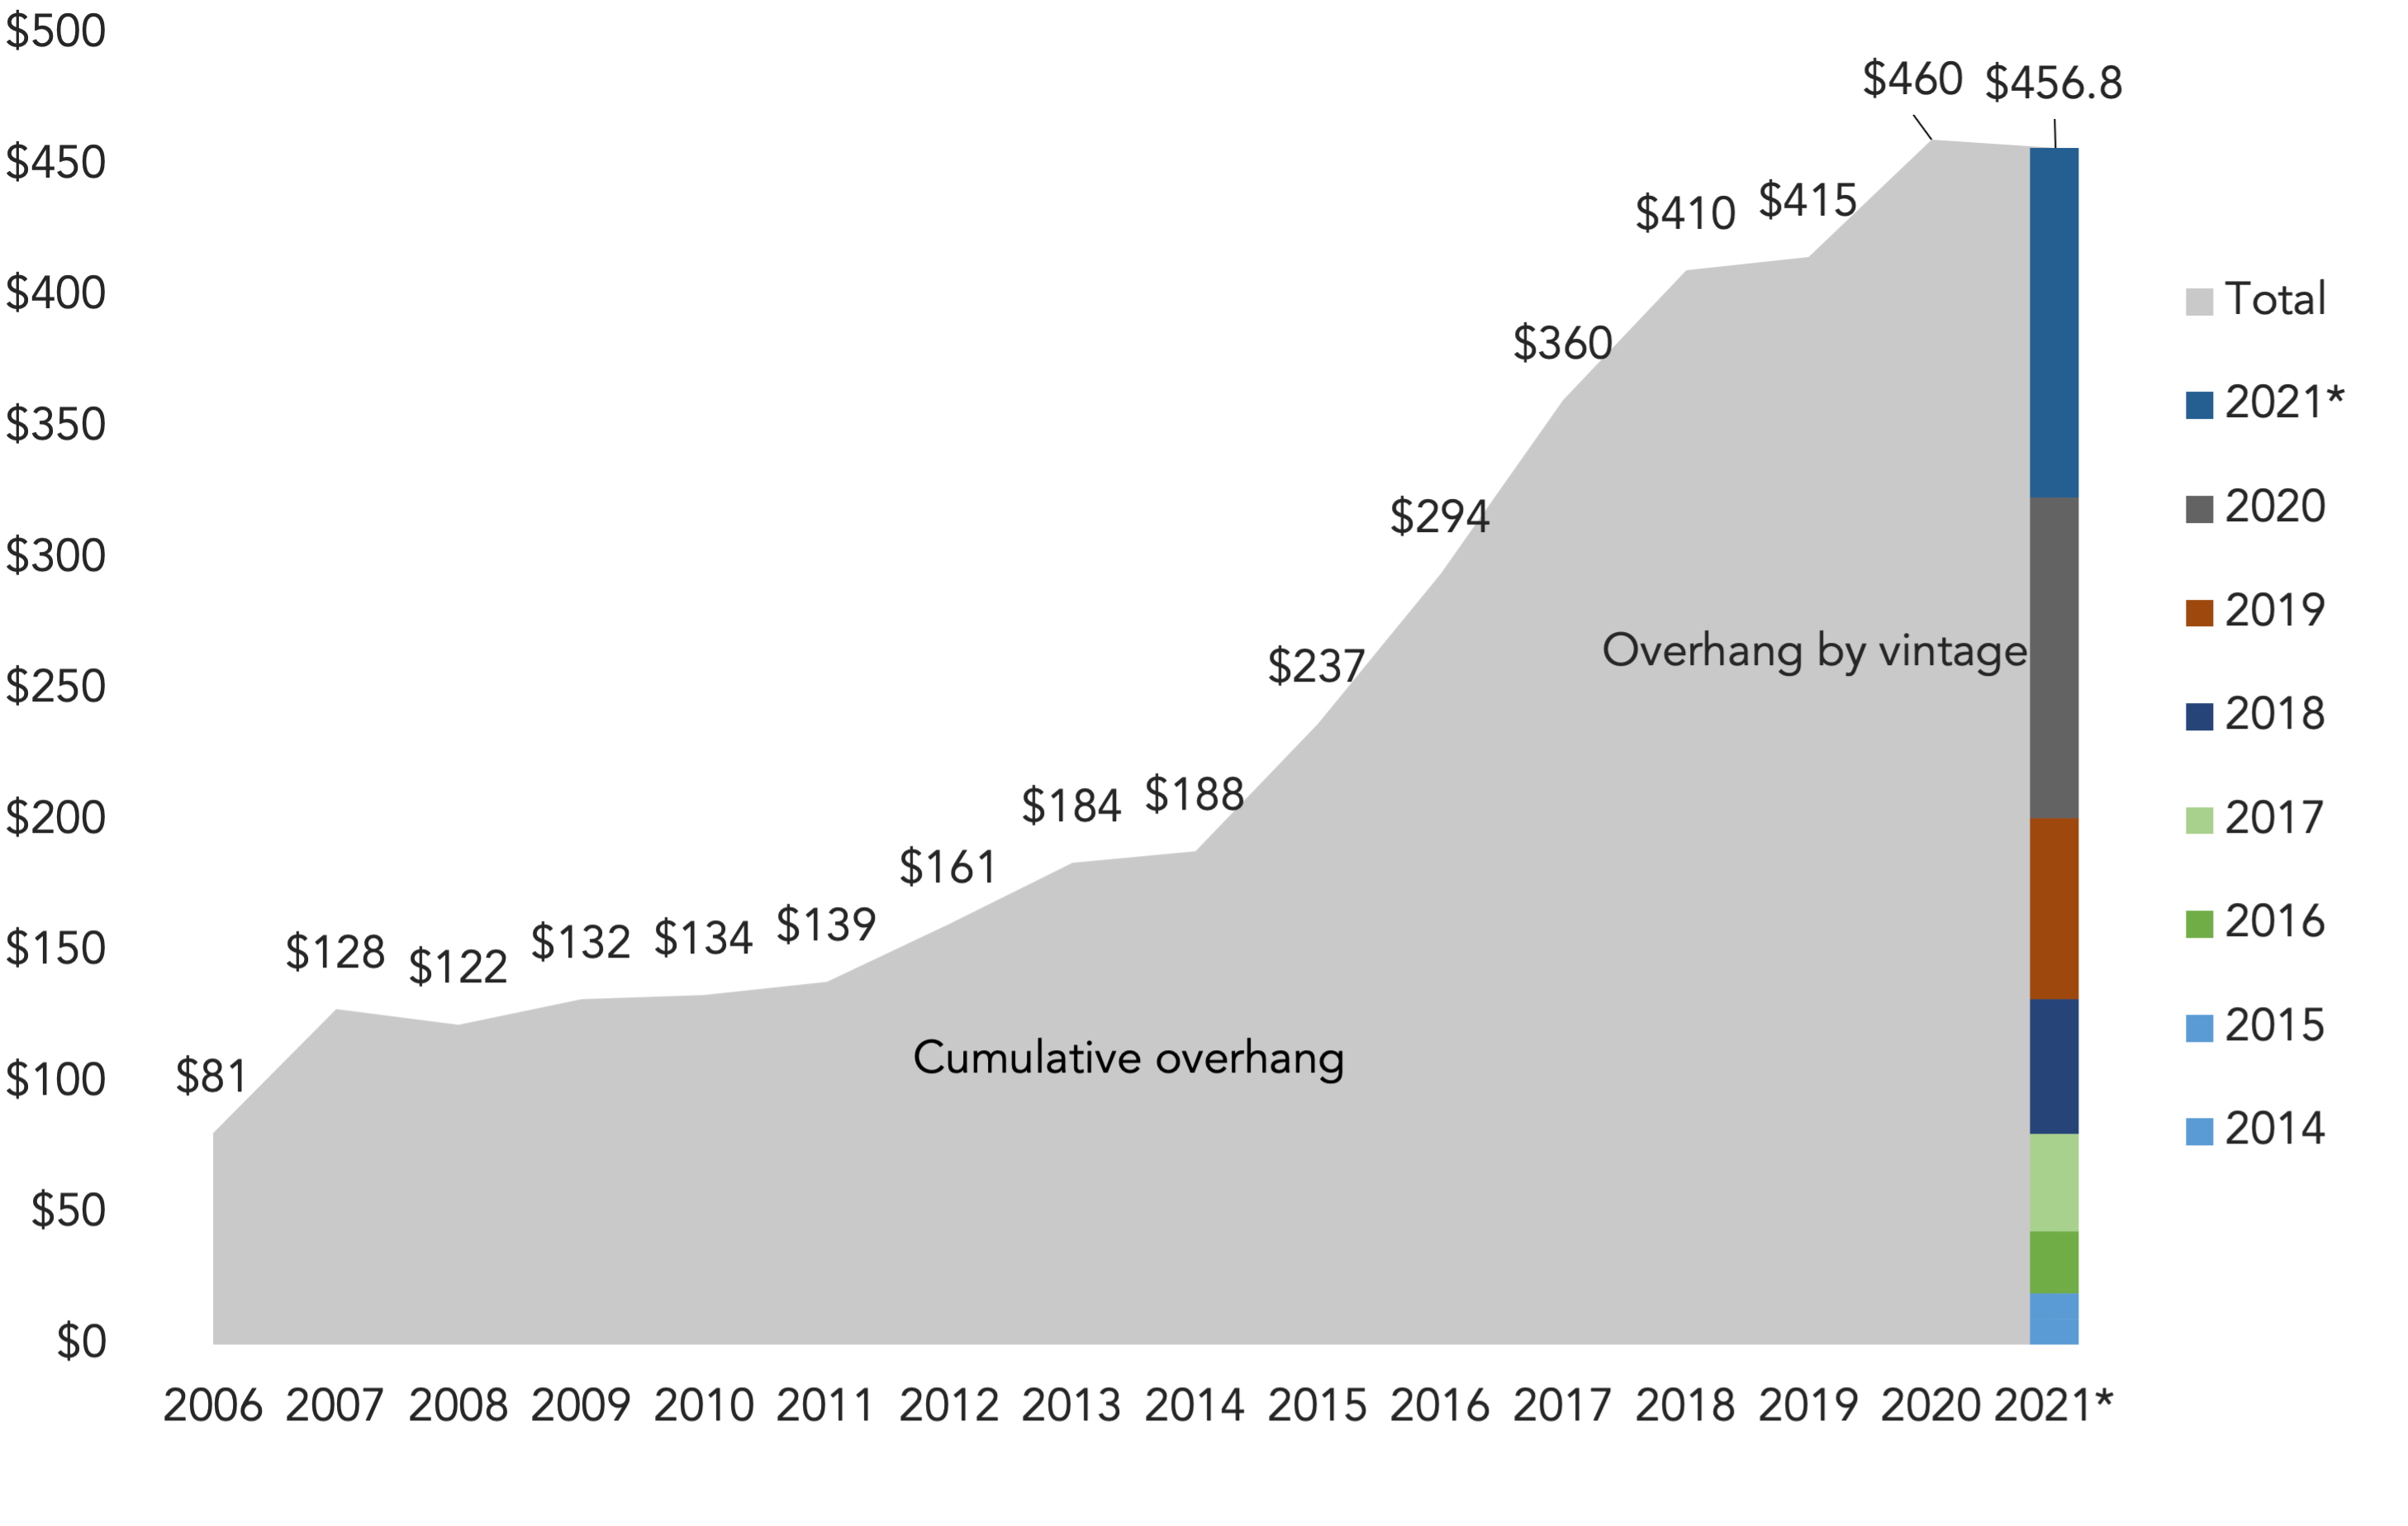
The cumulative capital overhang for the private debt industry dropped for the first time in more than a decade, according to PitchBook’s Annual Global Private Debt Report. It’s another indication of how accelerant today’s PE market is, considering almost $1 trillion of private debt capital has been raised over the past five years. Between 2020 and 2021 vintages, about $256 billion in dry powder is at the ready, $200 billion of which is stored in $1B+ funds. Sub-$1B funds hold the remaining $55.8 billion, less than 30% of the total.
Dominant $1B+ funds haven’t always been the norm. In 2014, 58% of private debt capital raised was above the $1B threshold; last year, they accounted for 81% of the fundraising total. Over the intervening years, dry powder levels have more than doubled, from $188 billion in 2014 to ~$460 billion today. The underlying numbers show that those gains are solely due to more big funds raising bigger and bigger funds. All of the other fund size ranges—chiefly the middle market and below—are more or less the same today as they were in 2014.
(Past performance is no guarantee of future results.)


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…