



Download PitchBook’s Report here.
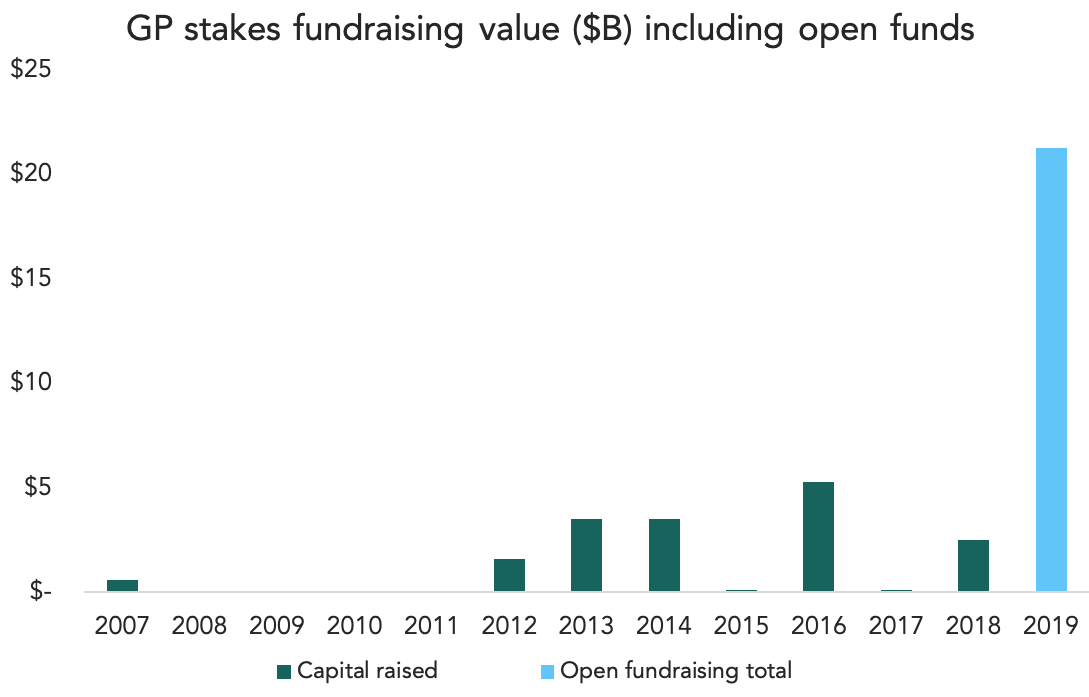
An awaited flood of GP stakes fundraising is starting to take shape. The funds currently in the market will eventually amass more capital for the strategy than the past decade combined, according to our recently released analyst note. The majority of those raises will be housed in three of the largest players in the market: Blackstone (aiming for $6 billion), Dyal (expecting to close on $7 billion), and Goldman Sachs (seeking $4 billion). Those three funds alone will constitute about $17 billion in combined GP stakes funds, which prompts the question of where exactly the money will wind up. Goldman and Blackstone are both targeting mid-market GPs. Goldman, true to form, is apparently wandering off the beaten path by expanding to VC stakes—VC funds tend to be smaller anyway and rely much more heavily on outsized carry, but Goldman likely knows what it’s getting itself into. Across the board, though, any GP stakes strategy tends to veer toward high performers with steady AUM growth and the fees that come with it. Our past research points to a preference for managers with lots of capital and an appetite for top performers with aggressive fund step-ups. Of the firms that have received a GP stakes investment, over 60% of their previous funds were in the top two quartiles, on average. Over the past three years, they’ve also enjoyed step-ups of nearly twice the industry average.
Fundraising and dealmaking are always exciting, but the exit question isn’t as obvious in this market. Smaller firms with smaller funds likely have more options to play with, including sales to strategic investors or sovereign wealth funds, or possibly selling via secondary sales. The bigger guys might have to get creative, like publicly listing their stakes through entities like Affiliated Managers Group. Michael Rees, a Dyal managing director who recently did a webinar with us, has said in the past that LPs see GP stakes as a yield play and may not want to focus on the exit. Dyal, for its part, is mulling whether to hold onto their assets in perpetuity, which would force underlying investors to use the secondaries market to sell.


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…