



Download PitchBook’s Report click here.
“Past performance does not guarantee future results.” Finance professionals have probably read that boilerplate disclosure so many times they may not even notice it anymore. And while that phrase has arguably reached truism status, there is a residual belief that past performance is relevant to future performance. If performance is persistent, it would have major implications for asset class allocations. According to our recent Benchmarks Report, we found evidence that performance is broadly persistent among PE funds and their successors. That merits a disclosure of our own: The correlations started to break down when we looked at regressions of net IRRs between funds within a fund family. In other words, the persistence we found was relative to the vintages assigned to each fund, and absolute returns were less predictive from one fund to the next.
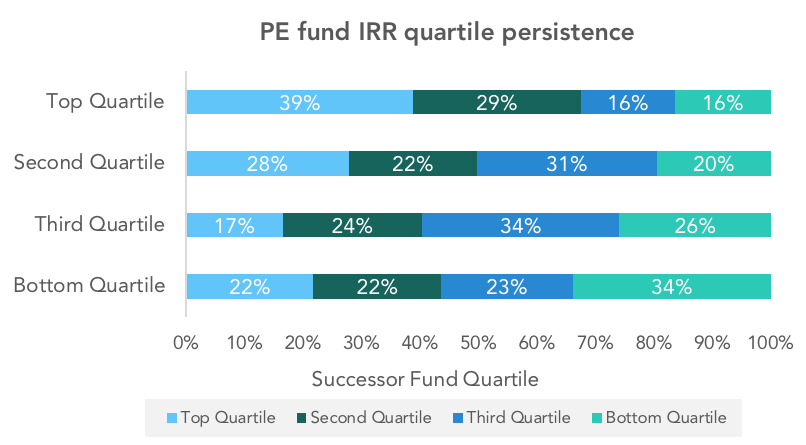
Top performers and bottom performers showed the most consistency. If performance from one fund to the next were random, 39% of top-quartile PE funds would produce a top-quartile successor. The inverse was also true, with 34% of bottom-quartile funds being followed by a bottom-quartile successor. The odds of a complete reverse for both top- and bottom-quartile performers was below 25%. In other words, only 16% of top-quartile funds were followed by a bottom-quartile successor, and 22% of bottom-quartile funds were followed by a top-quartile successor. It’s important to emphasize the caveat mentioned earlier: Top-quartile percentages vary wildly between vintages—a 15% IRR in the first fund’s vintage might qualify it as top-quartile, while a 20% IRR for its successor might only qualify as second- or third-quartile in a different vintage.
Past performance still doesn’t guarantee anything. But the data suggests it’s a good starting point for due diligence. Culture, talent and processes are much more easily transferred between funds, and LPs would be wise to look for consistency among those softer signals. The other wildcard to consider is first-time funds. We’ve noted in the past that recent first-time funds are performing relatively better than follow-on funds. Today’s first-timers are often spinning out as cohesive teams and going down market, bringing with them an institutional skillset to the middle- and lower-middle markets. They shouldn’t be overlooked by LPs, even if they fall outside of this discussion.


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…