



Download PitchBook’s Report here.
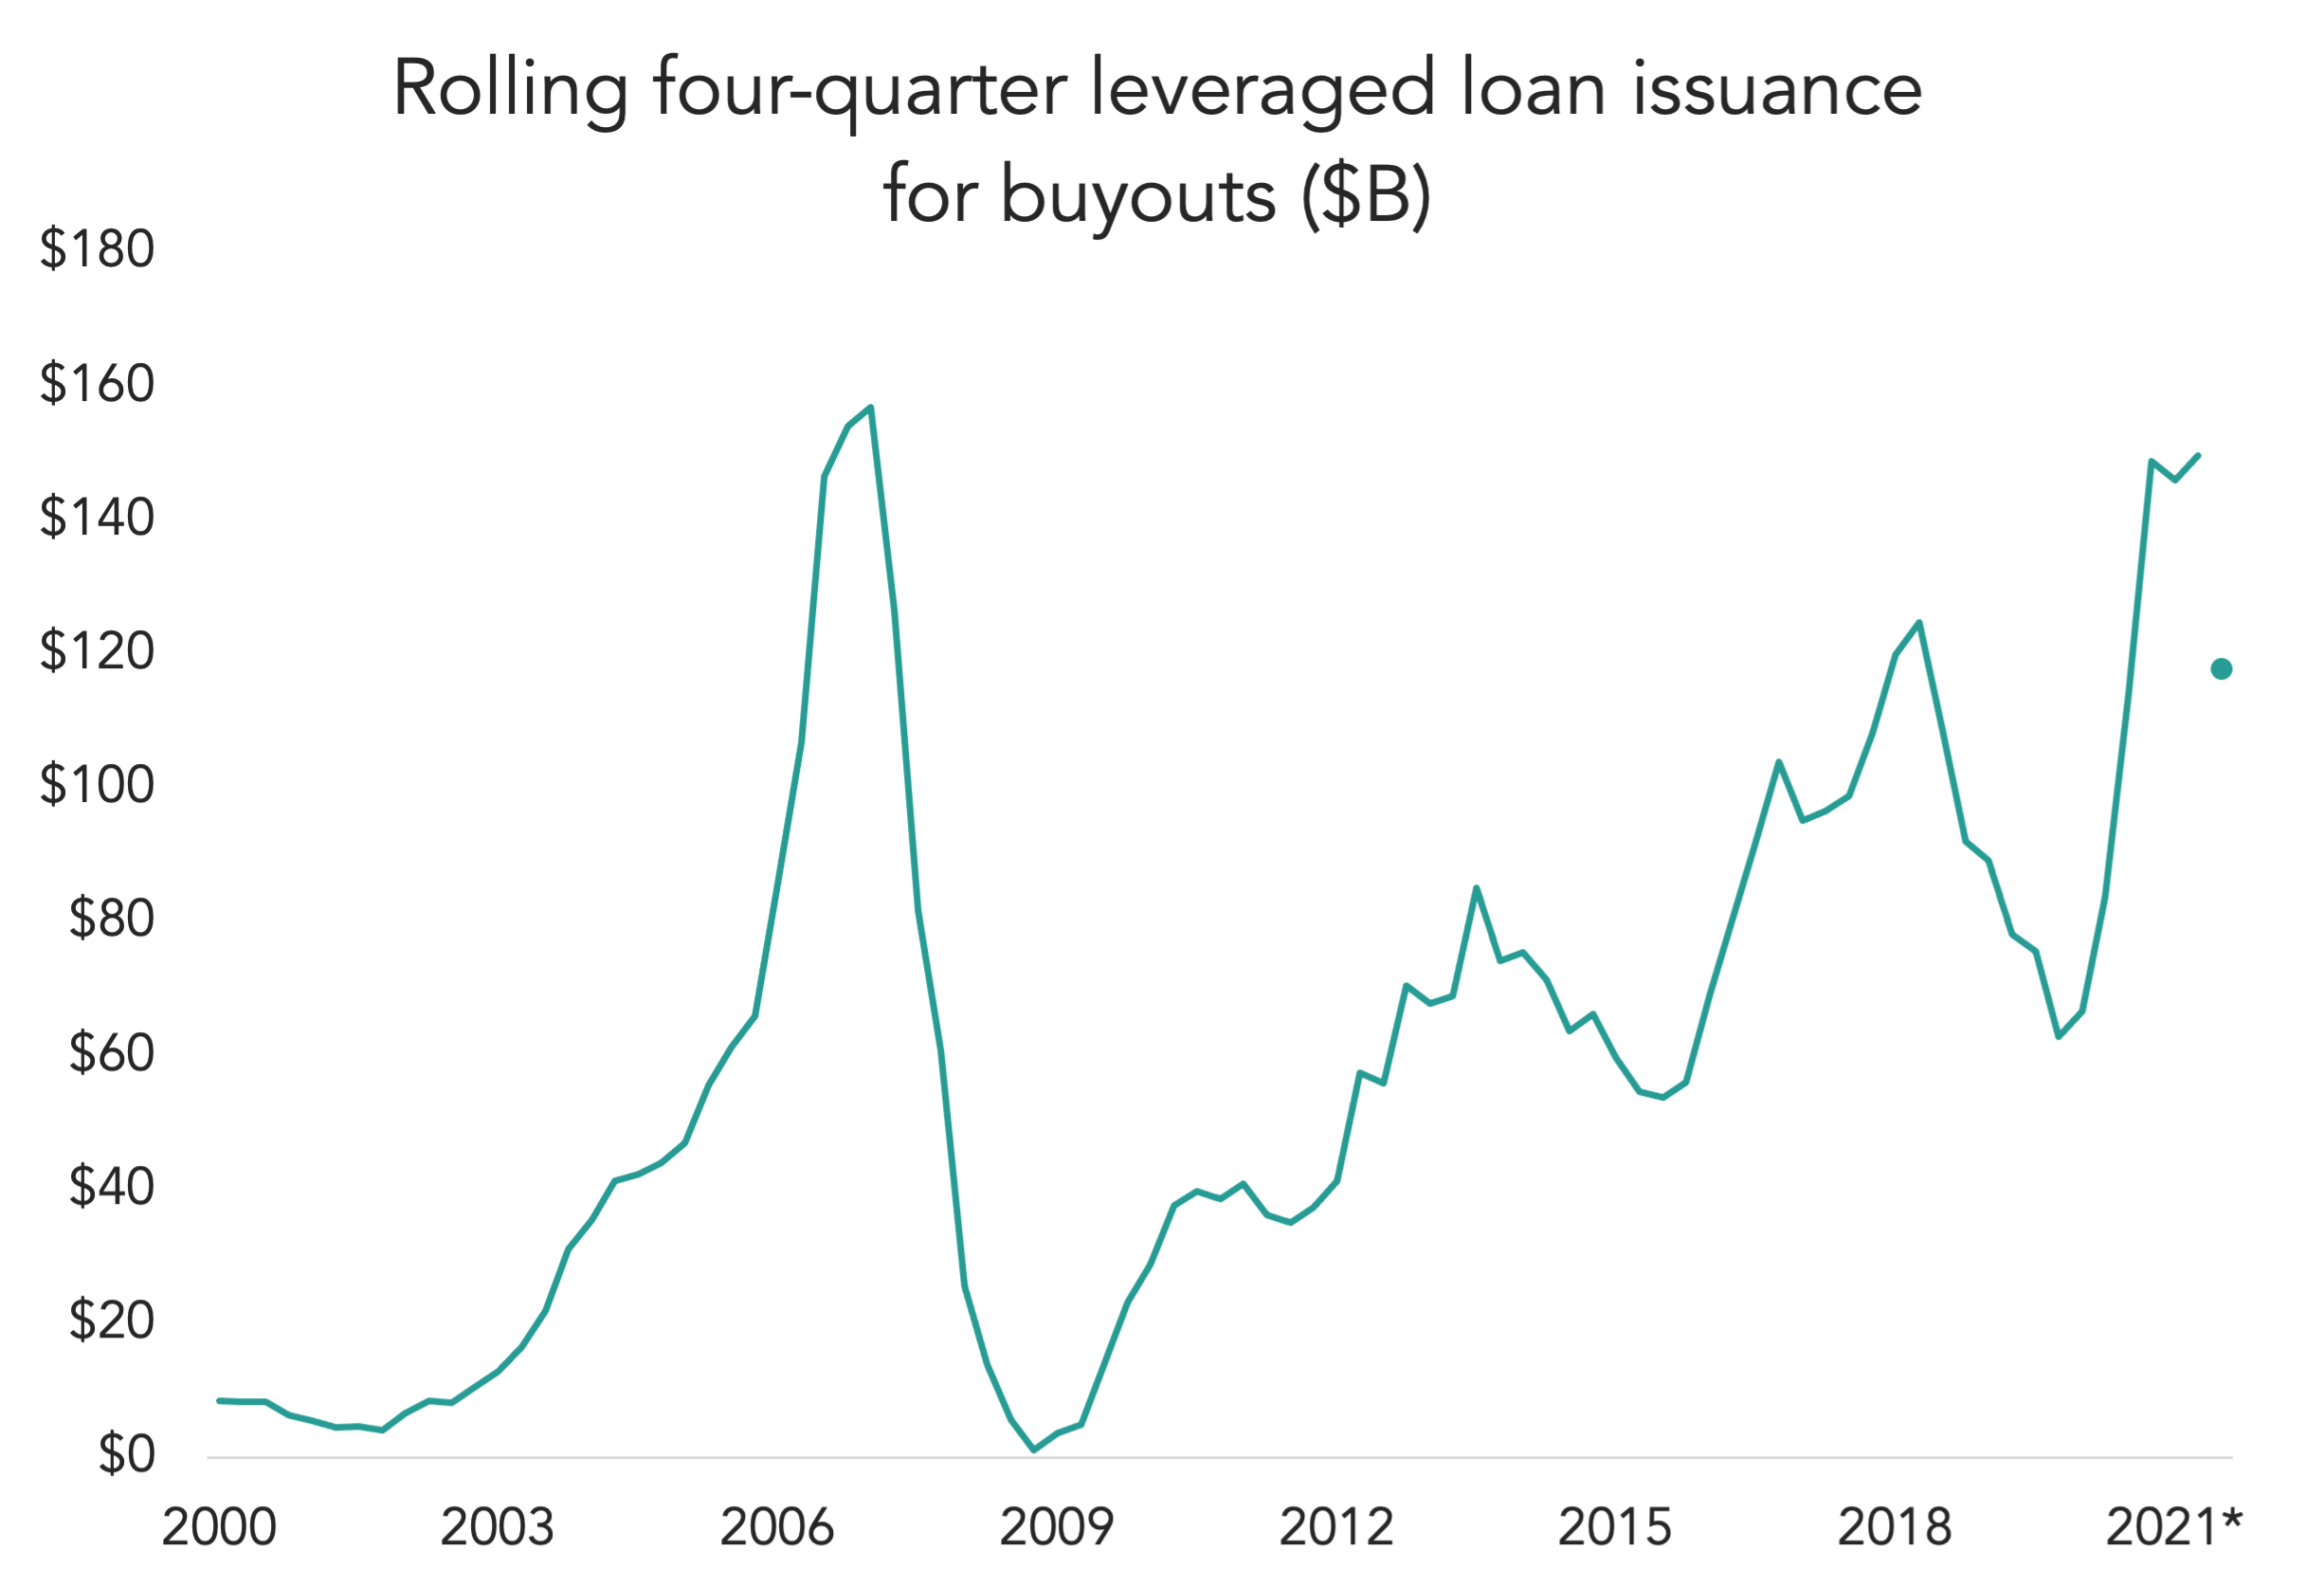
Leveraged loan issuance slowed noticeably in Q2, according to PitchBook’s latest Quantitative Perspectives: US PE enters a new regime. While still north of historical levels, the rolling sum fell to almost $118 billion in the second quarter, down from almost $150 billion just a quarter ago. Prior to Q2 2022, that figure was above $140 billion for three straight quarters. The pickup in deal activity led to a surge in outstanding value in the leveraged loan market, which has now passed $1.4 trillion in the US alone.
Credit quality of the overall leveraged loan market has softened since 2017. More than 64% of outstanding loans are now a single B, quite a bit higher than 2017, when only 45% of outstanding loans had that rating. What’s more, the financing costs for single B-rated loans have jumped from 4.3% to 5.9%, driven by increases in benchmark interest rates and credit spreads. Taken together, this suggests an elevated risk for companies if a downturn is around the corner. As the note points out, “it will be much more difficult to mitigate the impact of a continued increase in financing costs on companies that have already undergone a buyout, especially in the event of a recession.”
(Past performance is no guarantee of future results.)


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…