



Download PitchBook’s Report here.
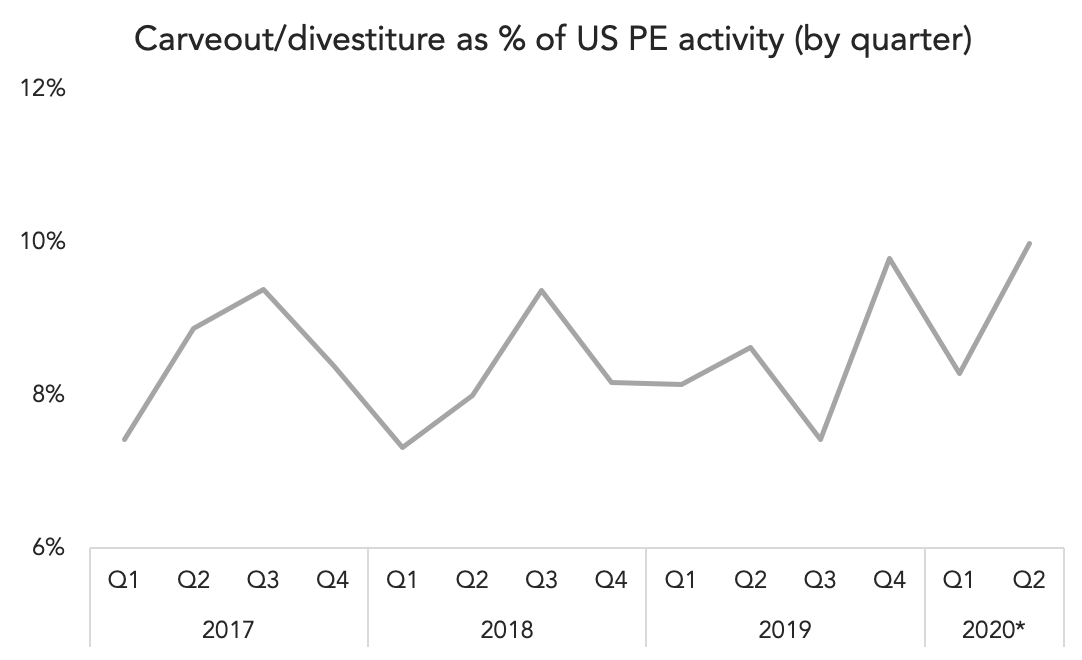
Carveouts are up slightly as a proportion of US PE activity, according to PitchBook’s latest Breakdown Report. They made up 10% of all deal flow in Q2, which is on the high end of what we’ve seen over the last three years. Carveouts didn’t boom in numbers in Q2 (but nothing else did either)—only 53 were done last quarter compared to 123 in Q4 2019. Still, the proportional jump is a small confirmation of what others have been saying—PE buyers are more than willing to take assets off the hands of corporate America in exchange for cash infusions. We wouldn’t be surprised to see another strong percentage in Q3, assuming the economy is still struggling. The energy sector is a potential wellspring for carveouts.
Divestiture expectations have been bubbling below the surface for a while now. To take one example, a recent EY survey in the banking sector found a post-COVID spike in divestiture plans. Before the pandemic hit, 61% of their respondents expected to initiate a sale within the next two years, but a re-survey in April shot up to 87%. It’s easy to imagine similar survey results in other sectors, particularly hard-hit ones like consumer or healthcare services. Revenue forecasts have become more difficult, and in addition to being one-time cash infusions, divestitures can help simplify the road ahead for struggling businesses. From PE’s perspective, those types of sales are easier to land in an environment like this—offers are being turned down elsewhere because many business owners, optimists by nature, are trying to ride out the storm without ceding the wheel. Corporate divestitures, on the other hand, are bottom-line financial decisions, not personal ones. The only question is what the price tag would be.


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…