


Download PitchBook’s Report here.
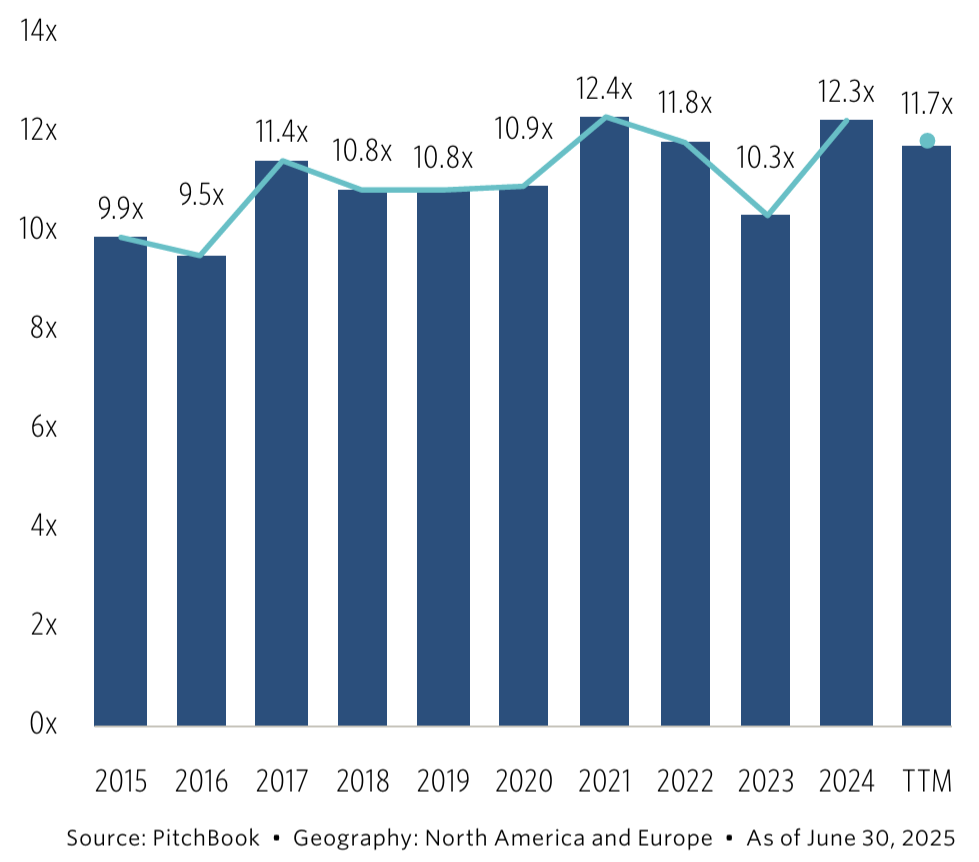
The EV/EBITDA multiple for PE buyouts stood at 11.7x for the TTM period ended June 30, 2025. This is comfortably above the recent trough of 10.3x in 2023, yet below the 12.3x registered in 2024. Compared with the 2017-2019 period, where multiples ranged from 10.8x to 11.4x, the current TTM value is on the higher end of historical norms. The recovery from the dip in 2023 reflects better credit availability, less concern around inflation and the outlook for rates, and higher-quality companies in the mix of transactions. For EV/revenue multiples within PE buyouts, the TTM figure is 2x, just below the 2.1x in the 2023-2024 period. This multiple also exceeds the 2017-2019 average range of 1.7x to 1.8x.
(Past performance is no guarantee of future results.)



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.