



Download PitchBook’s Report here.
Every December, PitchBook makes a slew of predictions about industry trends in the upcoming year. That’s been a tricky gambit since 2019. In successive years, the industry has navigated a global pandemic, a skyscraper of a recovery, and a slowdown driven by unavoidable macro trends. Last December, the prevailing mood was that, yes, deal flow would decline but would remain at very healthy levels. There was some spillover of 2021 euphoria into Q1 2022, but 2022 is starting to feel like a mild hangover.
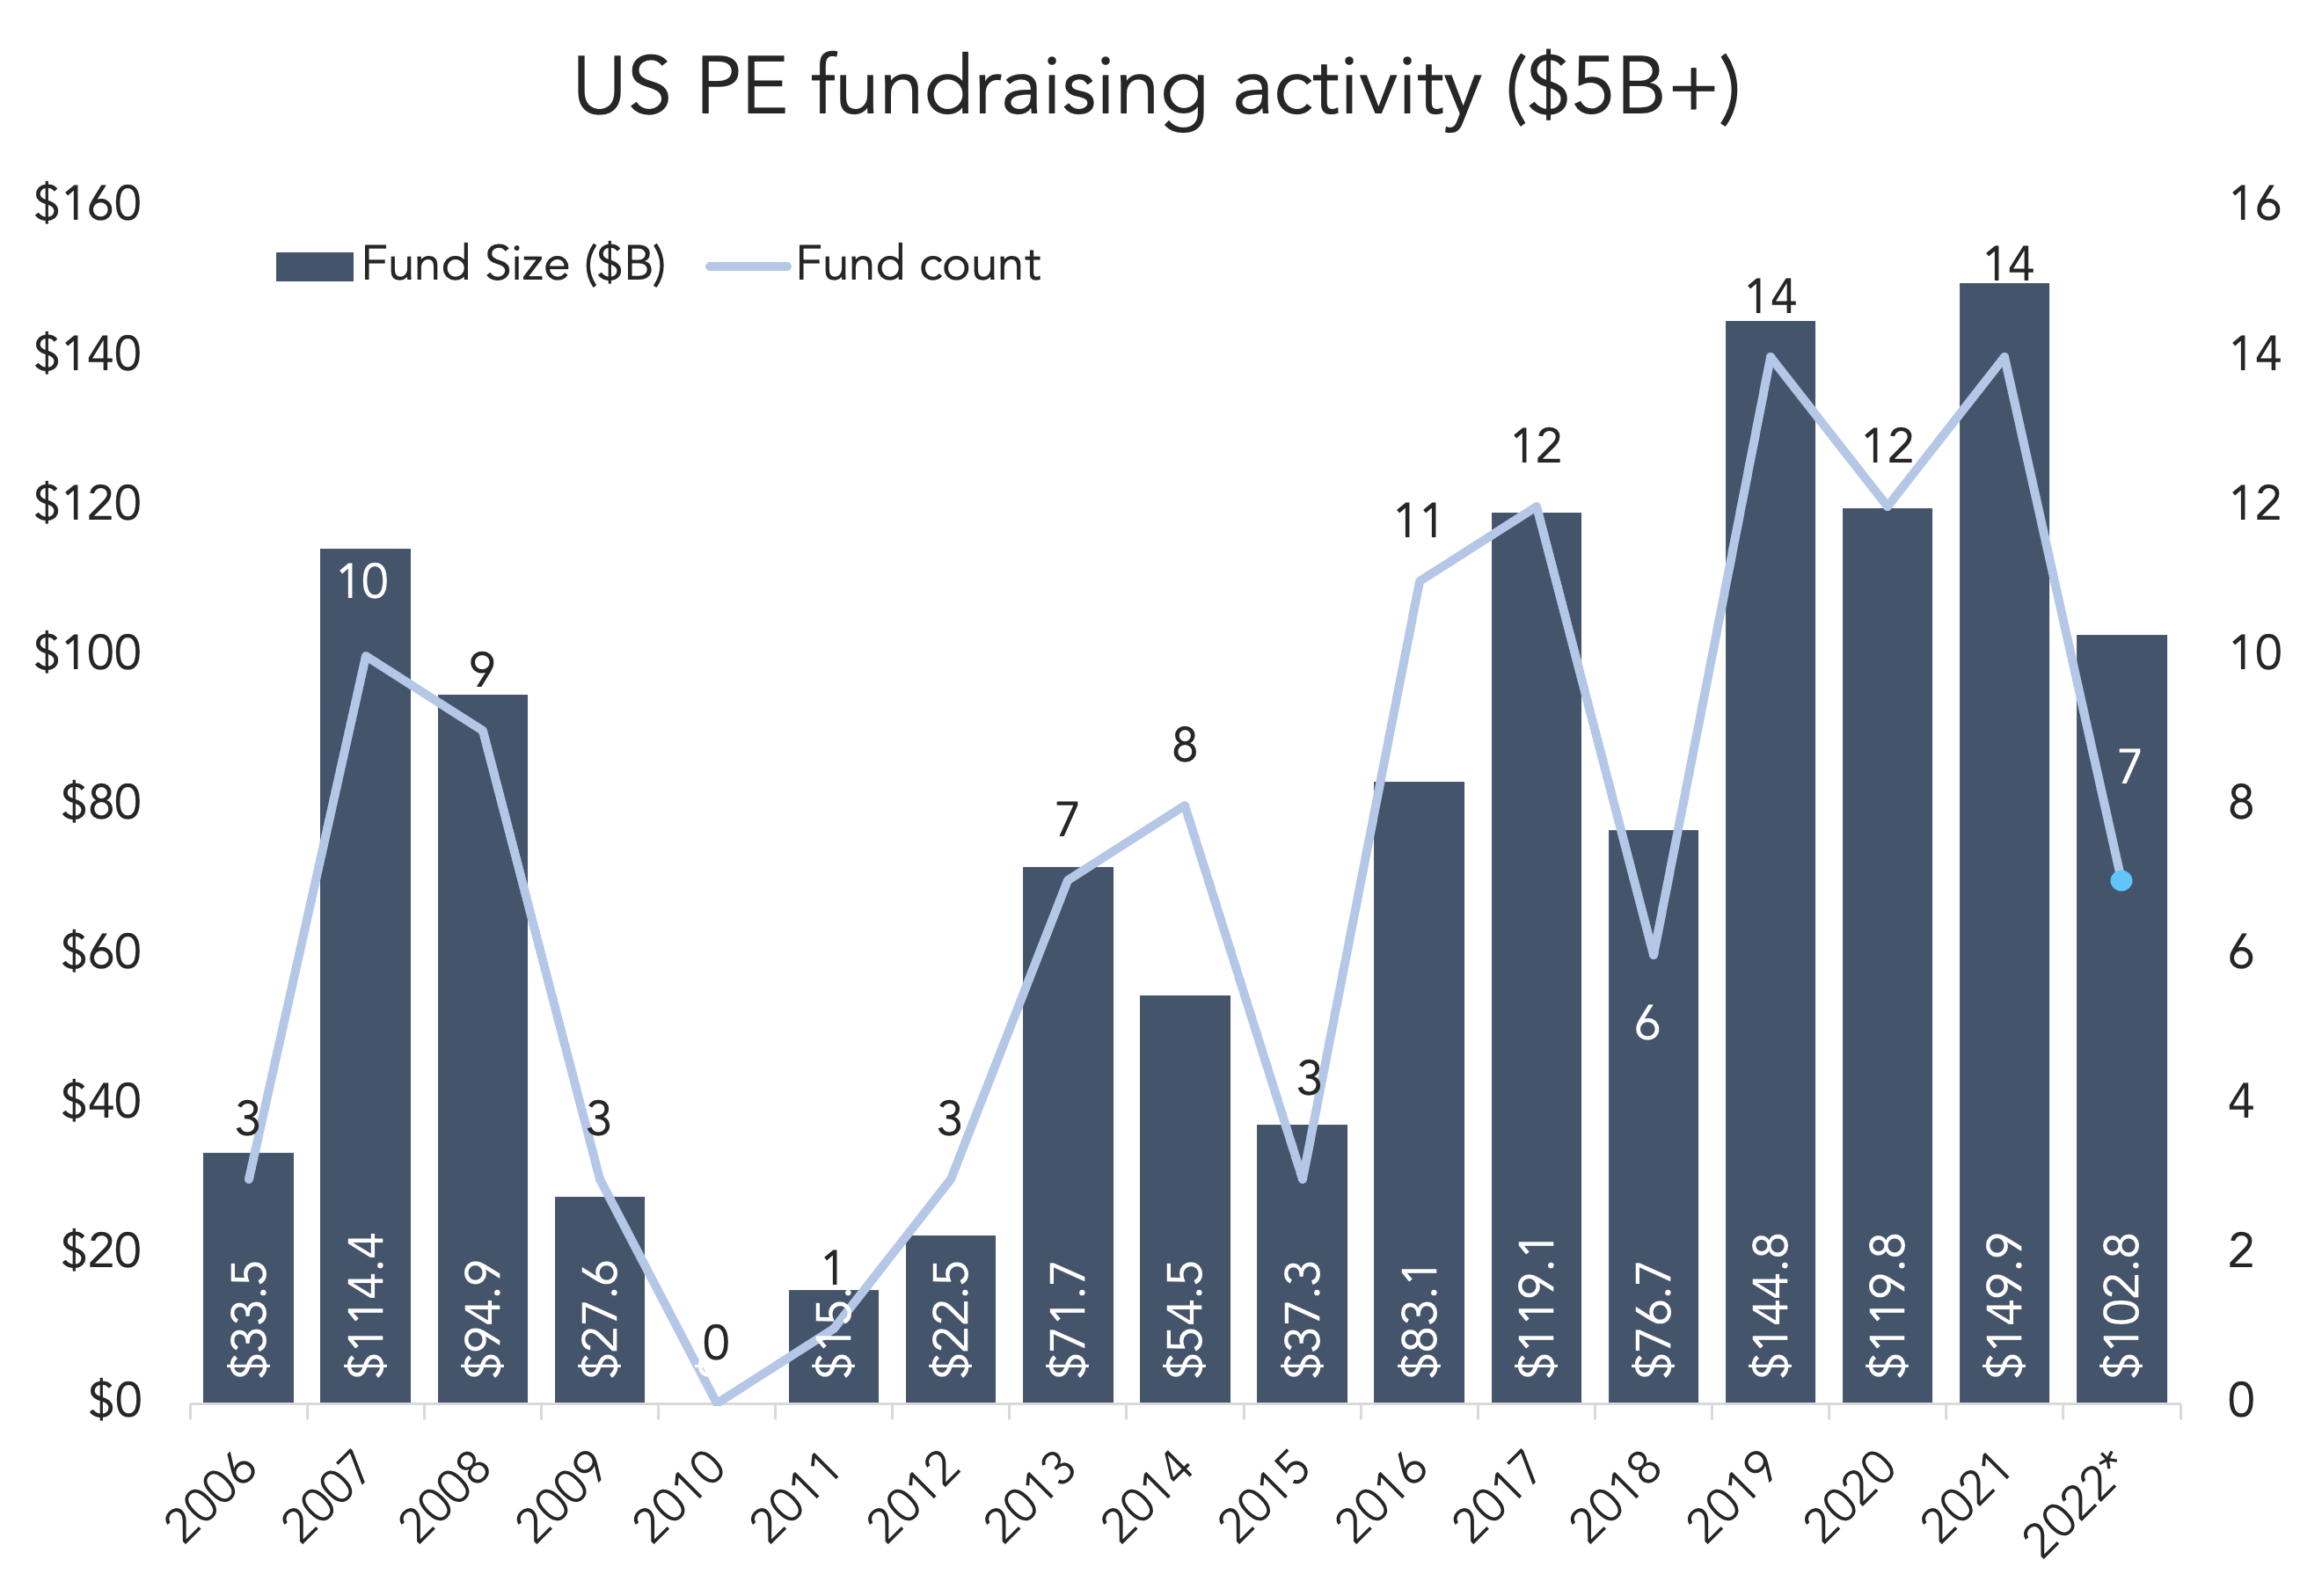
We revisited some of our predictions in a new analyst note, 2022 US Private Equity Outlook: H1 Follow-Up. One of our predictions was a big year for mega-funds, which has largely borne out. Specifically, we called for $250 billion to be raised in total, including the three largest-ever buyout funds. At $102.8 billion through June, mega-funds are well on pace to break last year’s mark of $149.9 billion. The seven $5B+ funds that have closed this year include KKR, Clearlake Capital and Advent International, but several others are still in the market. Thoma Bravo has raised $20 billion so far for its latest flagship, which is expected to close later this year. Apollo had planned on raising $25 billion and is now aiming to raise half of that in Q3, shifting its timetable a bit. If those two funds closed this year, 2022 would move past last year’s record. One question is whether LPs can accommodate what’s being offered to them, as exits slow and distributions back to LPs get thinner as a result.
(Past performance is no guarantee of future results.)


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…