


Like any good school year, this series went by fast. But as class comes to an end, there’s one theme that’s been top of mind here at The Lead: “noise.” Looking back on how this year unfolded, it’s never been more important for investors, institutional and high net worth alike, to cut through it and focus on the facts and fundamentals.
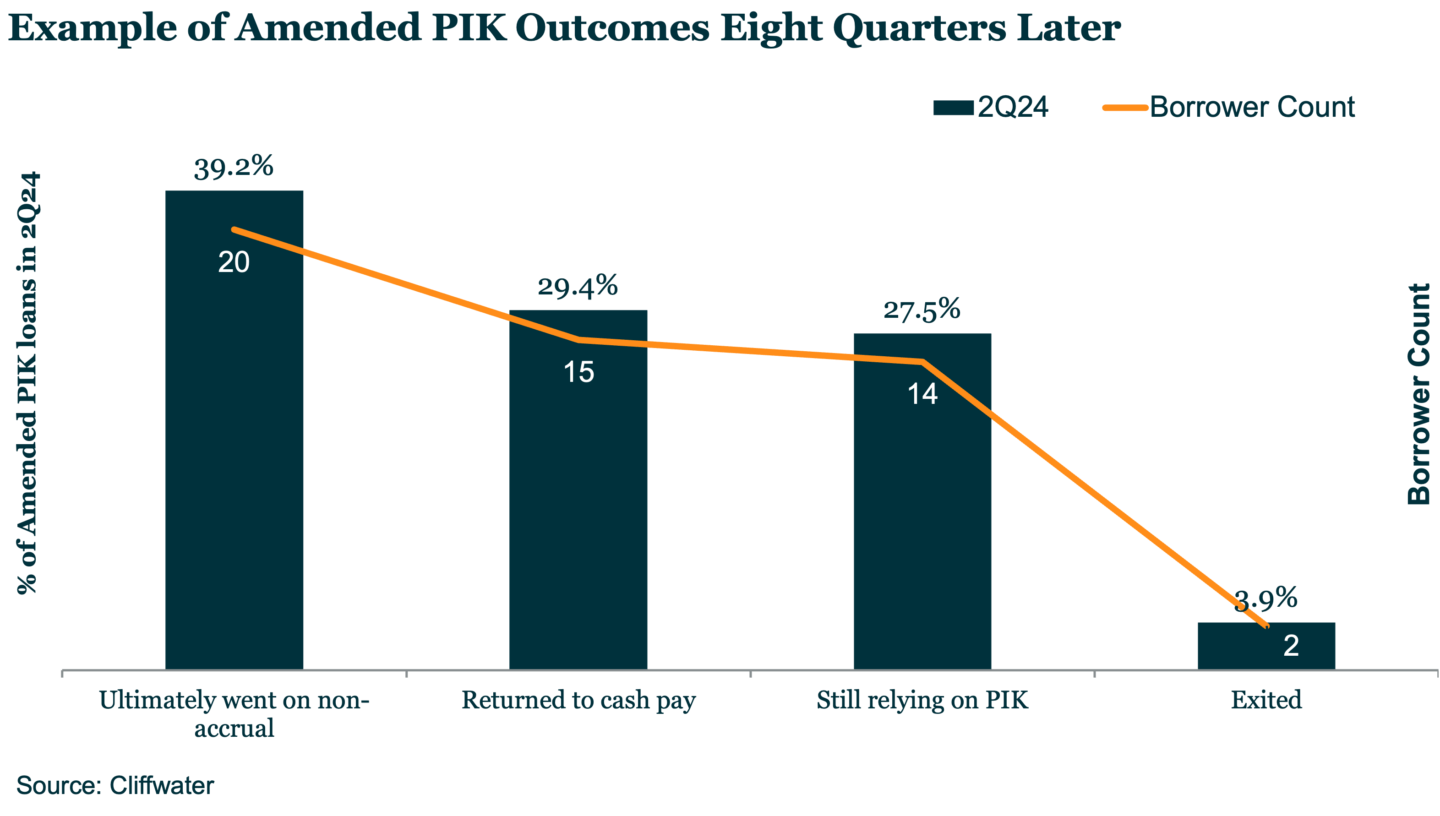
Our goal with this series was to give you the tools to separate signal from noise, especially against headlines like Private Credit Defaults Are 1%, 6% or 19%, Depending Who You Ask – Bloomberg. As we’ve covered throughout the series, including in Different Numbers, Different Stories, and in conversations with experts on our webinar, you don’t need to know the exact details. You just need a general understanding of what’s driving these numbers. For example, at the low-end of the range, that’s generally going to reflect “harder” measures of defaults such as missed payments, bankruptcies and distressed restructurings. Conversely, a higher rate is more likely to include items like maturity extensions, amended PIK, non-accruals and covenant trips. These measures can be a sign of stress, but that is not always the case. In fact, a recent Cliffwater research note puts some context around this. Of the PIK loans tracked, 40% eventually moved to non-accrual, but 30% returned to cash pay (see Chart). That’s exactly why these figures are worth reading alongside other measures, rather than in isolation.
It’s also worth asking why that gap between hard and soft defaults has widened in the first place. Borrowers are still working through a substantial rate shock, with base rates moving from the zero lower bound to 4% today. Lenders have responded by extending maturities and, in some cases, preserving cash. But that rise hasn’t necessarily translated into losses, with the loss given default rate remaining around 1.1%.
None of this means we should ignore the pockets of stress discussed in Where Are We in the Credit Cycle? But history matters. When a headline cites a record-high default rate, how long has it actually been measured? In several cases, the data only goes back to 2024 – not even a full cycle. Measured against a longer lookback, many of these rates are simply migrating back toward their long-term average. In short, this is a normalization of the credit cycle, not a deterioration.
Going forward, we’ll keep watching how these softer credit events evolve, alongside other indicators like loans marked below 80, PIK loans marked below 90, and interest coverage ratios under 1x.
Noise will always be part of this market. The difference now is you know which signals are worth tuning into, because you understand how a default gets defined, how to read a rate and what’s driving it, how a recovery determines what you actually lose, and how it all ties back to where we sit in the cycle.
As promised, there’s no pop quiz, no final exam. Thanks for attending class this semester. We’ll see you in 201.


Latest news
Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.
Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…