


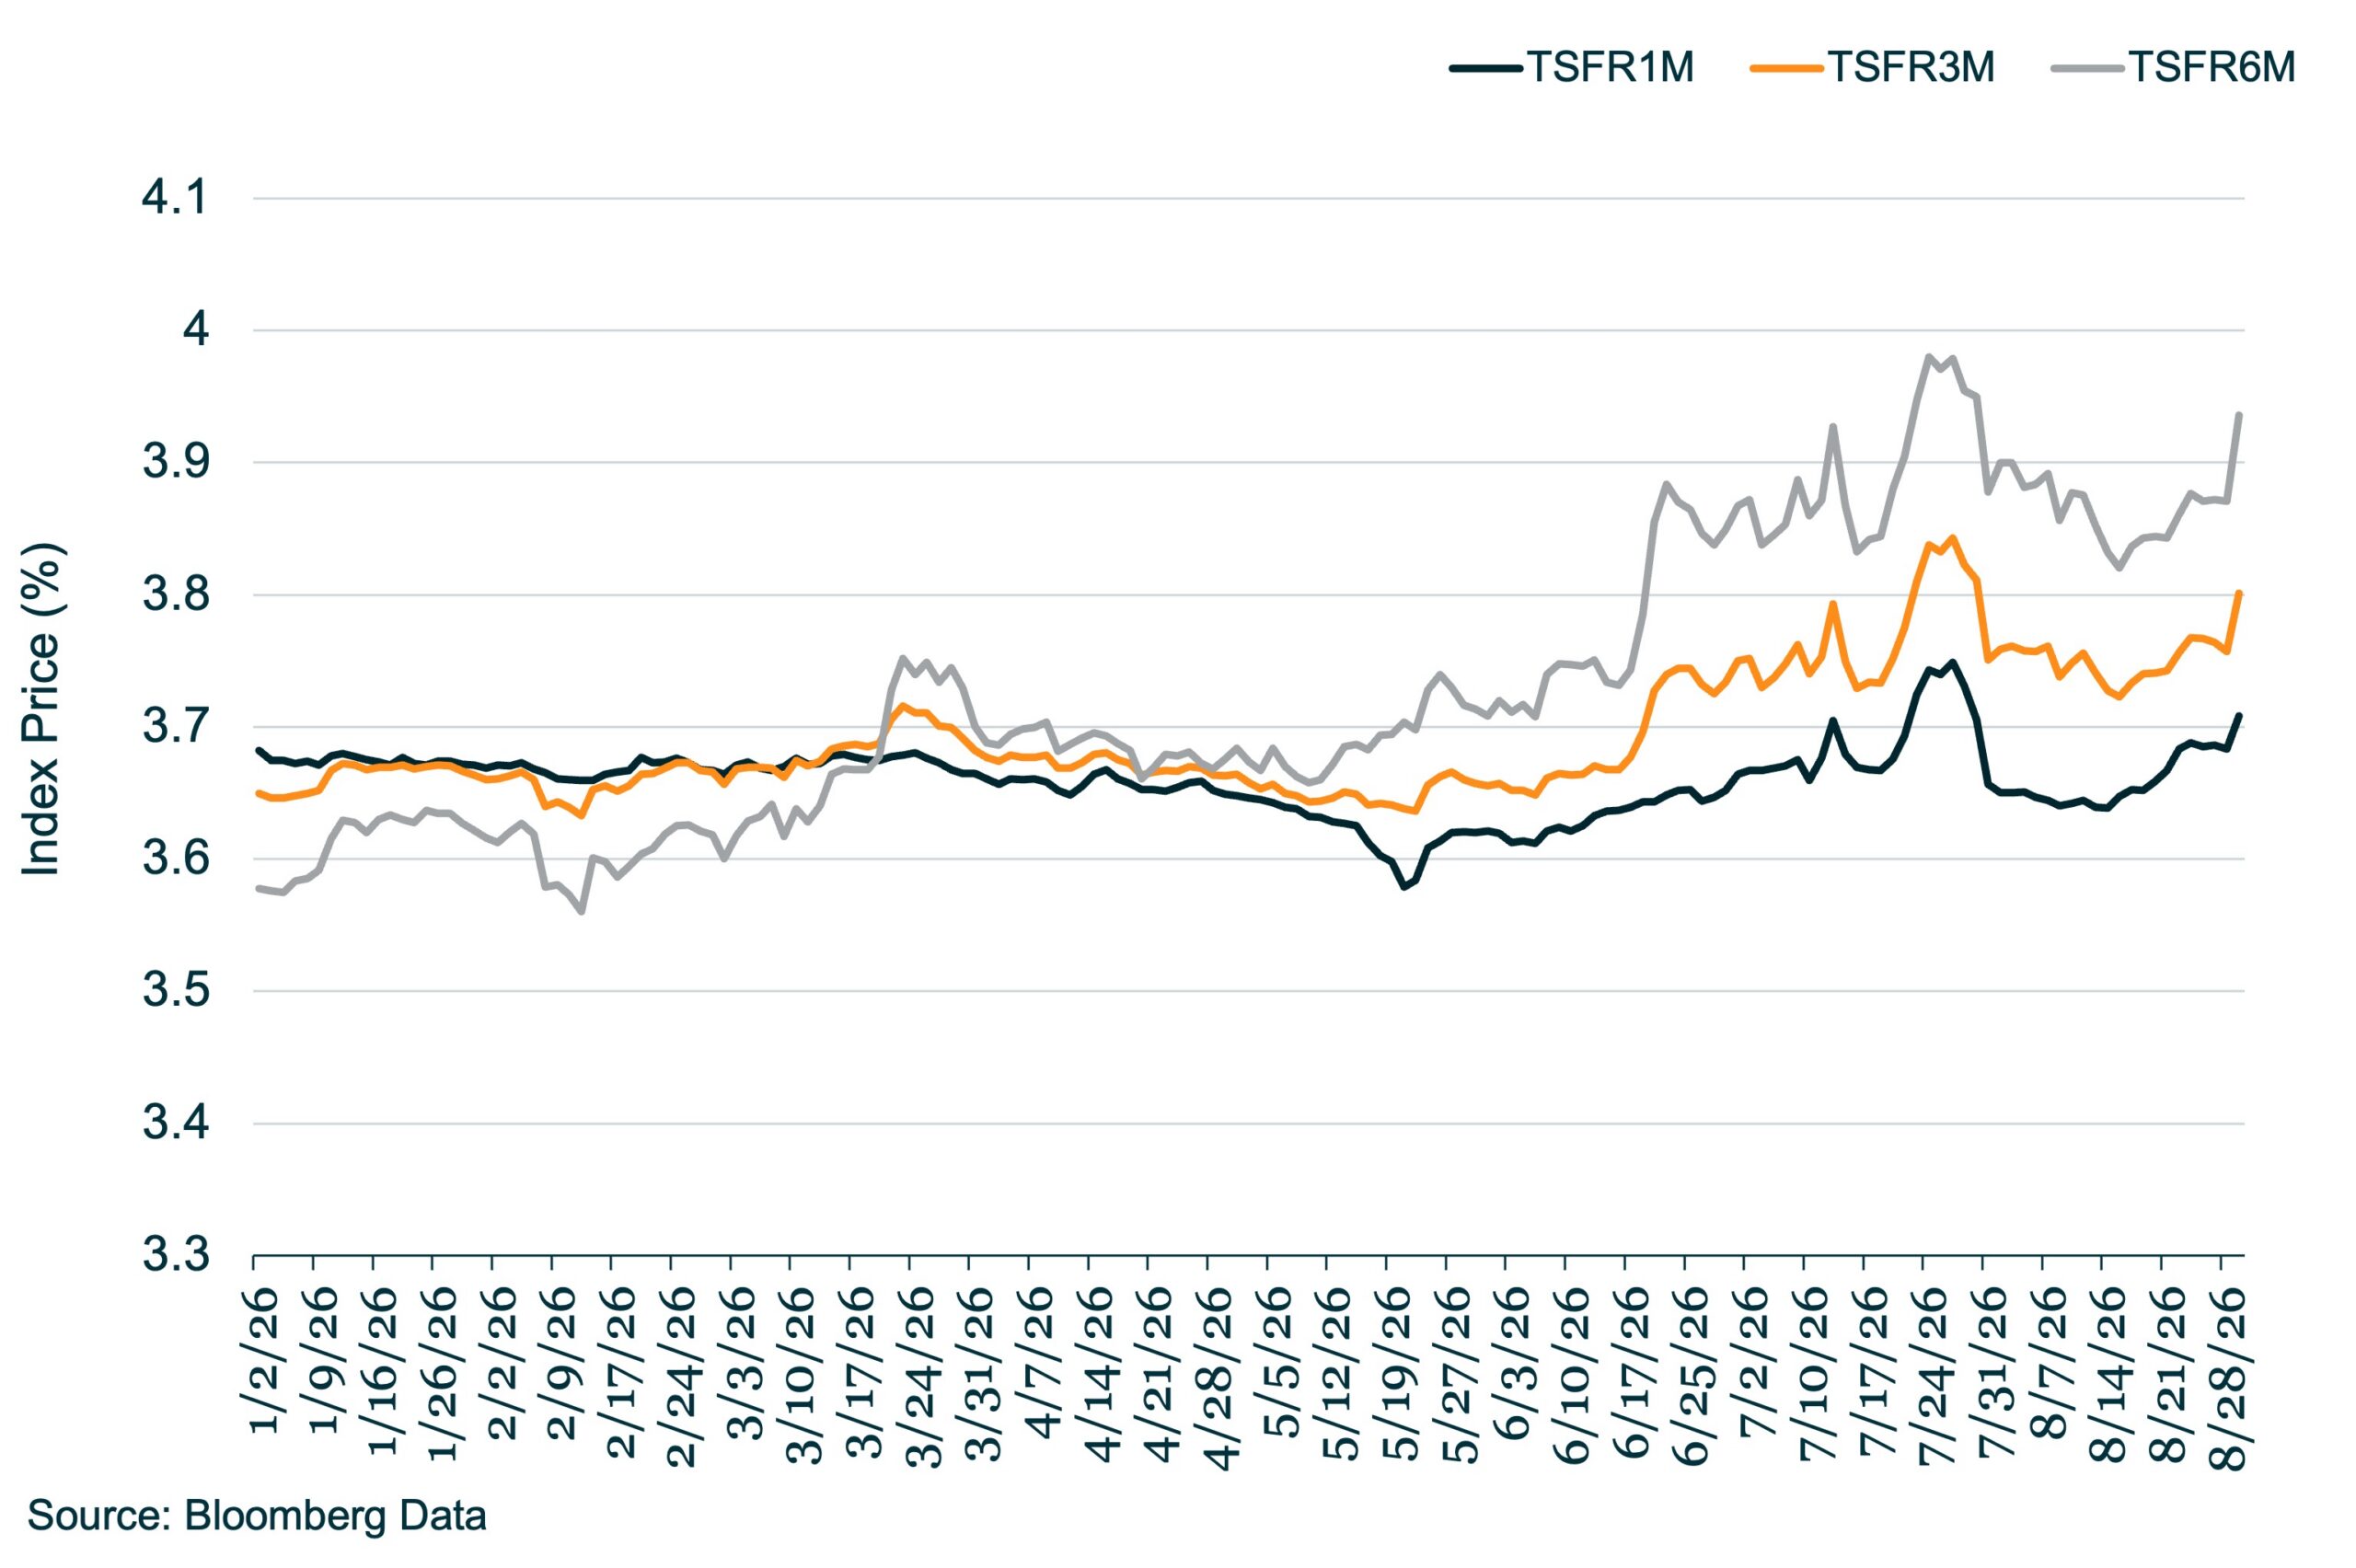
The CME six-month Term SOFR rate reached a recent high of 3.979% on July 28 before retreating to 3.821% as of August 17. Over the same period, the six-month premium over one-month Term SOFR narrowed from a high of 25 basis points to 17bps. Since then, the premium has ticked back up to 22.8bps as expectations for tighter monetary policy have rebounded.
Following the Federal Open Market Committee meeting on July 29, six-month Term SOFR declined by approximately 10bps over the subsequent three sessions. The rate fell another 5bps following the weaker-than-expected August 7 employment report, further tempering expectations for tighter monetary policy. That changed after Fed Chair Kevin Warsh’s August 28 speech at Jackson Hole, when the six-month rate gained 6.5bps following hawkish remarks on inflation.
The shift in rate expectations has been significant since the beginning of the year. In January, one-month Term SOFR traded at a 10.5 basis point premium to the six-month benchmark, reflecting expectations that the Federal Reserve would continue easing monetary policy. That dynamic reversed on March 19, when the curve inverted and six-month Term SOFR moved to a premium over the one-month rate, signaling a meaningful shift toward a more hawkish outlook. That hawkishness peaked in late July but has reignited ahead of the September FOMC meeting.



Latest news

PIK Your Next Adventure
Every amended PIK loan hits the same crossroad. Not everyone ends up at the same destination.

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.
Private Credit Defaults 101: Beyond the Noise
Like any good school year, this series went by fast. But unlike the end of the year, we’re not out for the summer.