


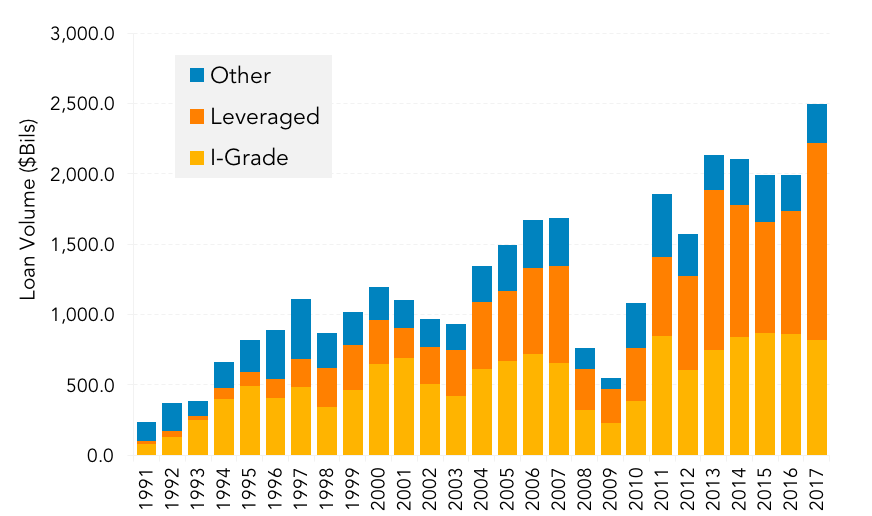
Despite the din of geopolitical noise in the background, 2017 was a remarkably steady year in the loan market, punctuated by an especially strong finish in the last few weeks of 4Q17. At US$2.5Tr, full year 2017 US syndicated loan volume was up 26% compared to 2016 results to set a new record. At US$790bn, new money represented 31.5% of total lending, but fell short of lender demand for assets. After a relatively slow start to the year, M&A lending gained momentum culminating in US$537Bn of issuance , a 12% increase over 2016 results. Both investment grade and leveraged issuers benefitted. High grade, jumbo financings backing Amazon’s purchase of Whole Foods as well as CVS’ anticipated takeover of Aetna among others, made headlines and were studiously supplemented by a steady calendar of generally smaller leveraged transactions. At US$126Bn, loans backing buyout deals surged to mark the highest total annual figure since the record setting US$210Bn raised in 2007. Refinancings remained a cornerstone of lending activity – most notably among leveraged issuers taking advantage of highly liquid market conditions, while investment grade issuers focused on shorter dated backstop credits with an eye toward anticipated changes to corporate tax rates and repatriation of cash.
Contact: Maria Dikeos
maria.dikeos@thomsonreuters.com



Latest news

PIK Your Next Adventure
Every amended PIK loan hits the same crossroad. Not everyone ends up at the same destination.

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.
Private Credit Defaults 101: Beyond the Noise
Like any good school year, this series went by fast. But unlike the end of the year, we’re not out for the summer.