


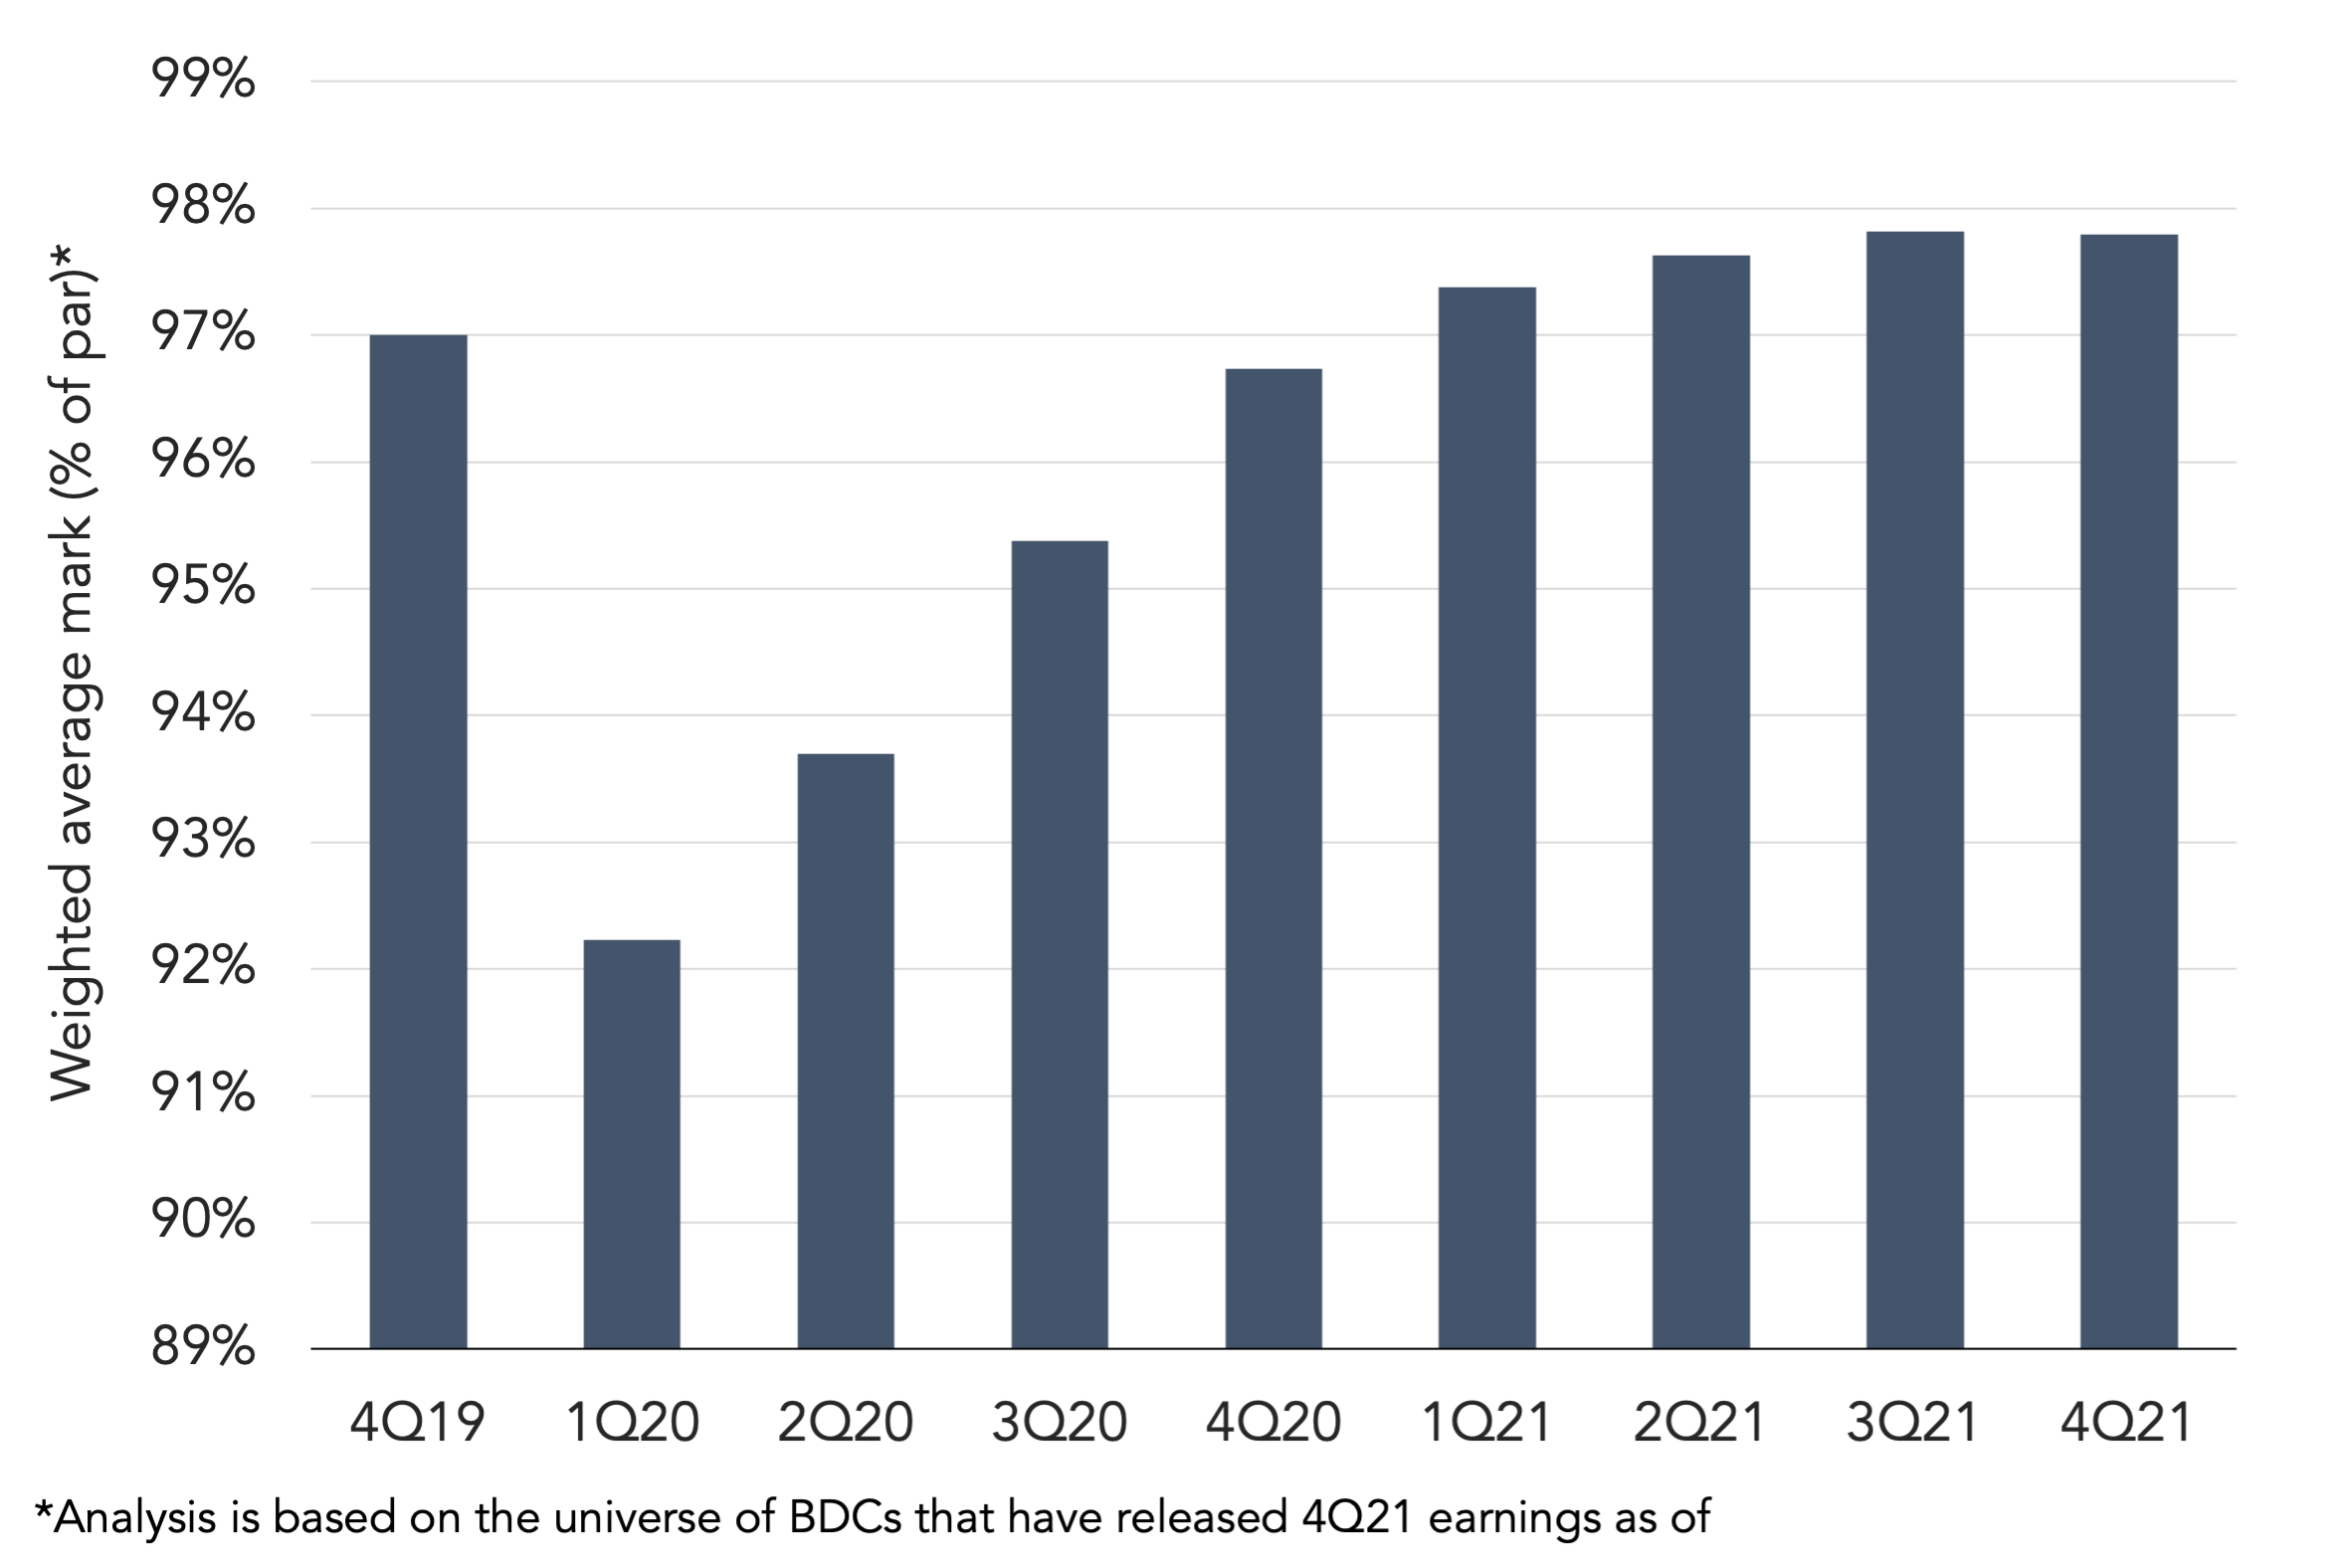
The most recent data from BDC earnings season shows that debt valuations stabilized in 4Q21, as price appreciation finally eased off, following a huge rebound from the lows seen in 1Q20 when COVID first hit.
Looking at the cohort of BDCs that have filed as of March 1, the weighted average mark on debt holdings finished 4Q21 at 97.80, relatively unchanged from 3Q21 levels. However, 4Q21’s level is up year-over-year from the 96.73 posted in 4Q20 and is far above the recent low of 92.23 set in 1Q20. At a more granular level, both first-lien and second-lien loan valuations edged lower in 4Q21, while subordinated debt climbed higher.
More recently in 1Q22, valuations of actively marked BDC loans have slipped amid increased financial market volatility following the Russian invasion of Ukraine. The Refinitiv LPC BDC Visible Loans Benchmark (comprised of $19bn in BDC held loans) currently has a weighted average bid close to 97, down around 100bp since mid-January.
(Past performance is no guarantee of future results.)




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…