


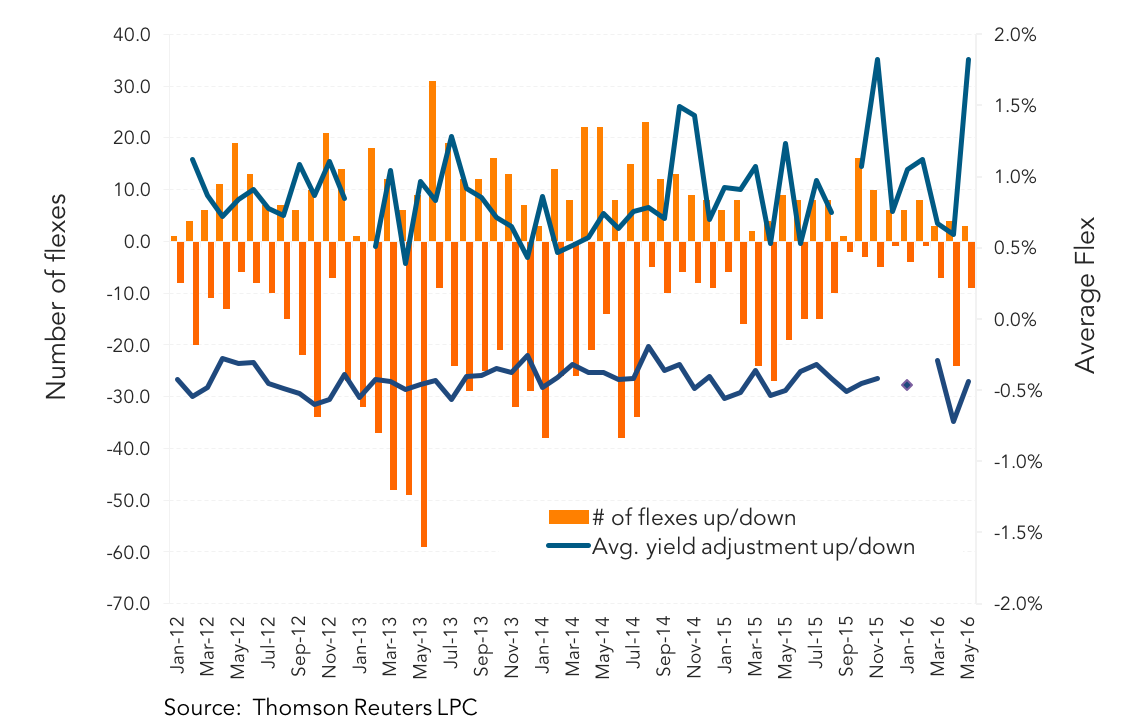
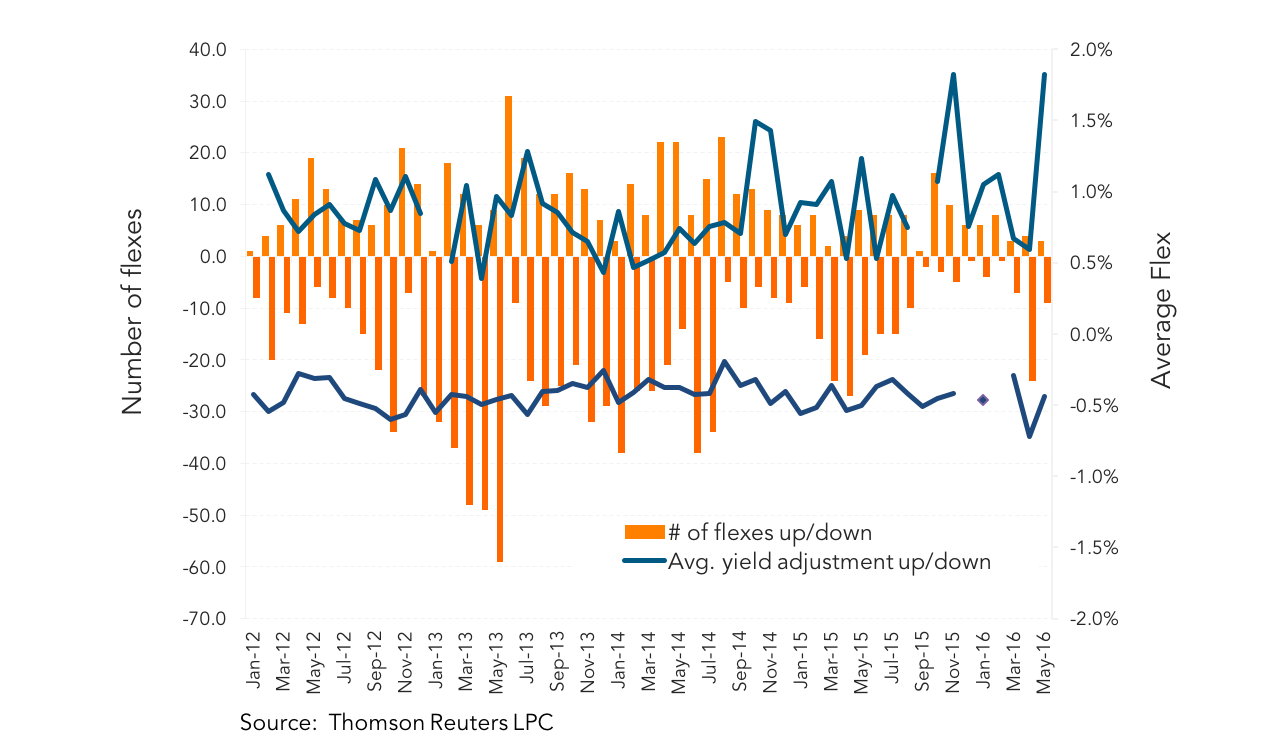
Downward flexes continue at the forefront of flex activity so far in May. There have been three times more downward price flexes than upward price revisions this month. However, with nine downward flexes so far, May is trailing the 24 price cuts tracked in April. Terms continue to favor issuers this quarter, and at 33 so far, downward price flexes are up over four times the total logged in 1Q16. At the same time, upward price revisions have dropped 50% to seven so far in 2Q16. With the supply of loans falling short of demand, terms continue to favor issuers, and yields have tightened significantly.
Downward flexes dominate but slow down in May
The average yield, assuming a three-year term to repayment on first-lien institutional term loans is 5.82% so far this quarter, down 70bp from 1Q16 levels. Issuers have taken notice and repricings and dividend recaps, which had been absent for a while, are making a showing and getting attention. US Farathane accelerated the deadline on its US$80m incremental term loan and existing US$474.5m repriced term loan. Also the discount on the dividend tranche was tightened to 99.25 from 99.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
