


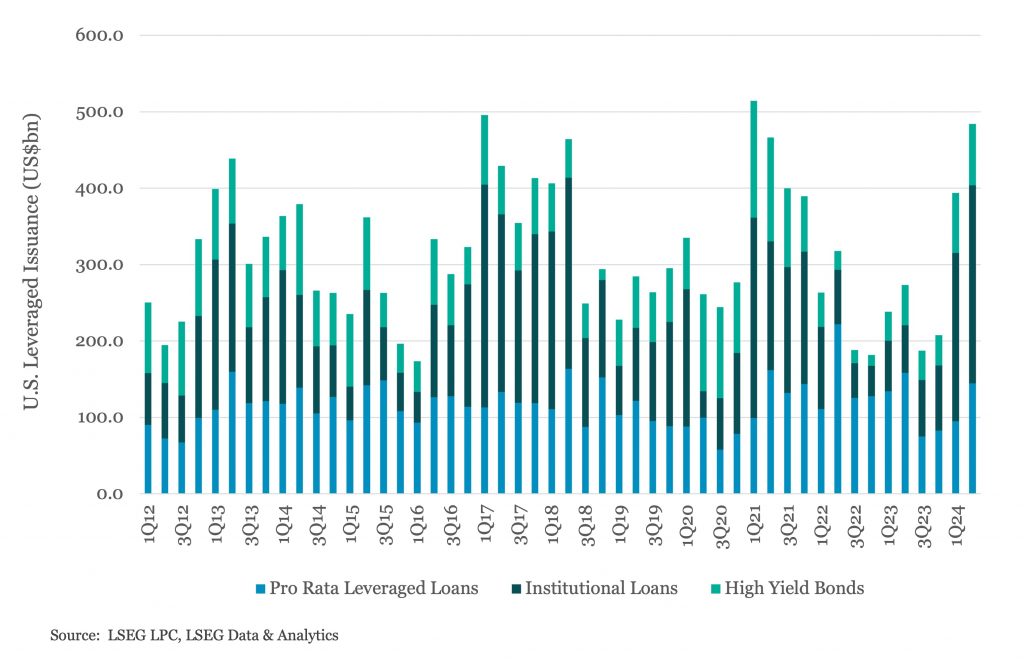
Leveraged issuers raised over US$484bn via the loan and high yield bond markets in 2Q24, the strongest quarterly results since 1Q21. Off a low base, 2Q24 leveraged corporate M&A and LBO lending was up 13% and 80% respectively year over year at roughly US$16bn and US$21bn. The vast majority of dealflow came in the form of refinancings and repricings however. Just under US$260bn of institutional loan volume worked its way through retail syndication during this quarter. Of this total, almost half, US$124bn, represented repricing events. Almost US$144.6bn of pro rata leveraged loan volume was cleared the market, down roughly 9% year over year but up over 52% quarter over quarter. Finally, amid significant overall investor liquidity and tightening spreads, HY bond volume has been running at about US$32bn a month, with May issuance marking a high, before slowing down in June. Ultimately, over US$80.5bn in HY bond volume was issued, the highest quarterly total since 3Q21.




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…