


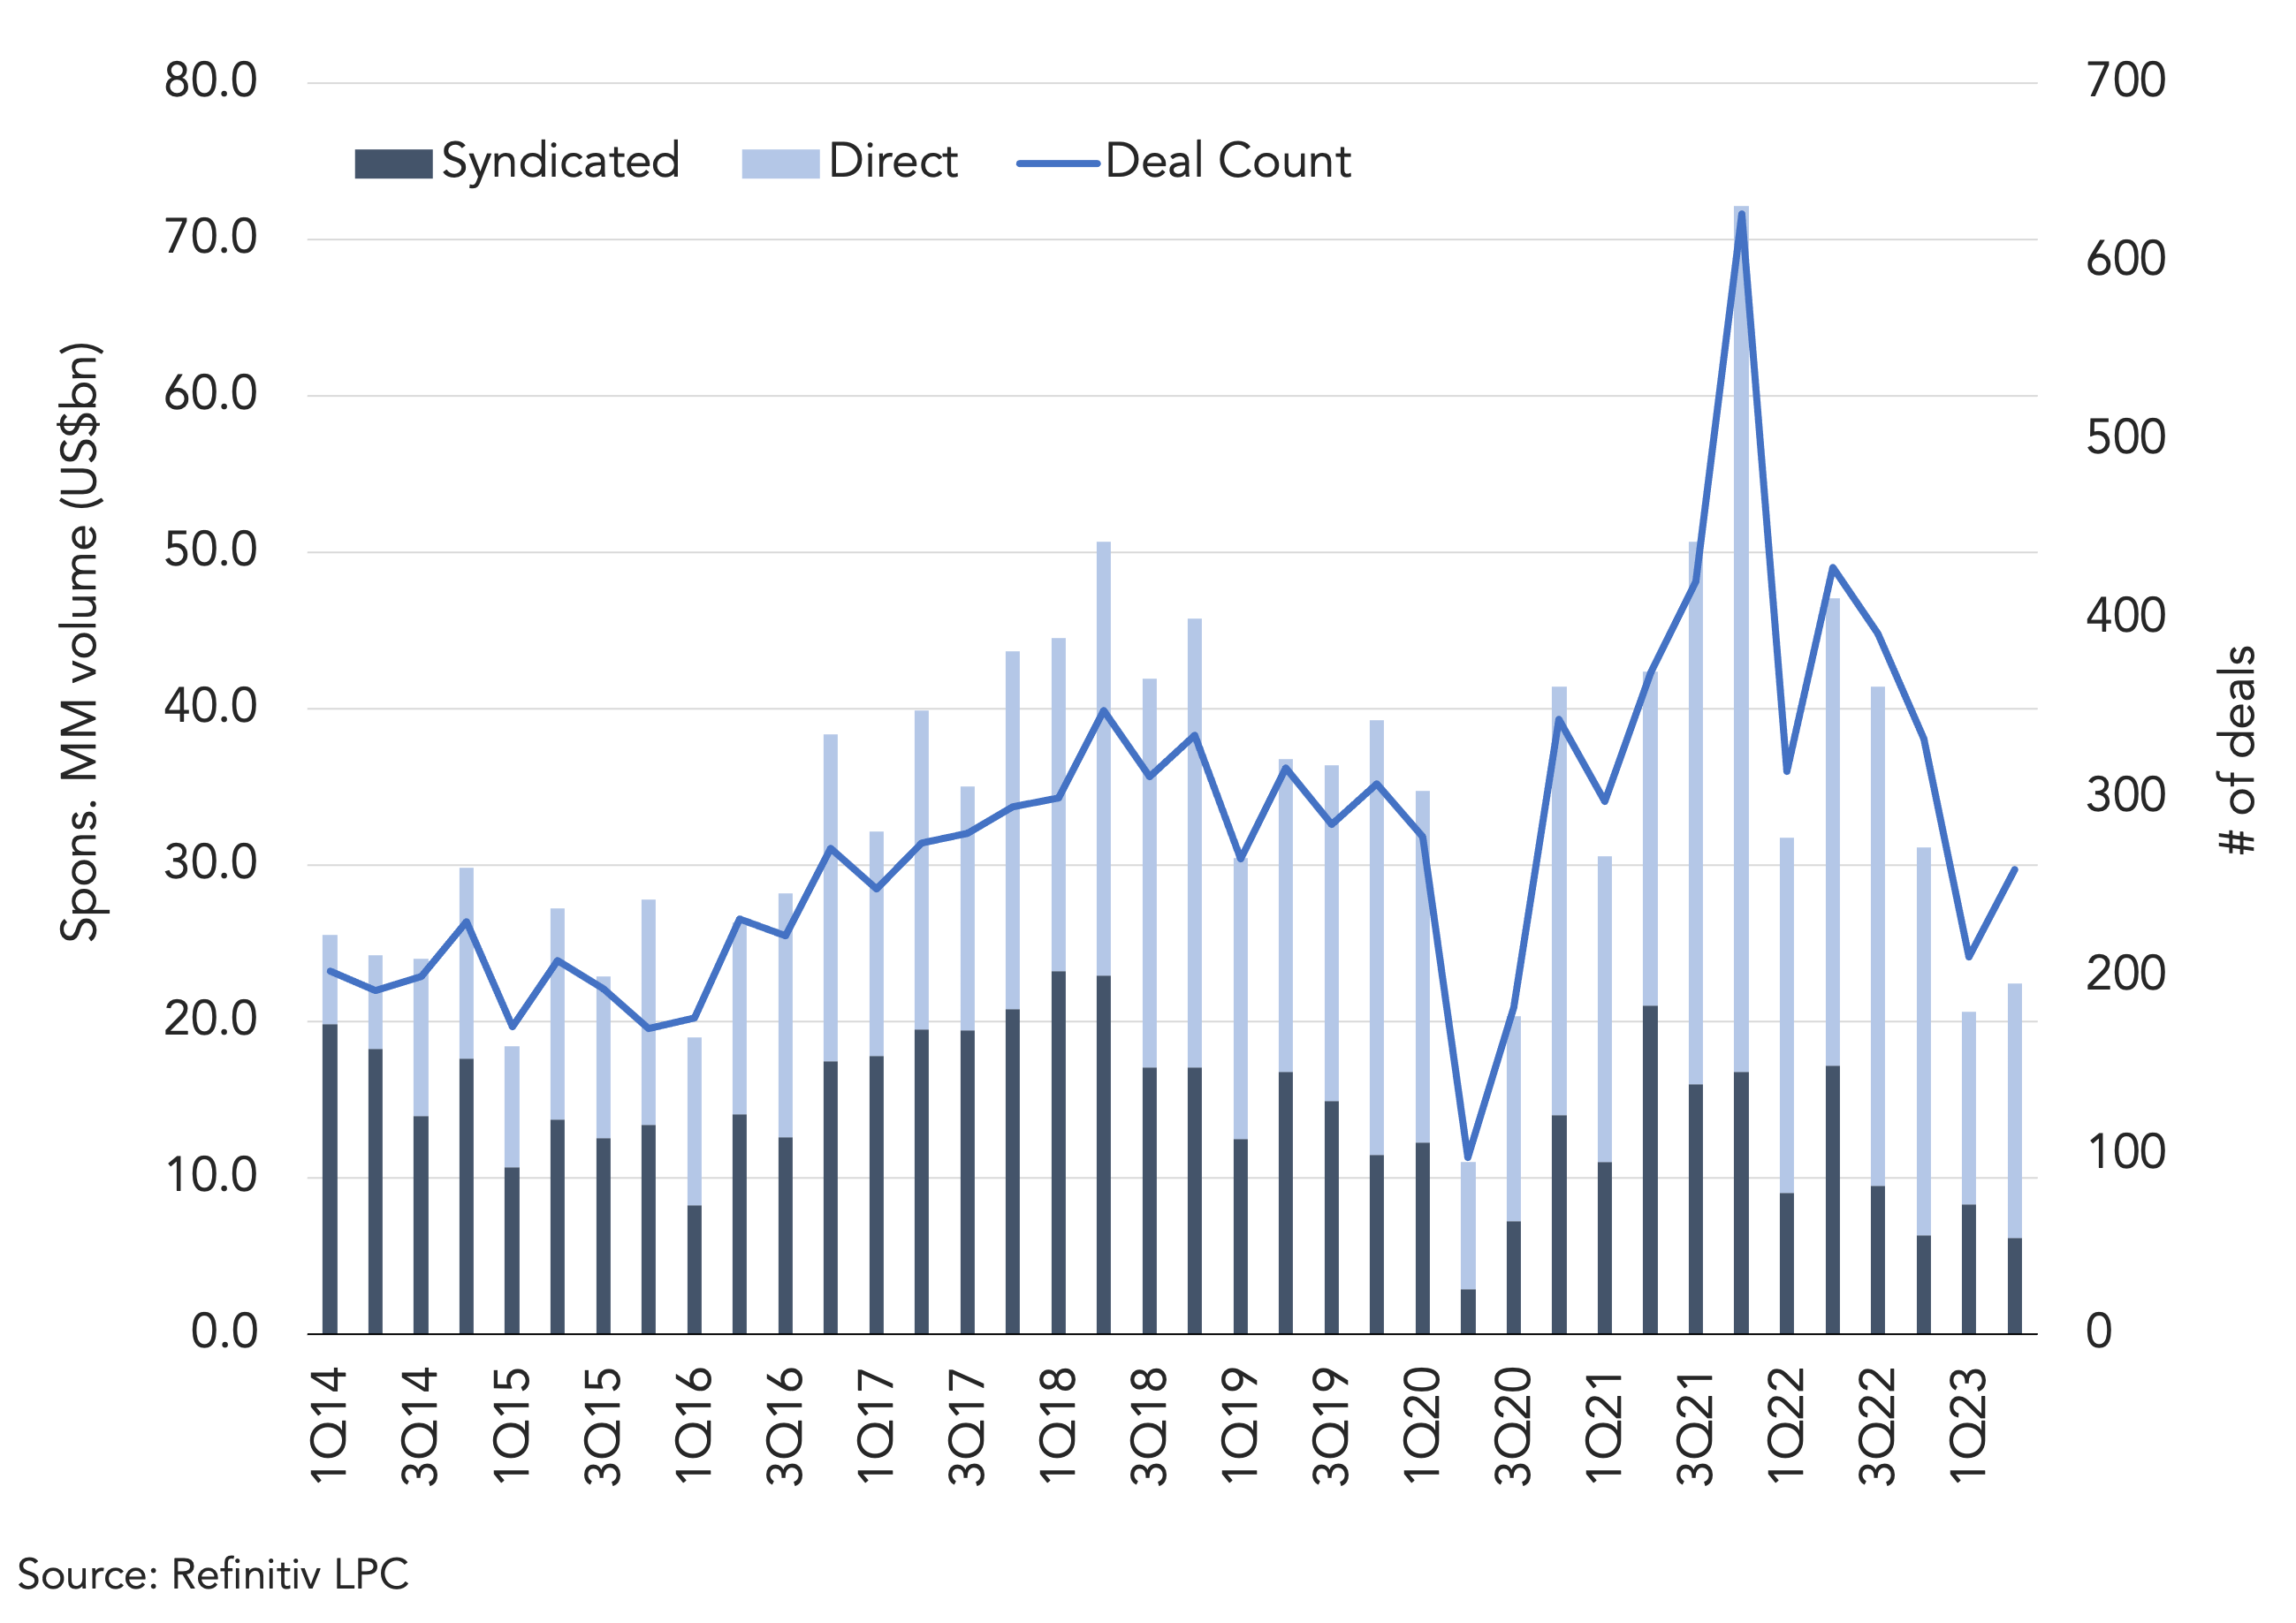
Activity picked up in the US middle market direct lending space in 2Q23 but remained at lower levels. At US$16.3bn, sponsored middle market direct lending volume was up 32% from 1Q23 but was down 46% year-over-year. In contrast, the syndicated sponsored market slowed down relative to 1Q23, with issuance dropping 26% quarter-over-quarter and a whopping 64% from 2Q22. In turn, the ratio of direct lending to syndicated loan volume climbed to 2.6 times after dropping to 1.5 times in 1Q23. Finding quality deals, low M&A activity and more selectivity continue to be the main factors hindering activity in the sponsored market.
(Past performance is no guarantee of future results.)




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
