


Total leverage on sponsored middle market deals ticked up in the 2Q 2025, driven by higher senior leverage
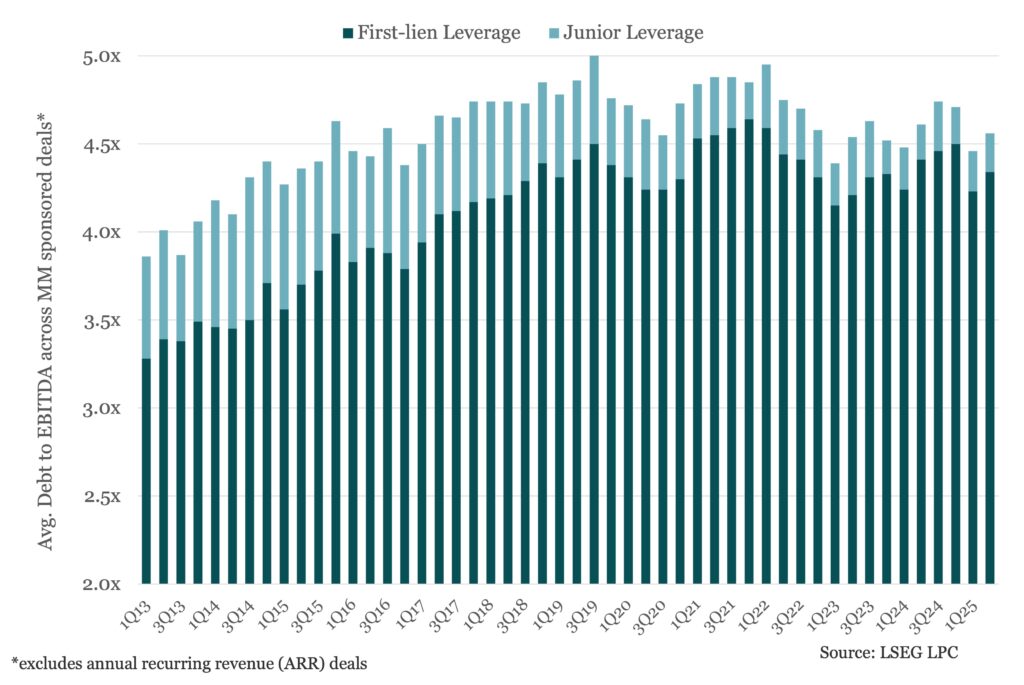
Total leverage on sponsored middle market deals ticked up to 4.56x on average in 2Q25, driven by higher senior leverage. First-lien leverage came in at 4.34x, up from 4.23x in 1Q25, while junior leverage edged down to 0.22x from 0.23x. Though leverage climbed in 2Q25, it remained slightly below the level recorded in the same quarter last year (4.61x). Looking at leverage levels by capital structure, middle market unitranche transactions averaged 5.55x in 2Q25, while all senior/senior stretch deals edged up to 3.89x. Though few in number, first-lien/second-lien structures saw a jump in leverage to 6.21x on average.



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.