


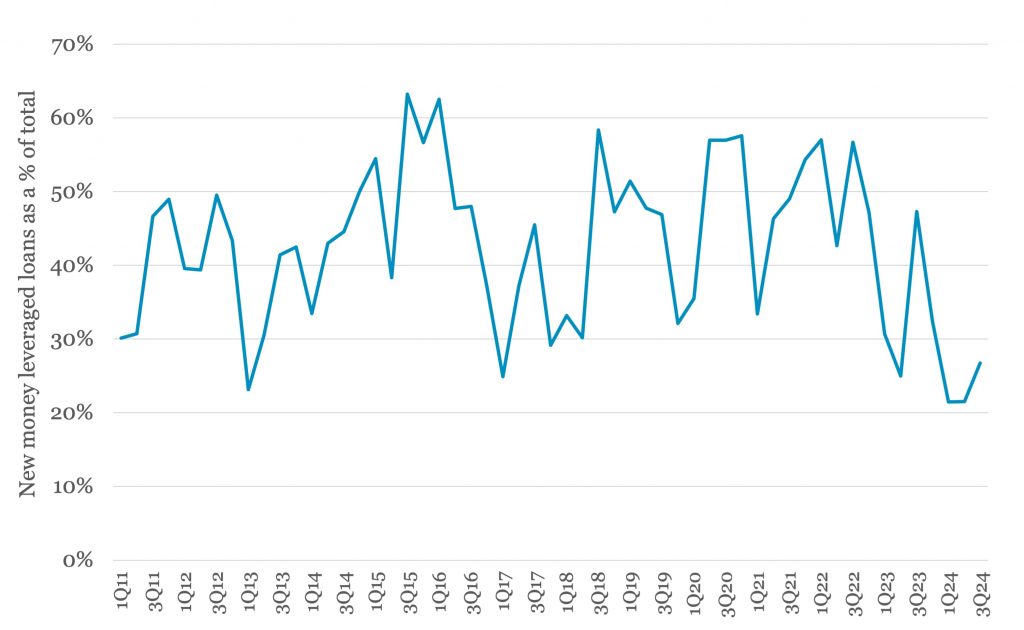
After a slow start to the year, leveraged issuers are increasingly tapping lenders for new and/or incremental loan capacity. In 3Q24 to date, 27% of total leveraged loan volume came in the form of new assets, up from 21% and 22% during each of the first two quarters respectively. Of this, over US$10bn represents completed 3Q24 LBO loan volume (an additional US$16bn is in process). Lenders expect the launch of a US$2.05bn financing backing KKR’s purchase of Infrastructure to come to market before year end. More immediate is the scheduled launch of US$1.55bn in loans to support KKR’s acquisition of Janney Montgomery Scott, a wealth management firm, this week.


Latest news
Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.
Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…