


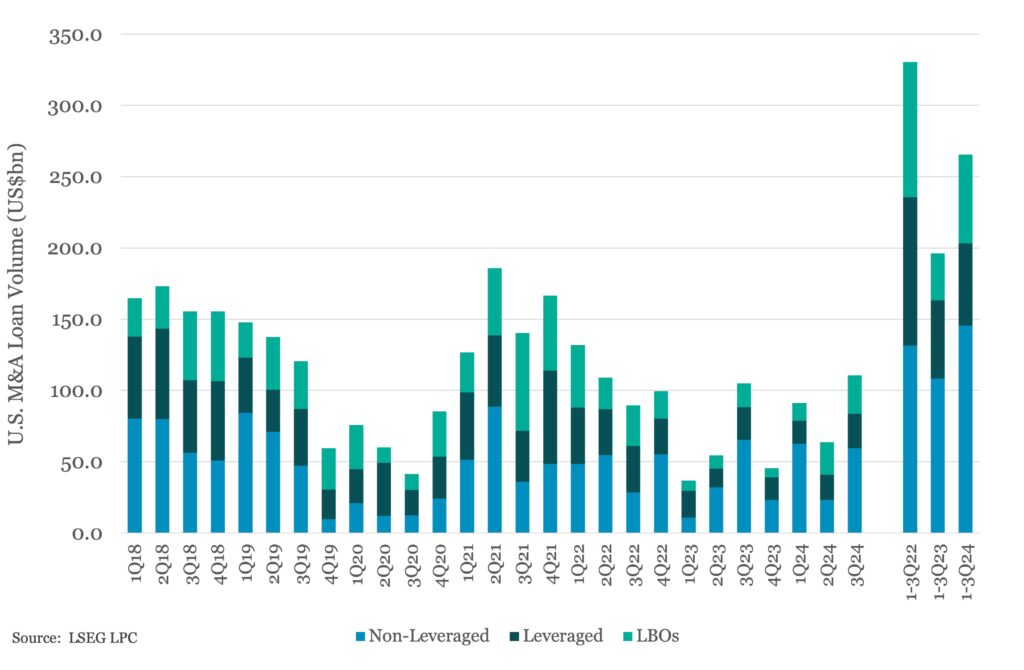
The US broadly syndicated loan market supported over US$110.5bn of acquisition financing in 3Q24, the strongest quarterly results in over two years, pushing 1-3Q24 totals to nearly US$266bn. Issuance for the first nine months was up 35% year over year. After a slower than expected 2Q pipeline, both investment grade and leveraged M&A ticked up markedly in 3Q24. A flurry of large, high grade issuers tapped lenders for nearly US$60bn of issuance, a 34% jump compared to 2Q24 results but modestly off the US$62.5bn raised in 1Q24 and the US$65.4bn raised during the same time last year. In the leveraged space, both corporate and private equity backed M&A credits came to market. Corporate issuers tapped lenders for over US$24bn in acquisition related financing, a 6% increase compared to the same time last year, pushing totals for the first nine months of 2024 to nearly US$58bn. But it was the re-emergence of steady LBO issuance via the BSL market that raised arranger hopes. Lenders supported almost US$27bn in LBO loan volume during the quarter, up 60% increase compared to the same time last year. At US$62.25bn, 1-3Q24 LBO loan volume was up 88% compared to US$33bn raised in the year ago period.




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…