



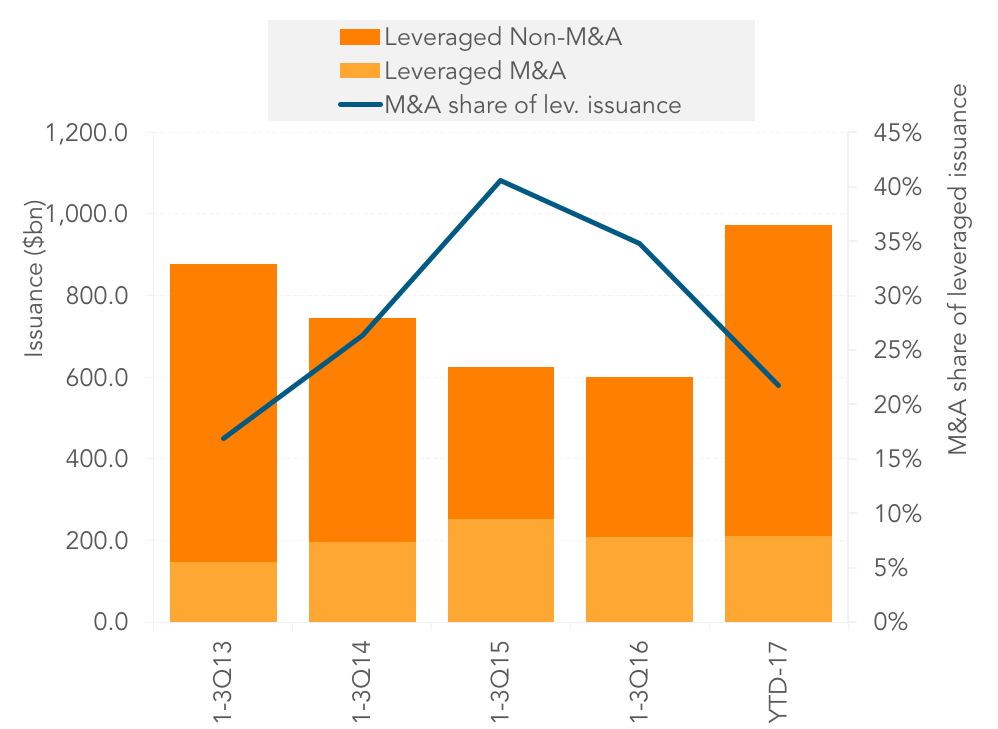
The leveraged loan market has not looked like it will slow down anytime soon. Year-to-date completed issuance stands at US$972bn through the end of August. That is higher than any post-crisis year through 3Q while another roughly $35bn sits in the pipeline for September. While the first half of the year was dominated by repricings, M&A activity has taken a larger share in the months since. So far this year, 22% of leveraged issuance has been in the form of M&A. By comparison, in 2013, when leveraged issuance hit a post-crisis high, M&A issuance comprised a lower 17% share of overall leveraged issuance. A lot of this M&A activity has been in the form of LBOs. August saw over US$17bn in completed LBO issuance compared to US$7.7bn in August 2016. LBO deals launching this week include Trimark, Advisory Board Co and Corsair. Investor demand for leveraged loans has been strong this year. CLO issuance has exceeded expectations while retail loan funds saw consistent inflows the first half of the year. And while market concerns remain, whether in the form of lack of action out of Washington, North Korea concerns or hurricane recoveries, the market has for the most part shrugged them off. This should allow the leveraged loan market to continue full speed ahead in the near term.
Contact: David Puchowski
David.Puchowski@thomsonreuters.com




Latest news

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Reading the Board
The story changes depending on which numbers you’re counting.
Private Credit Defaults 101: Different Numbers, Different Stories
In Season 2 of Billions, Bobby Axelrod takes his lawyer Orrin Bach to an empty Yonkers racetrack in the dead of night.