


Markit Recap – 5/29/2017

Italian banks give up gains
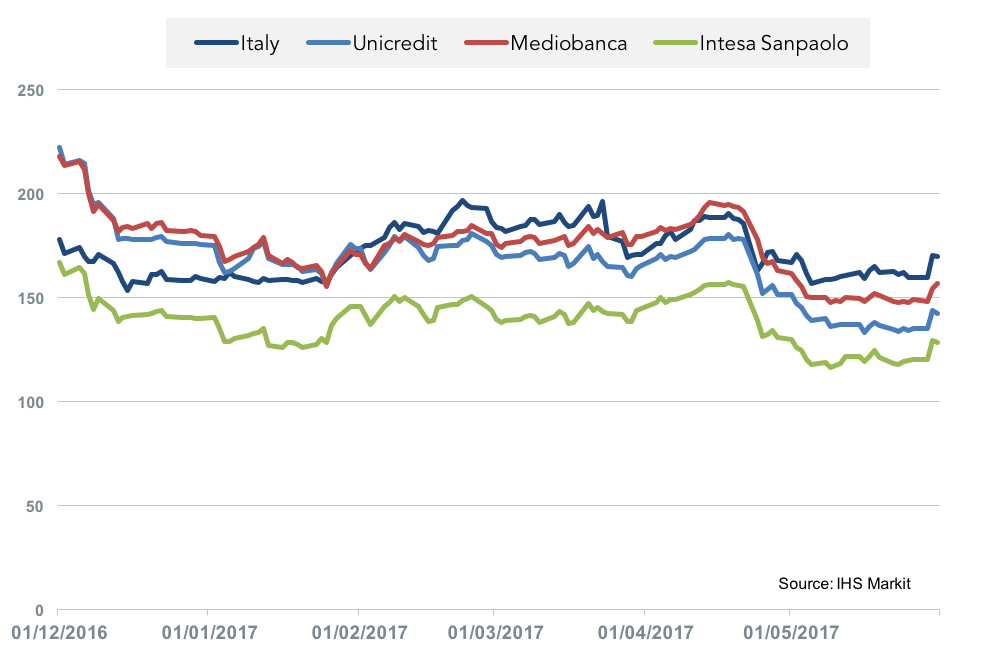
We posited after the French election that Italy was now the most likely country to trigger a material bout of political risk.
Italy, of course, is no stranger to instability, having had 42 prime ministers since World War II. But it didn’t have an election scheduled for this year, with 2018 the most likely time to go to the polls.
That changed this week, however, after a new law was proposed that would change the electoral system to German-style proportional representation. If passed in parliament, this would clear the way for a snap election.
Italy has innumerable economic challenges – not least a 132% debt/GDP ratio – so a period of political uncertainty is the last thing it needs. It may be difficult to form a stable coalition, particularly with the populist Five Start Movement riding high in the polls.
But the reaction in the credit markets was relatively muted. Italy’s sovereign CDS widened 10bps from 160bps to 170bps. While not insignificant, this move only brought the country’s spreads to levels reached at the beginning of May, and spreads were close to 200bps earlier this year.
It is by no means certain that there will be an early election, as the president and parts of parliament may oppose going to the public this year. Nonetheless, Italy’s highly liquid CDS will be the barometer to watch as the situation evolves.
Italy’s public debt is not its only challenge. A mountain of non-performing loans has been bearing down on the country’s banking sector for some time. Ignazio Visco, Bank of Italy governor, warned that the banking system will suffer higher than forecast losses from bad loans at current market prices. On the plus side, a preliminary agreement on a state bailout for Monte dei Paschi di Siena (MPS) was reached between the European Commission and the Italian government. This should put MPS – which is the country’s weakest major bank – on a surer footing.
A bailout will likely trigger the bank’s subordinated CDS as bondholders will share the burden of a bailout. Senior CDS won’t trigger under 2014 definitions, though it is a different story under 2003 rules. MPS subordinated five-year CDS has been quoted over 64 points upfront and has a steeply inverted curve, both indications of a high probability of default.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com



Latest news

With Inflation Running Hot, Rate Hike Expectations Strengthen
A hotter-than-expected inflation reading has renewed expectations for near-term Federal Reserve tightening. The Consumer Price Index rose 0.6% month-over-month, pushing…

Open Tab
Leveraged loans keep running up a tab. Senior direct lending already knows what it owes.
