


Markit Recap – 8/10/2015

Back in 2010, Brazil’s finance minister Guido Mantega warned that the world was in the midst of a “currency war” in the wake of US quantitative easing. The term is now back in vogue after China made the shock decision to devalue its currency.
China has a “dirty” peg against the US dollar, and the People’s Bank of China adjusted the managed float by 1.9%. This was the biggest one-day change since 1993, and the renminbi continue to depreciate the following day. Opinions differ on the rationale behind the decision. It appears to be a reaction to China’s lacklustre export performance in recent months, and in that sense it is the competitive devaluation that could escalate into the feared currency war.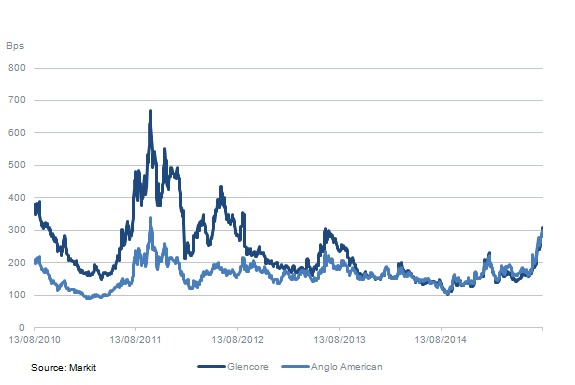 A more optimistic view is that it is a welcome move towards a “more market-determined exchange rate”, as stated by the US Treasury in its cautious response to the PBOC announcement. China is pushing to have the renminbi accepted as a reserve currency by the IMF, and this could be the first step.
If there is a positive side to China’s devaluation, the credit markets are not seeing it, at least not yet. The worst performers, unsurprisingly, were names with direct exposure to China. The prospect of a flagging Chinese economy is obviously detrimental to commodity firms, and they suffered disproportionately. Glencore’s CDS spreads widened beyond 300bps for the first time in over two years, and have now given up over 160bps since May. Anglo American also breached the 300bps level, the first time it has done so since October 2011.
North American indices were also driven wider by commodity-related names. But the most direct effect of China’s FX intervention was in emerging markets, where sovereigns in Asia saw their spreads widen significantly. Most of China’s regional neighbours are also export-driven, and the devaluation of the renminbi will make their goods less competitive in international markets. The policy response of governments in Asia, along with the extent China allows the renminbi to fall, will determine whether we do indeed enter a “currency war”. With US rates set to rise, emerging market debt could face a difficult end to 2015.
Contact: Gavan Nolan
Email: Gavan.Nolan@markit.com




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…